Oil versus Non-Oil Geopolitical Risk and US Industry Stock Market Volatility
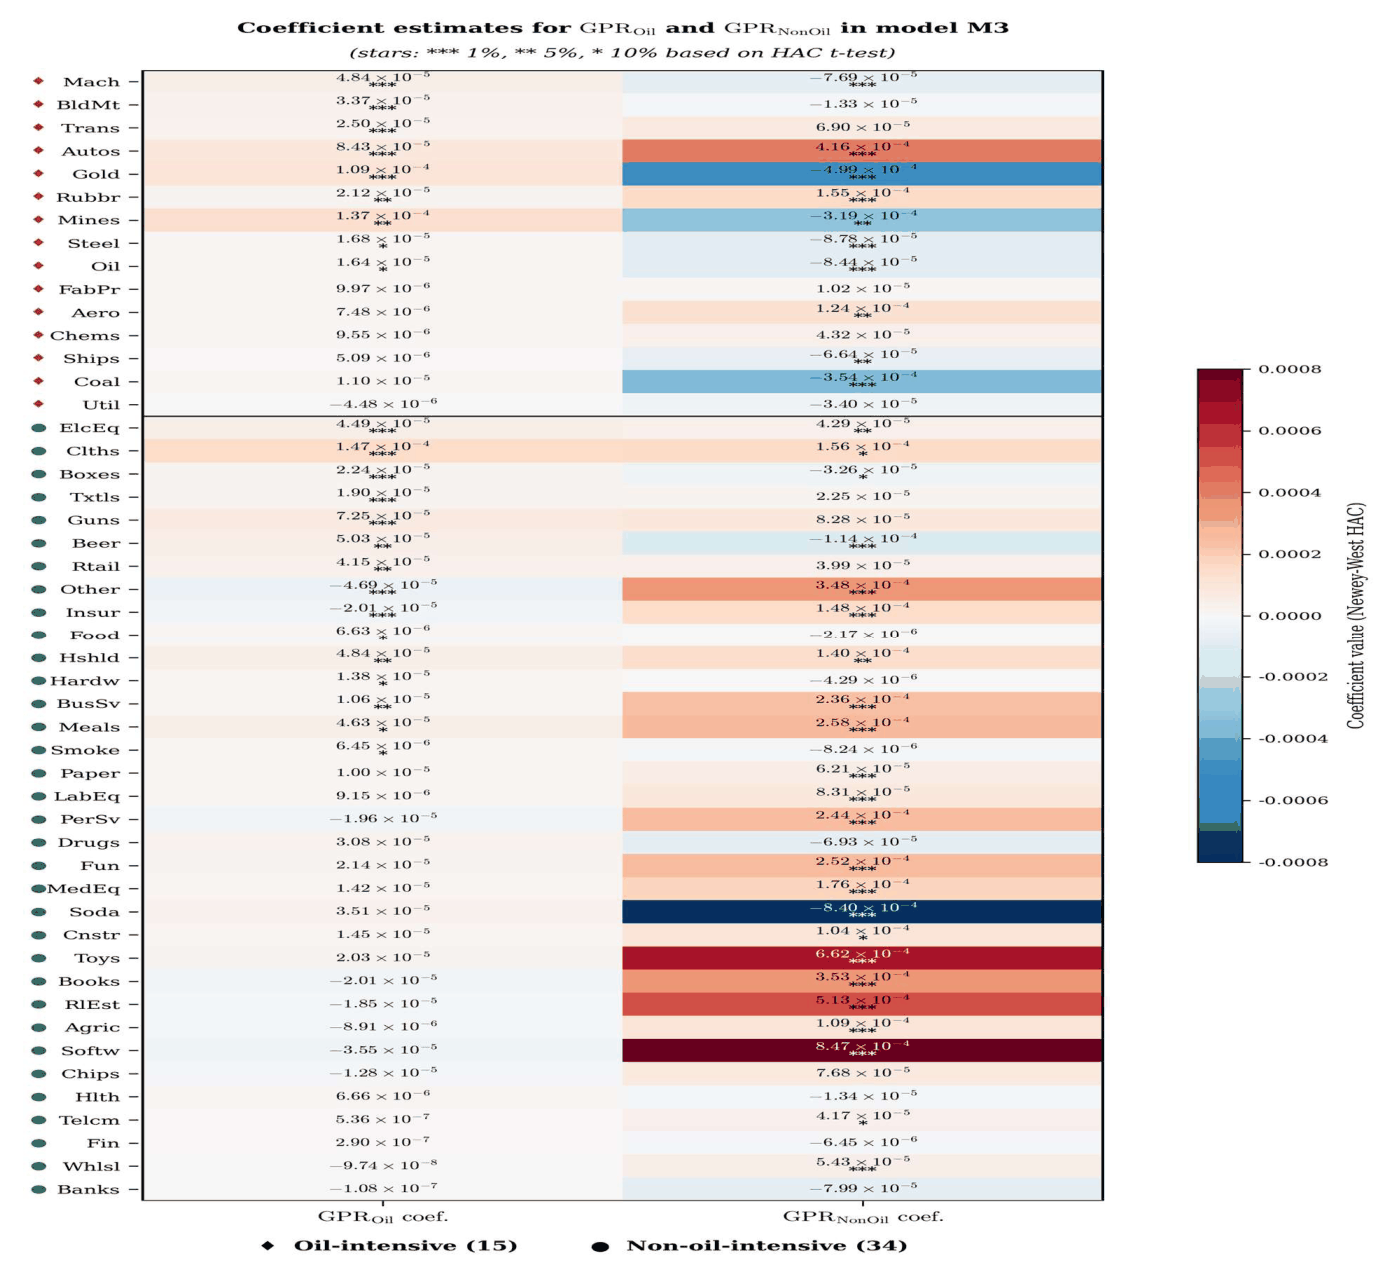
Decomposing geopolitical risk into oil and non-oil components predicts US industry stock volatility better than aggregate measures across 49 sectors.
Featured in No. 135 on 16 Oct 2026 · 7 days after release
- Released
- 9 Oct 2026
- First featured
- No. 135 · 16 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:pre:wpaper:202626
- Authors
- Onur Polat et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).