ML-QuantSubscribe

ML-QuantIssue No. 139

Quant research, ranked weekly.

Every Friday we screen every new arXiv, SSRN and RePEc paper, rank the best 30 per venue, pull each paper's key figure, and track what happens to it afterwards. Free for people. Open to agents.

Issues
139
Papers featured
7,026
Cited 100+ times
233
Quants on the radar
10.6k

This week's top picks

From issue No. 139. All 90 papers →

  1. Microstructure Invariance For Execution Policies

    An execution policy trained once on 954 stocks in normalized units generalizes to unseen assets, exchanges, and crypto with minimal performance loss.

    Fanfare 4Trading, Microstructure & Execution
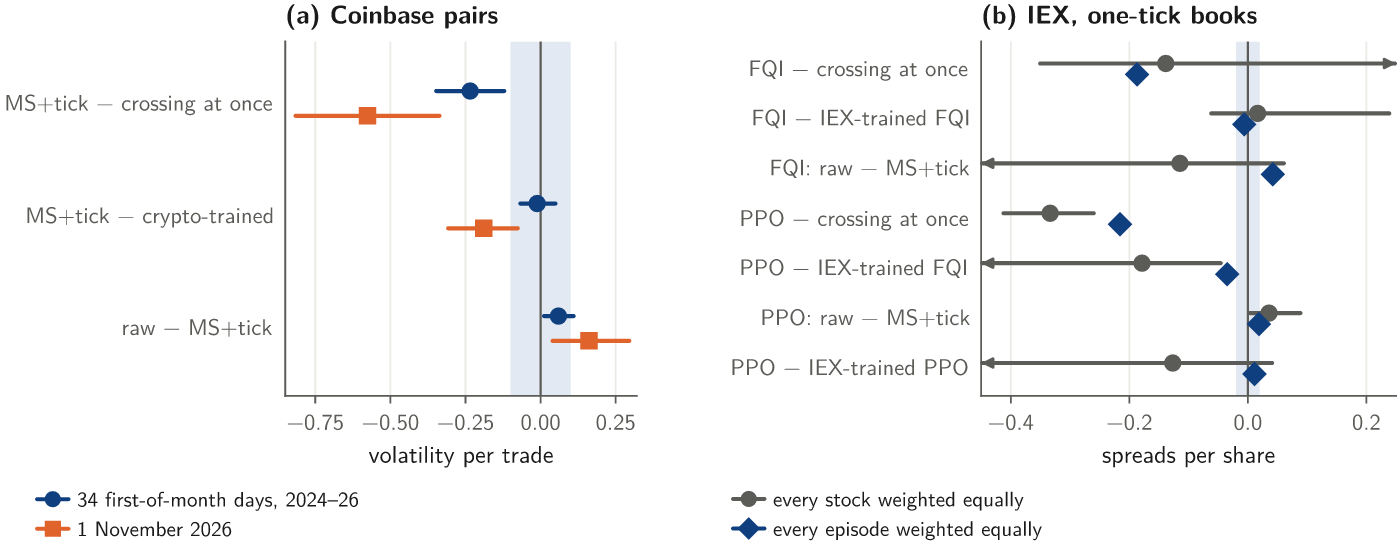
    Zero-shot policy transfer performance across crypto exchange and stock exchange pairs with confidence intervals.
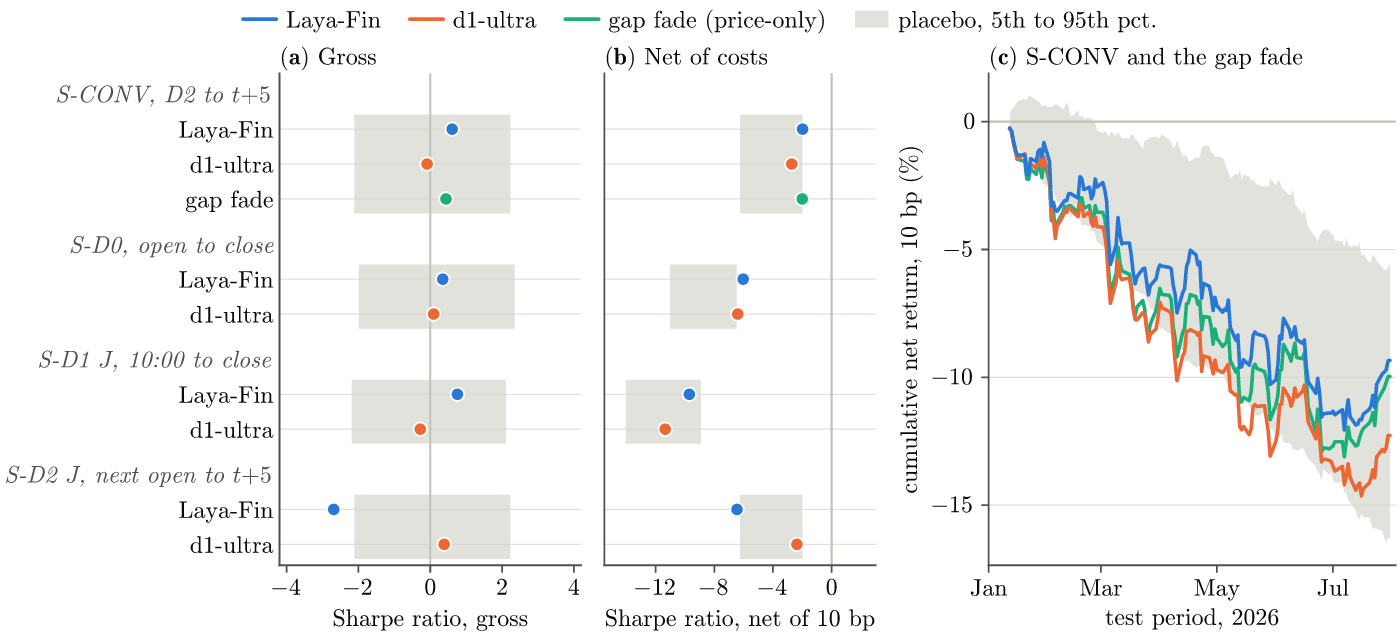
  2. Pre-registers and audits 91 LLM trading papers, finding 51% ignore trading costs, median test window is 12 months, and 98% fail to control for look-ahead bias in model training.

  3. Residual reversal timing and monthly aggregation weights
  4. A systematic audit of 1,820 economics and finance papers finds 10% of claims show discrepancies between code and description, with 49% containing potentially serious errors affecting central results.

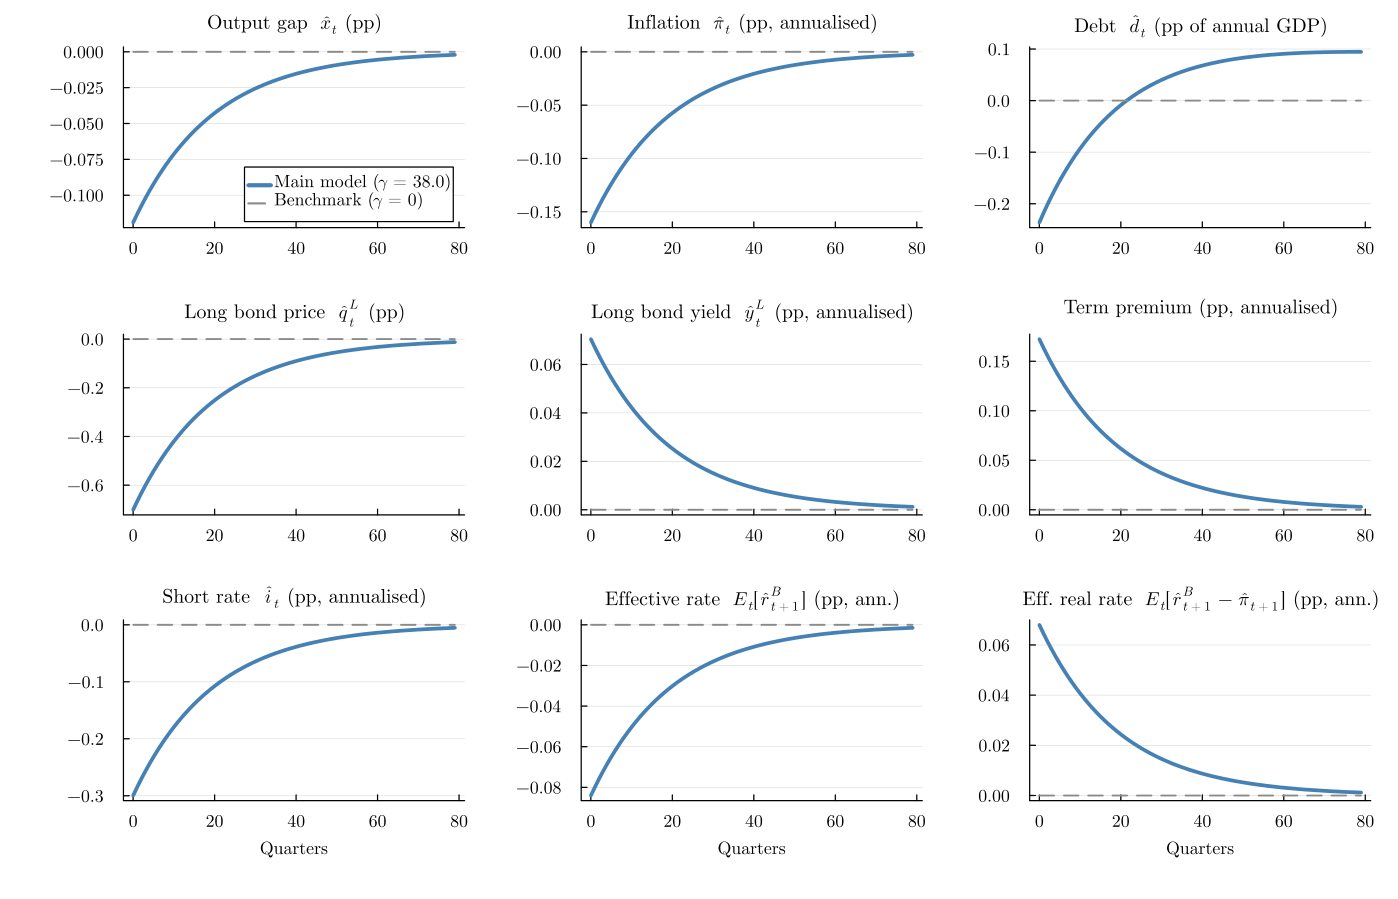
  5. Nine-panel grid showing impulse responses to maturity shock under monetary dominance

What's rising

Topics drawing unusually many papers this week.

  1. Earnings and analysts

    1.5×

    6.4% of this week's 689 new papers, 1.5x its share over the previous 7 weeks (4.3%).

  2. Foundation models

    2.1×

    1.9% of this week's 689 new papers, 2.1x its share over the previous 7 weeks (0.9%).

  3. Insurance

    1.5×

    4.5% of this week's 689 new papers, 1.5x its share over the previous 7 weeks (3.0%).

GitHub radar

What the quant community starred on GitHub this week, from a panel of 10,589 developers who follow financial machine learning (270 of the 857 we checked starred something). Counts only: we never publish who starred what.

Quant repos rising

  1. Personal finance app for managing money and budgets.

    ★ 14.5k+3,657 this weekRuby

  2. Self-hosted AI agent managing budget, investments, and trades.

    ★ 437+418 this weekPythonNew repo

  3. Forward-testing harness for trading crypto perpetuals on Bybit.

    ★ 145+145 this weekPythonNew repo

  4. Free open source order flow screener for spot and perpetual trading.

    ★ 184+151 this weekTypeScriptNew repo

  5. FinRL-X: AI-native modular infrastructure for quantitative trading.

    ★ 3,938+27 this weekPython

  6. Backtesting engine for quantitative trading and portfolio analysis.

    ★ 648+41 this weekPython

  7. Production-grade charting library for brokers and trading platforms.

    ★ 197+8 this weekTypeScript

  8. Foundation model for the language of financial markets.

    ★ 47.7k+655 this weekPython

What quants are playing with

  1. Agent skills framework for building AI agent capabilities.

    ★ 8,098+8,081 this weekNew repo

  2. Local emulator of AWS APIs for development and testing.

    ★ 6,507+6,510 this weekRustNew repo

  3. Python framework for semantic graph-based reasoning over data.

    ★ 12.5k+3,088 this weekPython

  4. Web best practices guidance for coding agents.

    ★ 9,906+7,280 this week

  5. Understand how software works and build your own.

    ★ 31.1k+12.3k this weekRustNew repo

  6. Open-source plugin for designing and reviewing software with agents.

    ★ 18.4k+5,239 this weekPythonNew repo

We called it

Every featured paper is tracked on Semantic Scholar. Of the finance papers we featured when new, 27% are now in journals.

  1. 534

    FinGPT: Open-Source Financial Large Language Models

    Featured 14 Jun 2023, 5 days after release

  2. 290

    FinMem: A Performance-Enhanced LLM Trading Agent With Layered Memory and Character Design

    Featured 29 Nov 2023, 6 days after release · IEEE Transactions on Big Data

  3. 258

    HybridRAG: Integrating Knowledge Graphs and Vector Retrieval Augmented Generation for Efficient Information Extraction

    Featured 15 Aug 2024, 6 days after release · Proceedings of the 5th ACM International Conference on AI in Finance

  4. 255

    TradingAgents: Multi-Agents LLM Financial Trading Framework

    Featured 1 Jan 2025, 4 days after release

  5. 195

    TKAN: Temporal Kolmogorov-Arnold Networks

    Featured 15 May 2024, 3 days after release

  6. 148

    Instruct-FinGPT: Financial Sentiment Analysis by Instruction Tuning of General-Purpose Large Language Models

    Featured 28 Jun 2023, 6 days after release

Browse by topic

Papers featured per quarter since May 2023.

  1. Crypto & DeFi

    Crypto & DeFi: papers featured per quarter

    Crypto assets, DeFi, stablecoins and blockchain markets.

    • Factors Influencing Cryptocurrency Prices: Evidence from Bitcoin, Ethereum, Dash, Litcoin, and Monero
    • Decentralised Finance and Automated Market Making: Execution and Speculation

    325 papers

  2. LLMs & Text

    LLMs & Text: papers featured per quarter

    Large language models, agents, sentiment and text as data in finance.

    • DeepSeekMath: Pushing the Limits of Mathematical Reasoning in Open Language Models
    • Mistral 7B

    605 papers

  3. Derivatives & Volatility

    Derivatives & Volatility: papers featured per quarter

    Option pricing, volatility models and forecasting, hedging and implied surfaces.

    • Risk Revisited
    • Rough Volatility: Fact or Artefact?

    921 papers

  4. Trading, Microstructure & Execution

    Trading, Microstructure & Execution: papers featured per quarter

    Order books, market making, execution, high-frequency data and trading signals.

    • FAST: Efficient Action Tokenization for Vision-Language-Action Models
    • Deep Reinforcement Learning for Active High Frequency Trading

    628 papers

  5. Portfolio & Allocation

    Portfolio & Allocation: papers featured per quarter

    Portfolio construction, allocation, rebalancing and risk budgeting, from Markowitz to deep RL.

    • Missing values handling for machine learning portfolios
    • AlphaSAGE: Structure-Aware Alpha Mining via GFlowNets for Robust Exploration

    668 papers

  6. Risk, Credit & Banking

    Risk, Credit & Banking: papers featured per quarter

    Credit risk, default prediction, banking, systemic risk and risk measures.

    • Attention-based Dynamic Multilayer Graph Neural Networks for Loan Default Prediction
    • Moderating effects of gender and family responsibilities on the relations between work–family policies and job performance

    430 papers

  7. Asset Pricing & Factors

    Asset Pricing & Factors: papers featured per quarter

    Factor models, anomalies, the cross-section of returns and what survives publication.

    • Bubble economics
    • NUMOSIM: A Synthetic Mobility Dataset with Anomaly Detection Benchmarks

    329 papers

  8. Macro-Finance & Rates

    Macro-Finance & Rates: papers featured per quarter

    Rates, the yield curve, monetary policy, inflation and macro-finance.

    • The disruption index is biased by citation inflation
    • Inflation—Who Cares? Monetary Policy in Times of Low Attention

    326 papers

  9. Econometrics & Forecasting

    Econometrics & Forecasting: papers featured per quarter

    Forecasting, time series, econometrics and nowcasting.

    • TKAN: Temporal Kolmogorov-Arnold Networks
    • Deep learning models for price forecasting of financial time series: A review of recent advancements: 2020–2022

    365 papers

  10. ML & AI Methods

    ML & AI Methods: papers featured per quarter

    Machine-learning methods applied to finance: deep learning, boosting, RL and new architectures.

    • Mamba: Linear-Time Sequence Modeling with Selective State Spaces
    • Octo: An Open-Source Generalist Robot Policy

    1,193 papers

  11. Corporate Finance

    Corporate Finance: papers featured per quarter

    Firms, governance, IPOs, M&A and corporate decisions.

    • ESG Reputation Risk Matters: An Event Study Based on Social Media Data
    • Articulate AnyMesh: Open-Vocabulary 3D Articulated Objects Modeling

    170 papers

Recent issues

139 issues since May 2023.

Week 2

No. 139 · November 2026, Week 2

This week: generalization and robustness in execution and hedging; and systematic evidence failures in published quant research. Standouts: Microstructure Invariance For Execution Policies shows trained policies transfer across assets and venues. RL Hedging for Options cuts tail losses versus delta. Evidence Audit of…

  1. Microstructure Invariance For Execution Policies
  2. Evidence Audit of 91 LLM Trading Papers
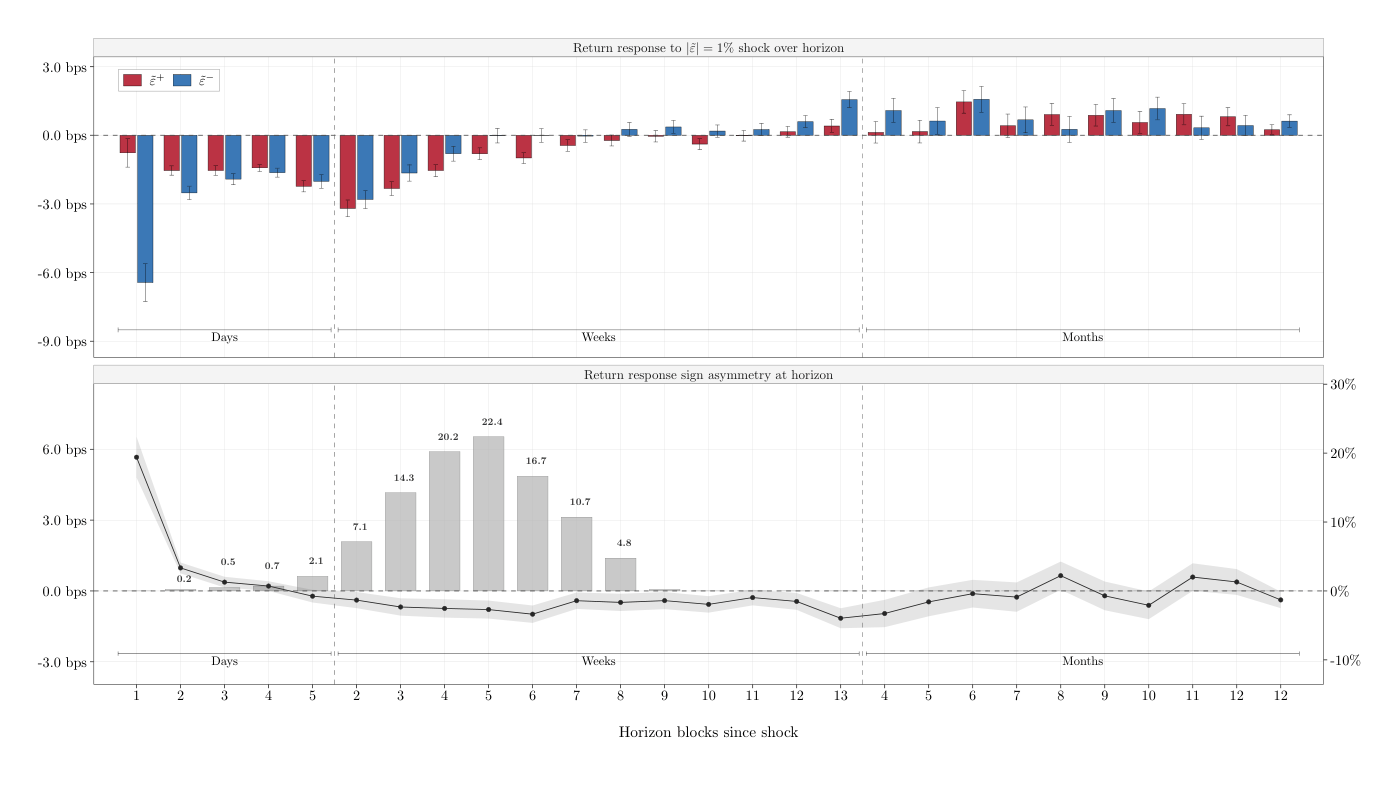
  3. Asymmetric Idiosyncratic Return Reversal

90 papers · arXiv 30 · SSRN 30 · RePEc 30
Week 1

No. 138 · November 2026, Week 1

This week spotlights credibility gaps in quantitative finance: LLMs lose predictive power in live trading despite strong backtests, knowledge cutoffs and future-look bias inflate strategy alphas, and reproducibility remains fragile. Standouts: LLM Stock-News Signals Under Scrutiny, LLM Knowledge Cutoffs and Backtests,…

  1. LLM Stock-News Signals Under Scrutiny
  2. The Hidden Sharpe Ratio
  3. Newspaper Reasons Explain Returns

90 papers · arXiv 30 · SSRN 30 · RePEc 30

Week 5

No. 137 · October 2026, Week 5

This week centers on AI agent fragility in financial markets, real-time benchmark design preventing memorization, and cryptographic signals predicting equities. AI Equity Research Without Future Data reveals forecast accuracy well below overall performance; Fragility Of Synchronized Agentic Wealth Management quantifie…

  1. AI Equity Research Without Future Data
  2. AI Monoculture Paradox in Markets
  3. 150 Years of US Inflation Expectations

90 papers · arXiv 30 · SSRN 30 · RePEc 30
Week 4

No. 136 · October 2026, Week 4

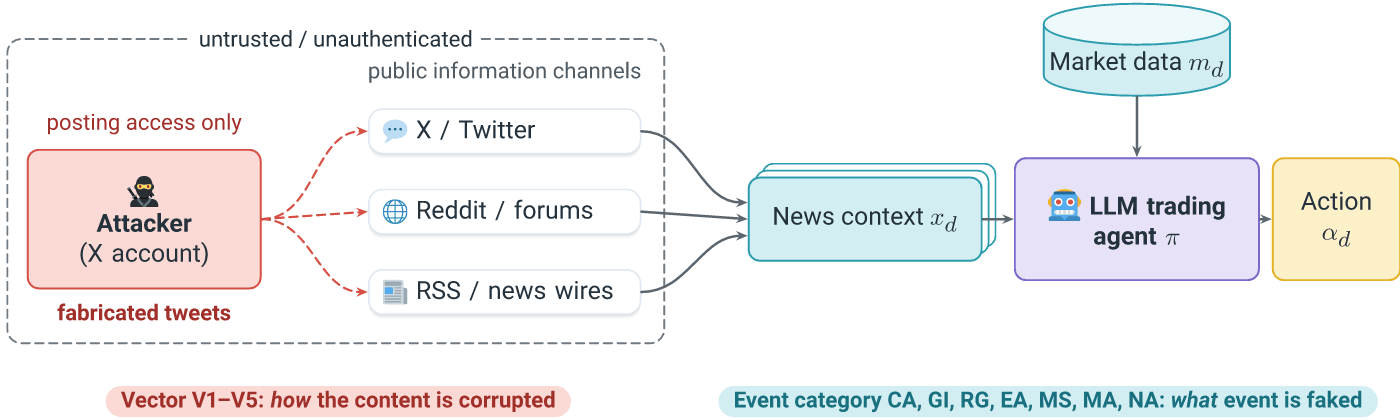
This week spans AI risk in trading, neural microstructure learning, and the frontier's limits. Key tensions emerge: LLM traders fall to information attacks while benchmarks show no leading model beats equal-weight; neural filters cut arbitrage uncertainty eightfold yet ML VaR models hide regime-shift failures. Mean-fi…

  1. Information Injection Attacks on LLM Traders
  2. ML Value-at-Risk Validation Under Regime Shifts
  3. AI Productivity Gains Boost GDP Growth

90 papers · arXiv 30 · SSRN 30 · RePEc 30
Week 3

No. 135 · October 2026, Week 3

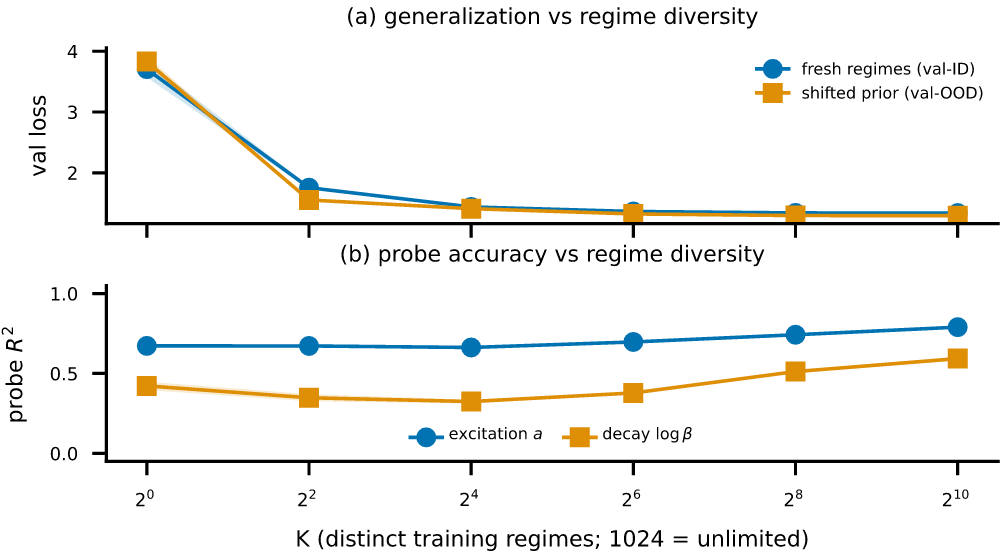
This week pivots toward machine learning in discovery and execution. Foundation models learn market regimes from order flow; genetic programming and RL agents discover alpha factors across assets and frequencies. But a survey of 47 LLM trading systems finds reported margins vanish on retest, and a massive pre-register…

  1. Foundation Models Learn Market Regimes
  2. LLM-Based Trading Systems Survey
  3. Large Language Models in Economics Research

90 papers · arXiv 30 · SSRN 30 · RePEc 30
Week 2

No. 134 · October 2026, Week 2

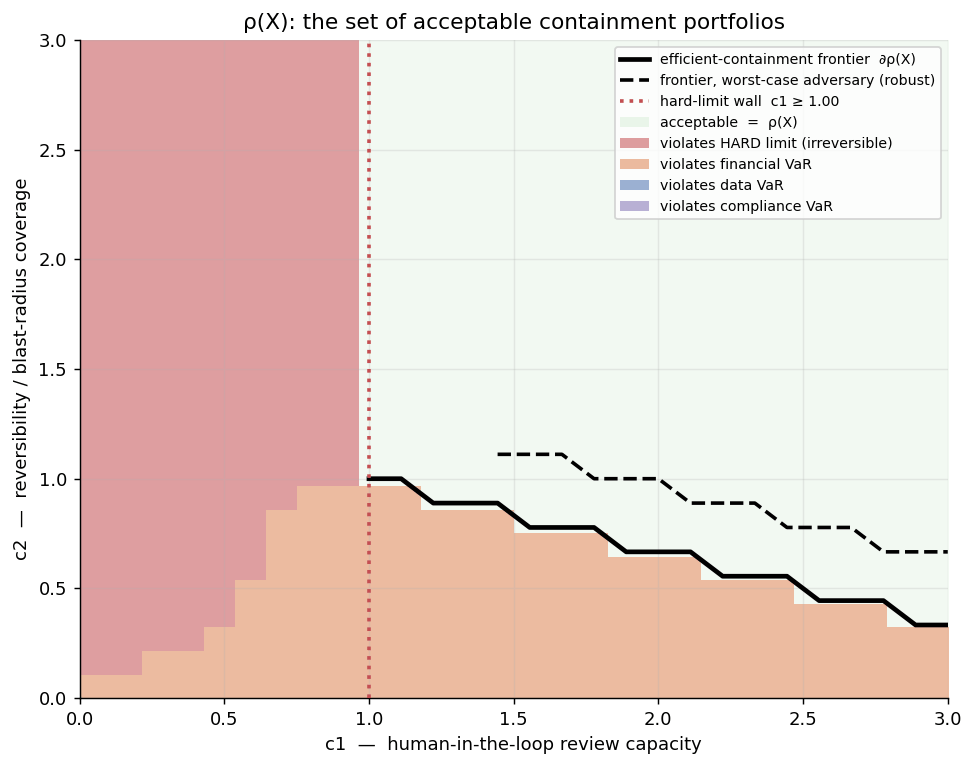
This week centers on AI systemic risk, factor discovery limits, and monetary transmission channels. Agentic AI systems create non-diversifiable contagion floors despite fleet size; automated factor mining shows no paradigm dominates; and Fed policy transmits primarily through risk appetite shifts rather than rates. Se…

  1. Agentic AI and Systemic Financial Risk
  2. Quantitative Equity Evolution: Constraints and Alpha Decay
  3. Risk Appetite and Monetary Transmission

90 papers · arXiv 30 · SSRN 30 · RePEc 30

Open to agents

Point your assistant at ML-Quant: it reads the same pages you do.

  1. llms.txt

    One file that tells an assistant what is here and where.

    https://www.ml-quant.com/llms.txt
  2. Every page as Markdown

    Add index.md to any URL, or press Copy for AI.

    https://www.ml-quant.com/topics/llms-text/index.md
  3. JSON API

    Issues, papers, topics, the radar and the track record. No key.

    https://www.ml-quant.com/api/v1/index.json
  4. Feeds

    RSS for the letter and for every topic.

    https://www.ml-quant.com/feed.xml

Every Friday, free

Join 11,000+ quants who read the letter.

The week's best arXiv, SSRN and RePEc papers, each in one sentence, with its key figure. Plus what quant developers are starring on GitHub and which of our past picks just got published.

Delivered by Substack. Subscribe on Substack · Past posts · RSS

    Type to search. Try rough volatility, LLM agents or FinGPT.

    ↑↓ move↵ openesc closeFull search page