arXivML & AI Methods
RICE-Alpha: Reliability-Informed Correction with Event Graphs for LLM-Agent Stock Forecasting
RICE-Alpha uses event graphs and historical reliability to improve LLM-based stock forecasting, achieving stronger results on Nasdaq-100 and Hang Seng panels than competing LLM agents.
Featured in No. 135 on 16 Oct 2026 · on release day
- Released
- 16 Oct 2026
- First featured
- No. 135 · 16 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- arXiv:2609.34004
- Authors
- Tong Liu et al.
Abstract
From arXiv (CC0).
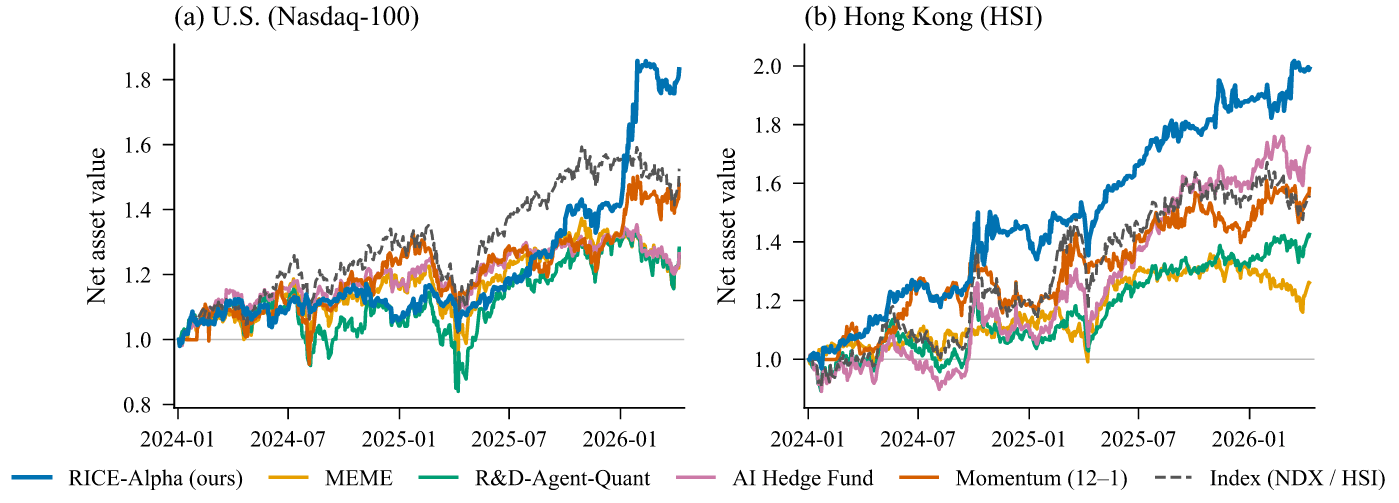
Equity-relevant news evolves through temporally dependent corporate events, making historical information useful only when event continuity, information availability, and transition reliability are modeled. Existing LLM-based financial agents incorporate historical evidence, yet they provide limited support for preserving issuer-specific chronology under point-in-time constraints and for identifying when historical transitions contribute information beyond the current forecast. We present RICE-Alpha (Reliability-Informed Correction with Event Graphs), a point-in-time stock-scoring framework that separates a history-aware multi-view Base Alpha from a reliability-calibrated residual correction derived from historical event continuation. A Multi-Tier Memory Layer grounds news interpretation in temporally eligible issuer-specific history, while a Typed Event Agent constructs event states whose successor relations are formed within issuers and pooled across firms only after valid local pairing. Matured transitions are calibrated by their empirical reliability, and the resulting graph signal is residualized against the Base Alpha and technical view to obtain the RICE Delta. On daily Nasdaq-100 and Hang Seng Index panels from 2024 to 2026, RICE-Alpha achieves the strongest results among the evaluated LLM-based agents and momentum across four predictive and four portfolio-level metrics. Its ICIR more than doubles that of the strongest baseline, while net Sharpe ratios reach 1.656 and 1.725 in the U.S. and Hong Kong, respectively. U.S. ablations further show significant reductions in IC and RankIC after Holm adjustment when major components are removed. These results indicate that historical event continuation adds incremental information when it is temporally grounded, reliability-calibrated, and introduced as a residual correction to a multi-view forecast.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).