arXivML & AI Methods
LiveOption: Evaluating LLM Agents in Structured Option Trading with Nonlinear Payoffs
An evaluation framework tests language model agents on structured option trading tasks, finding current systems underperform in most real-world scenarios.
Featured in No. 133 on 2 Oct 2026 · 3 days after release
- Released
- 29 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- arXiv:2609.33470
- Authors
- Haochen Luo et al.
Abstract
From arXiv (CC0).
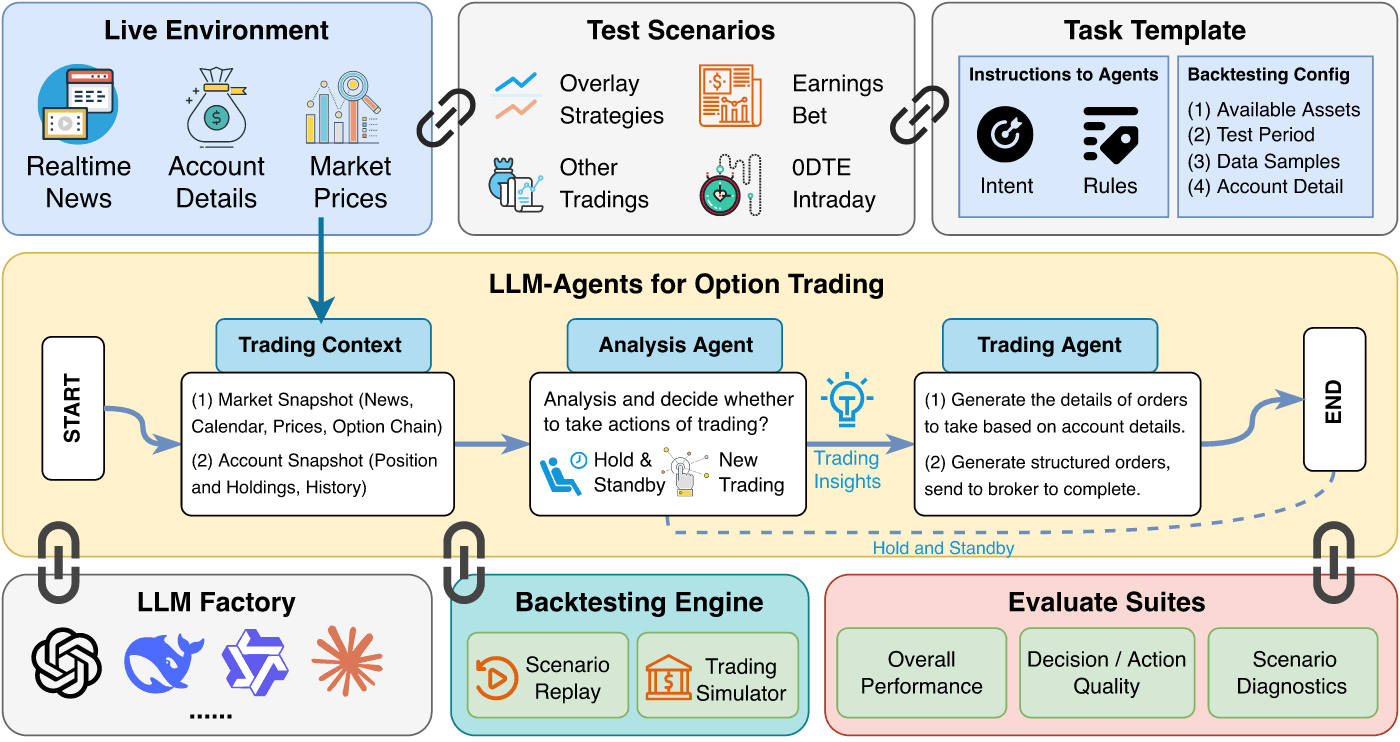
Large language models (LLMs) and multi-agent systems (MAS) have shown promise in financial decision-making, yet existing evaluations focus on equity trading and primarily assess directional prediction, overlooking the structural complexity of derivative markets. Option trading introduces fundamentally different challenges, including nonlinear payoffs and multi-leg strategy construction, requiring structured decisions rather than simple directional bets. We introduce LiveOption, an evaluation framework for LLM-based agents in option trading. LiveOption formulates the problem as structured sequential decision-making under realistic execution and capital constraints, and provides a reproducible environment with standardized interaction protocols. The framework includes three task suites covering portfolio overlays, event-driven earnings trading, and 0DTE intraday trading. We further propose a hierarchical metric suite that evaluates action validity, decision quality, risk characteristics, and outcome-level performance. Experiments show that current agents often fail to achieve competitive returns in most scenarios. LiveOption offers a principled testbed for evaluating structured decision-making beyond outcome-based metrics.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).