RePEcEconometrics & Forecasting
Zero-Shot Conditional Forecasting and the Information Content of Central Bank Paths
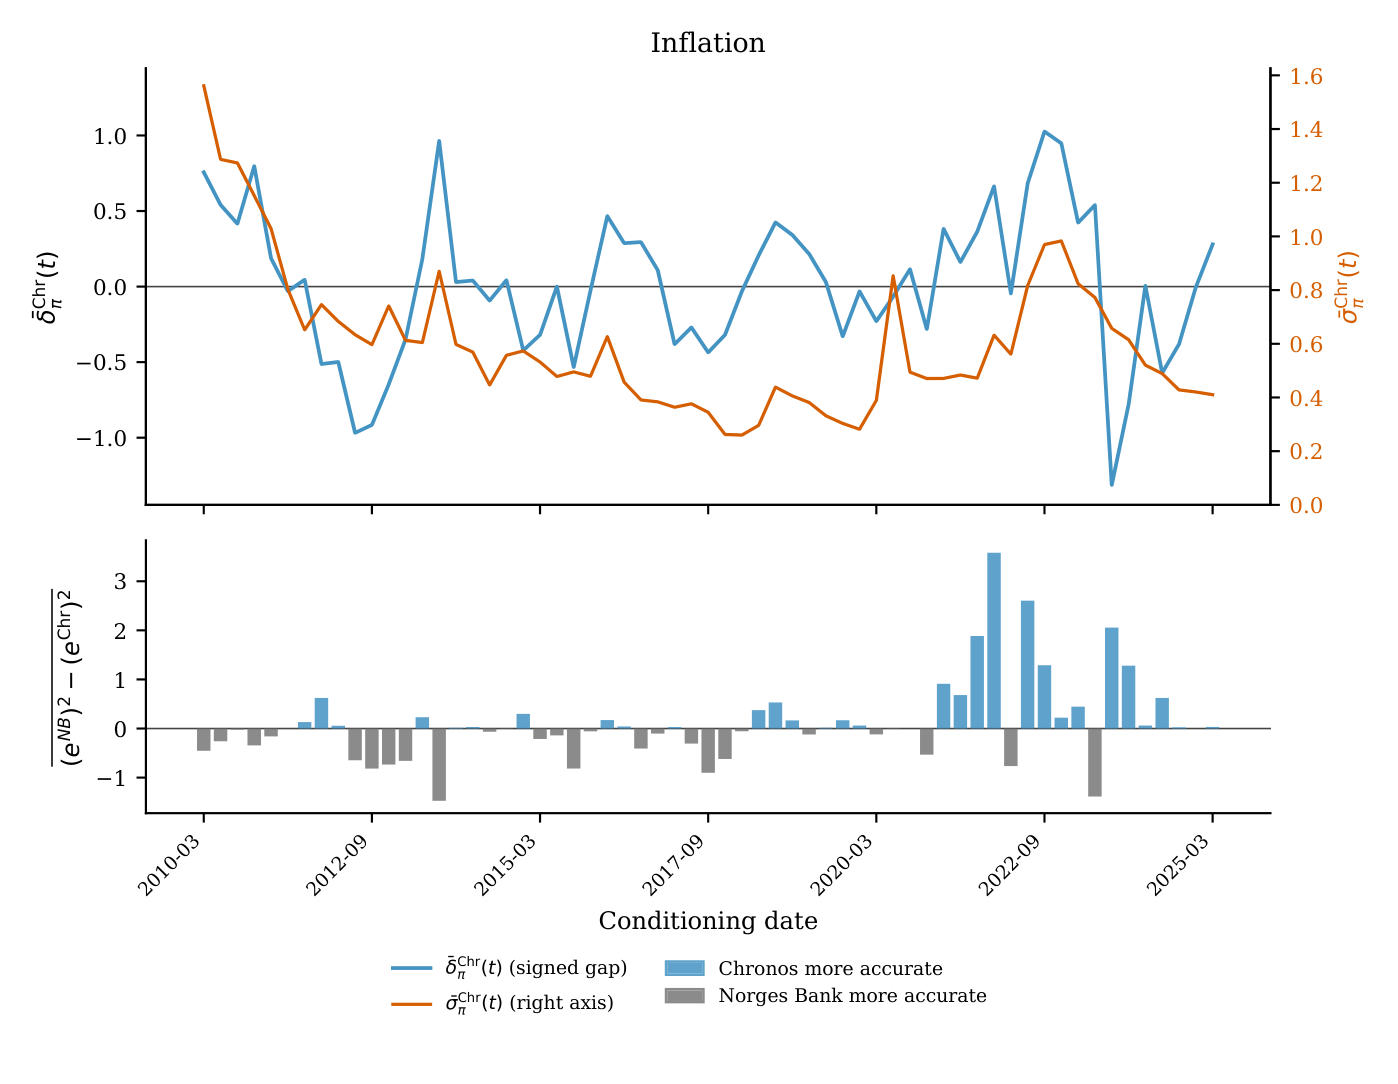
A pre-trained time-series model reading central bank published paths cuts forecast errors better than the banks themselves and hard-conditioned VARs, revealing exploitable institutional differences.
Featured in No. 133 on 2 Oct 2026 · 11 days after release
- Released
- 21 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:ces:ceswps:_12972
- Authors
- Vegard H. Larsen and Leif Anders Thorsrud
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).