RePEcEconometrics & Forecasting
What makes Monetary Policy More Powerful? A Big Data Approach
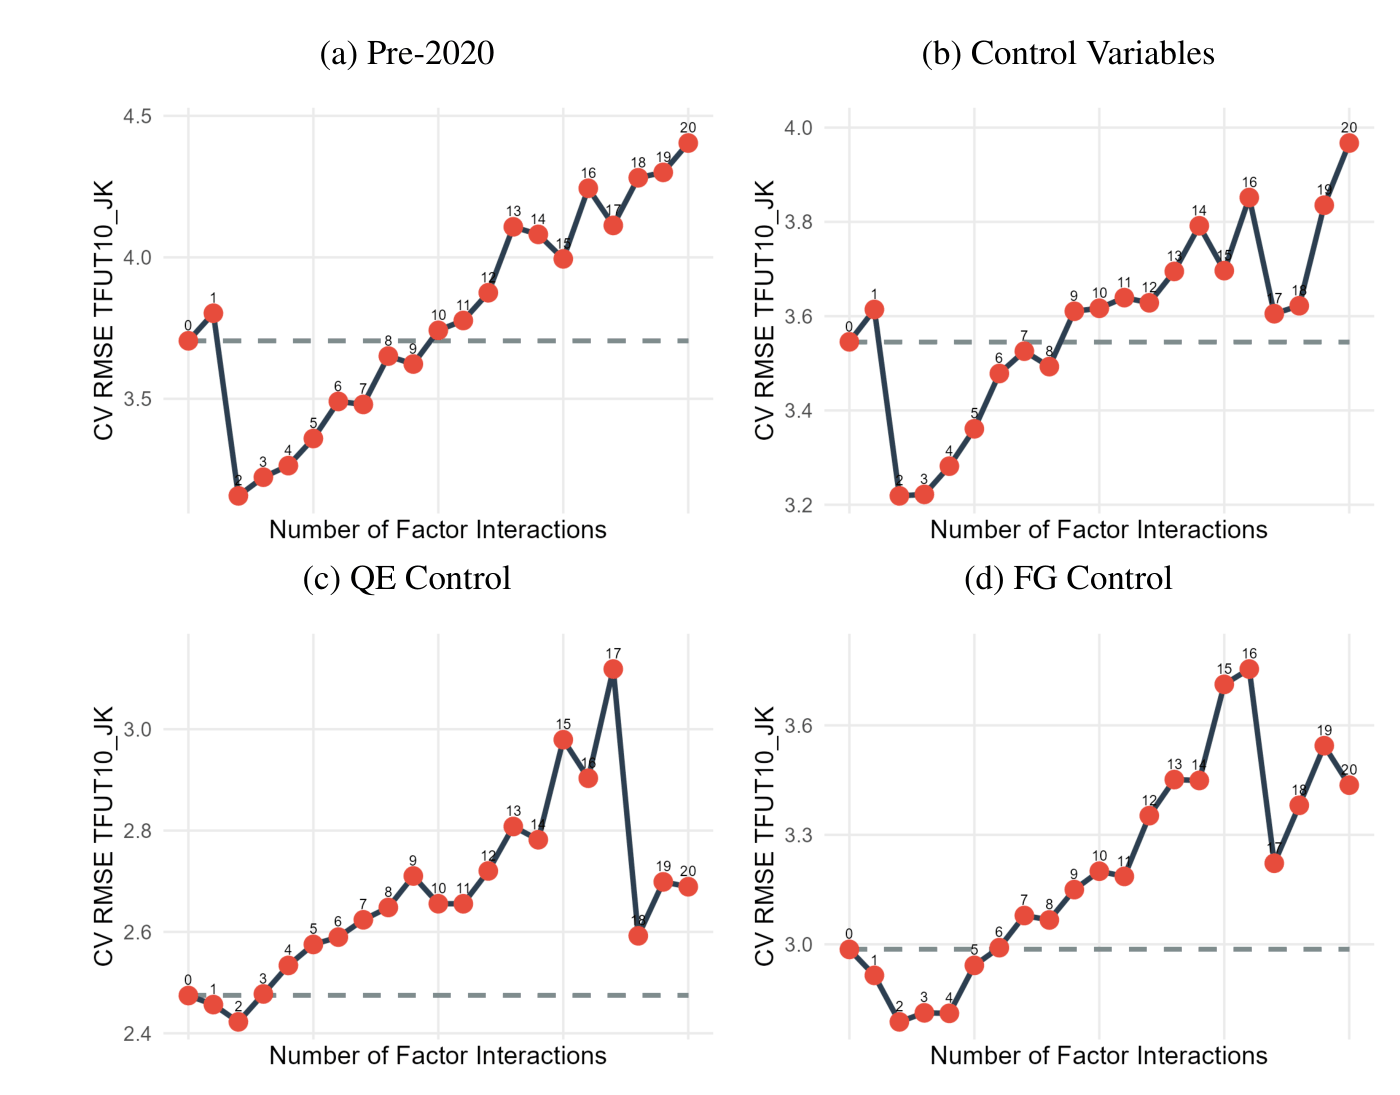
Analysis of a large macro-financial dataset ranks non-linear monetary transmission channels, finding transmission to long-term rates weakens at high interest rates and high credit growth, with sovereign risk mattering in the euro area.
Featured in No. 133 on 2 Oct 2026 · 11 days after release
- Released
- 21 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:cbi:wpaper:09/rt/26
- Authors
- Dilan Aydin Yakut et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).