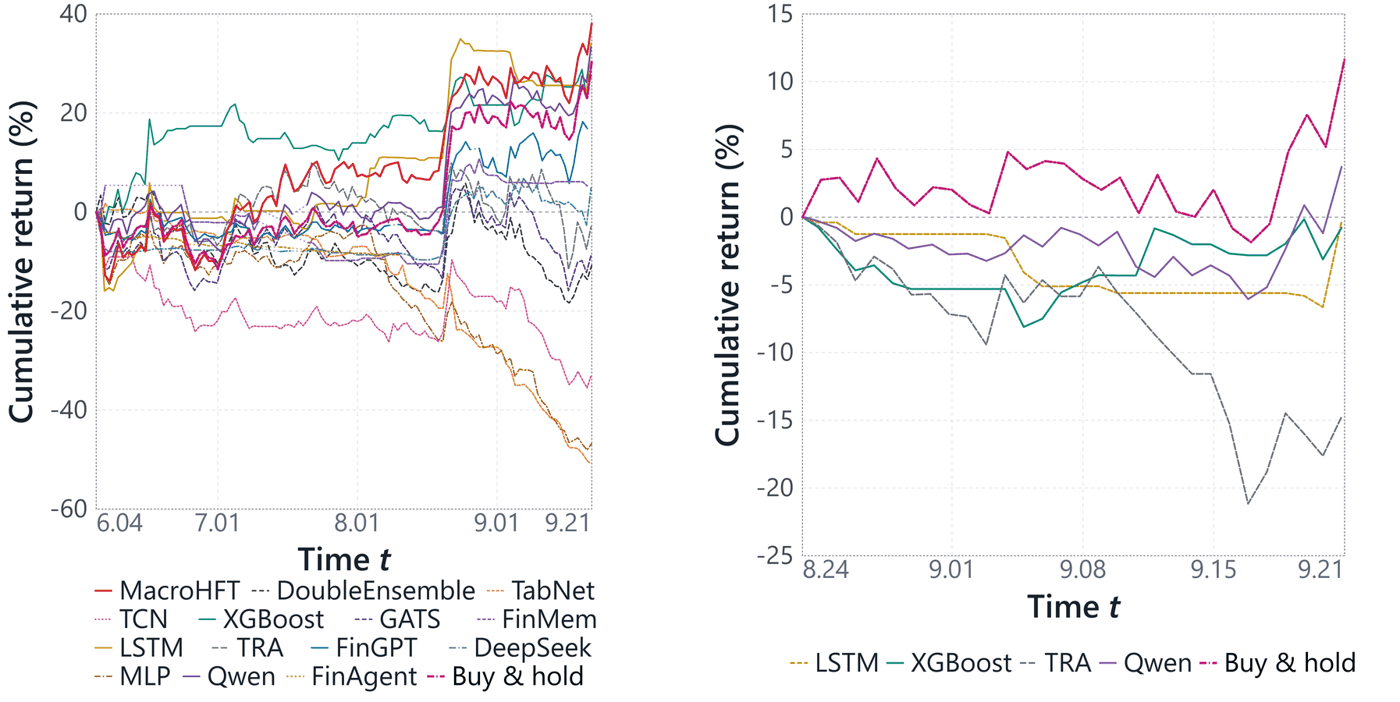
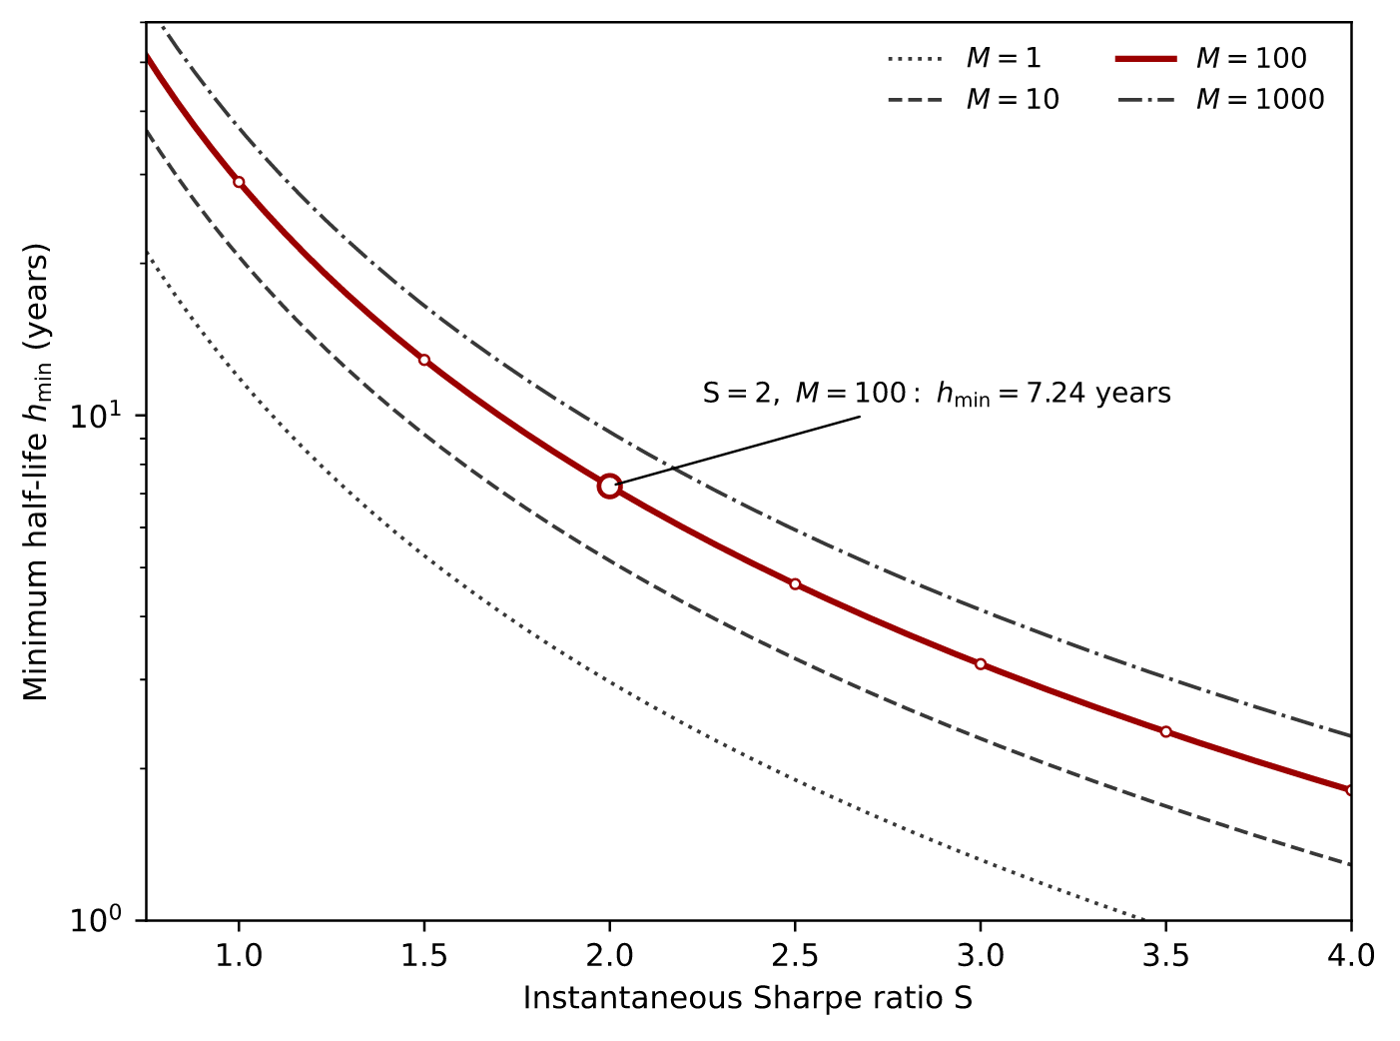
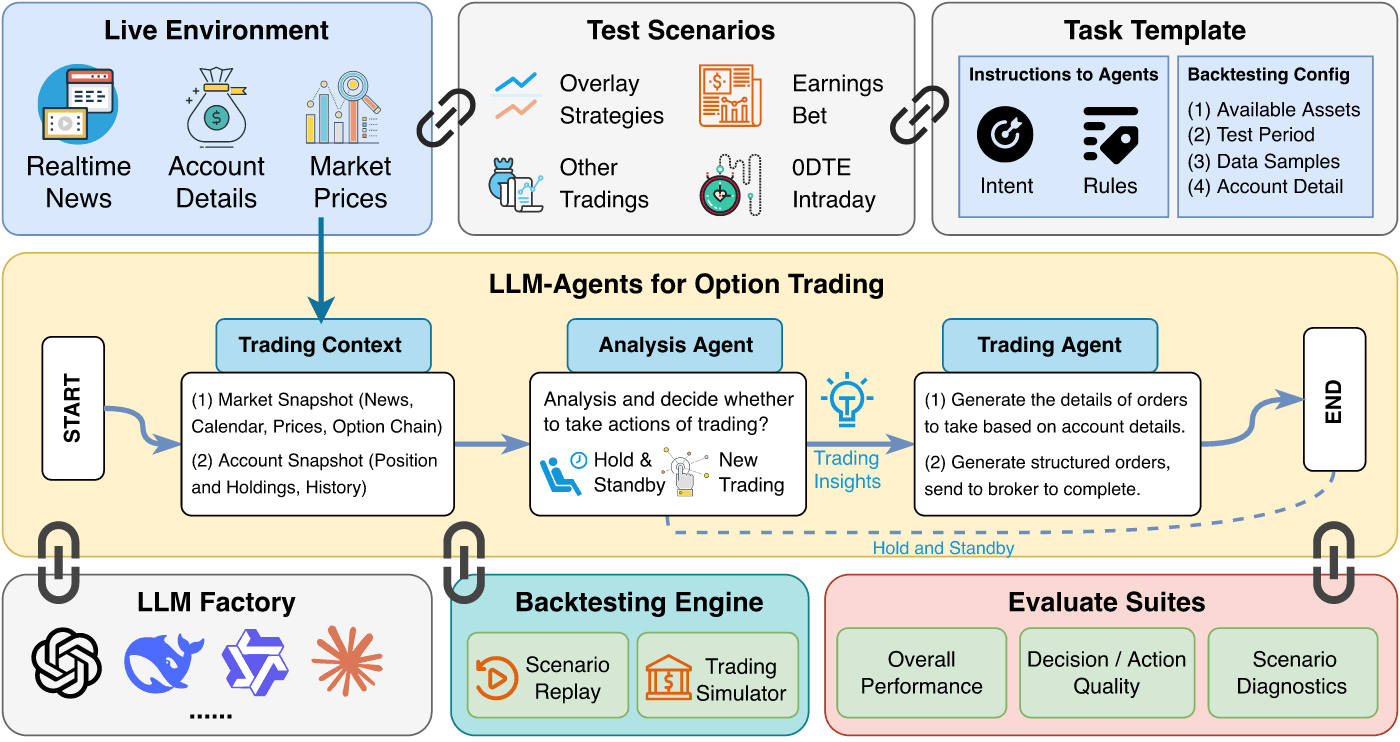
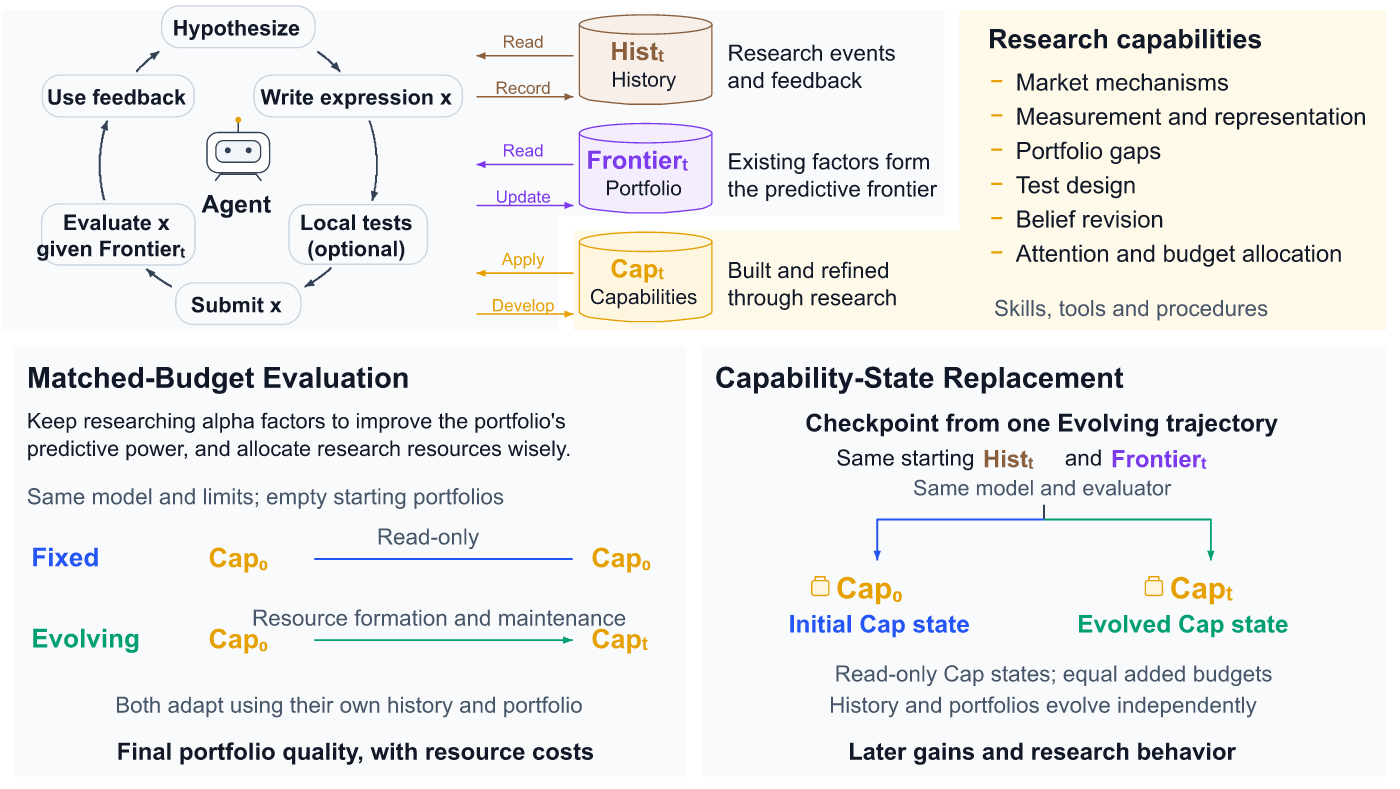
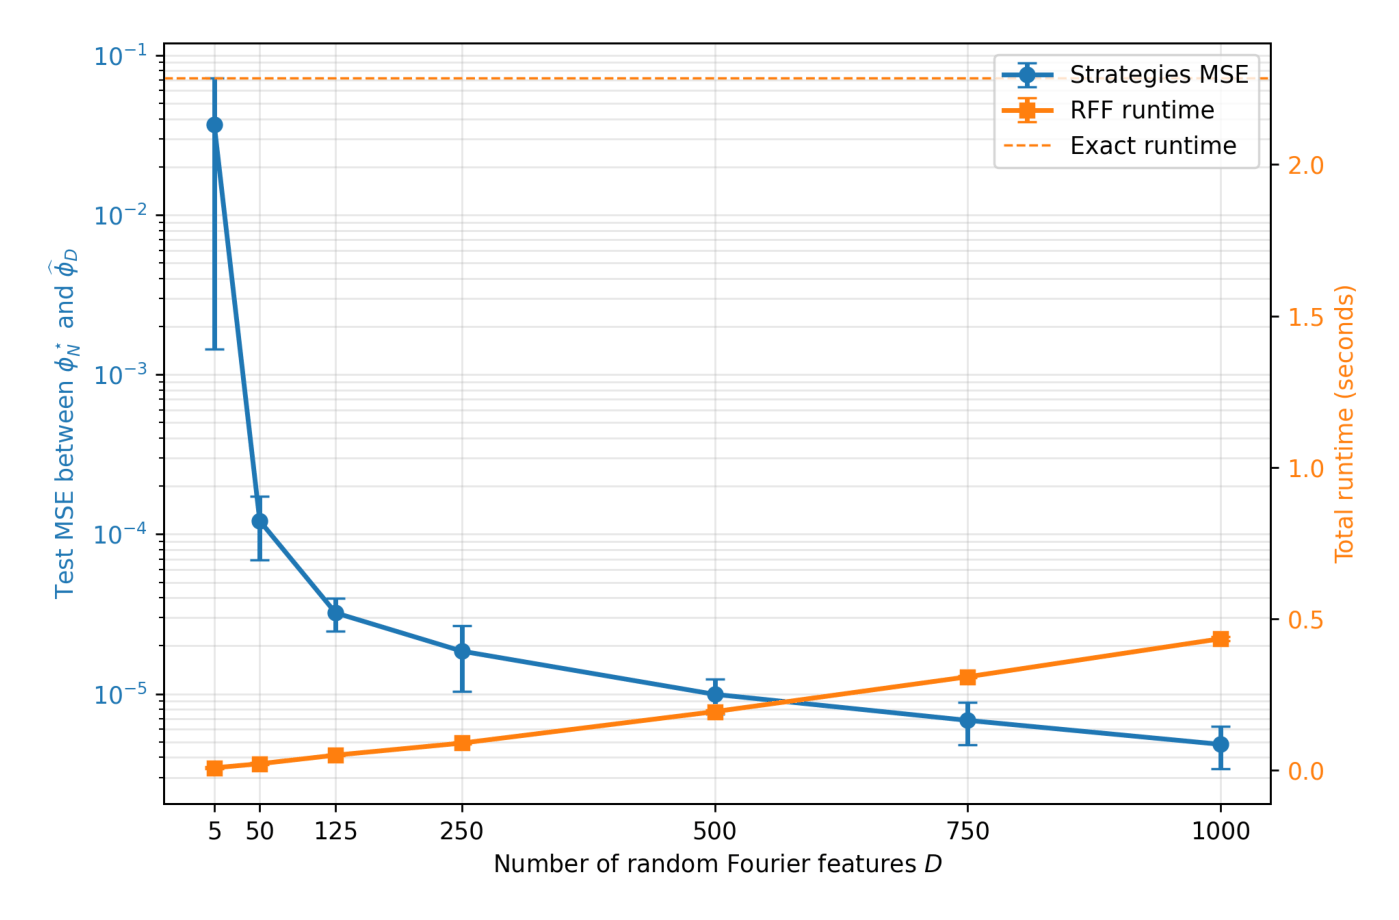
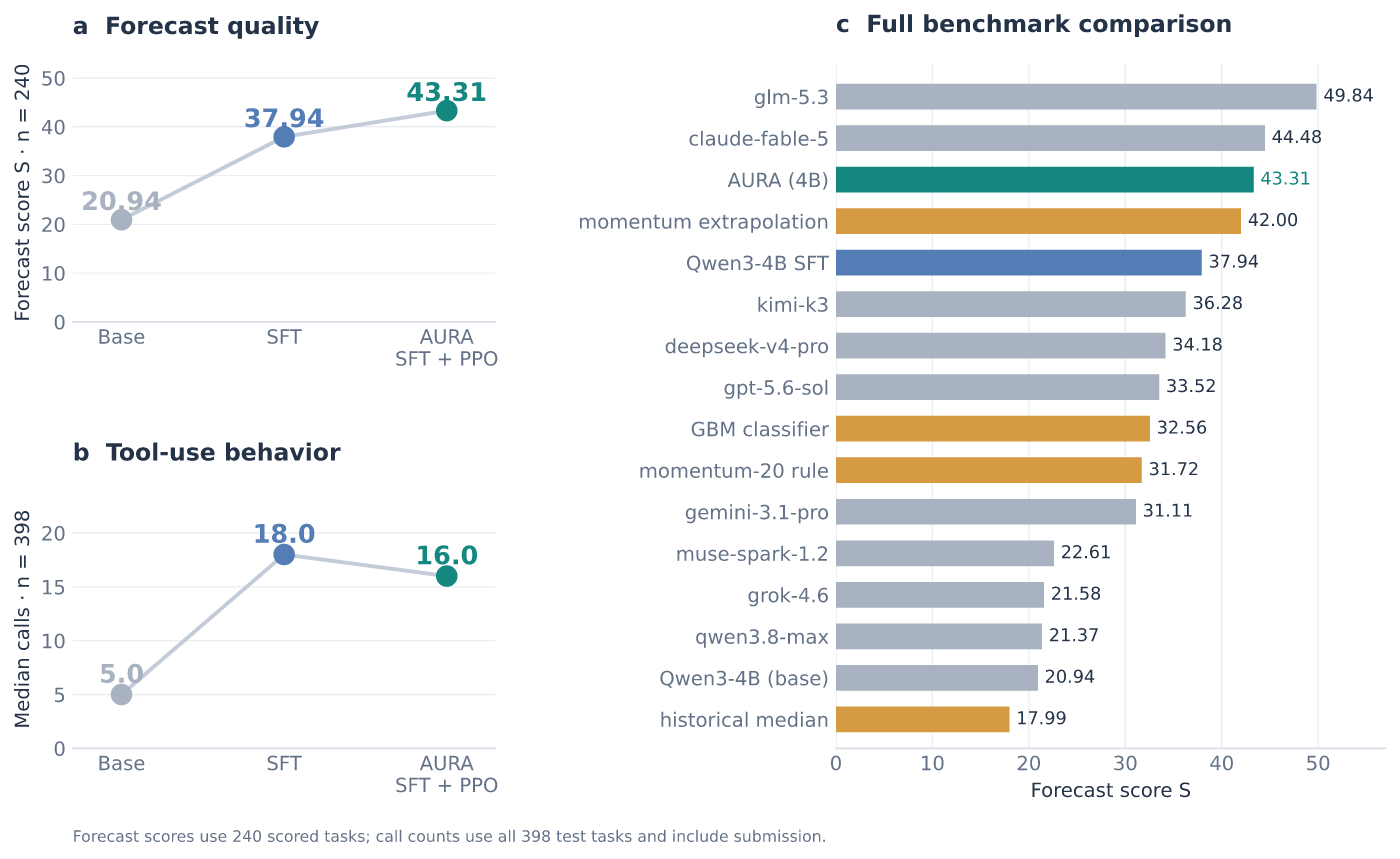
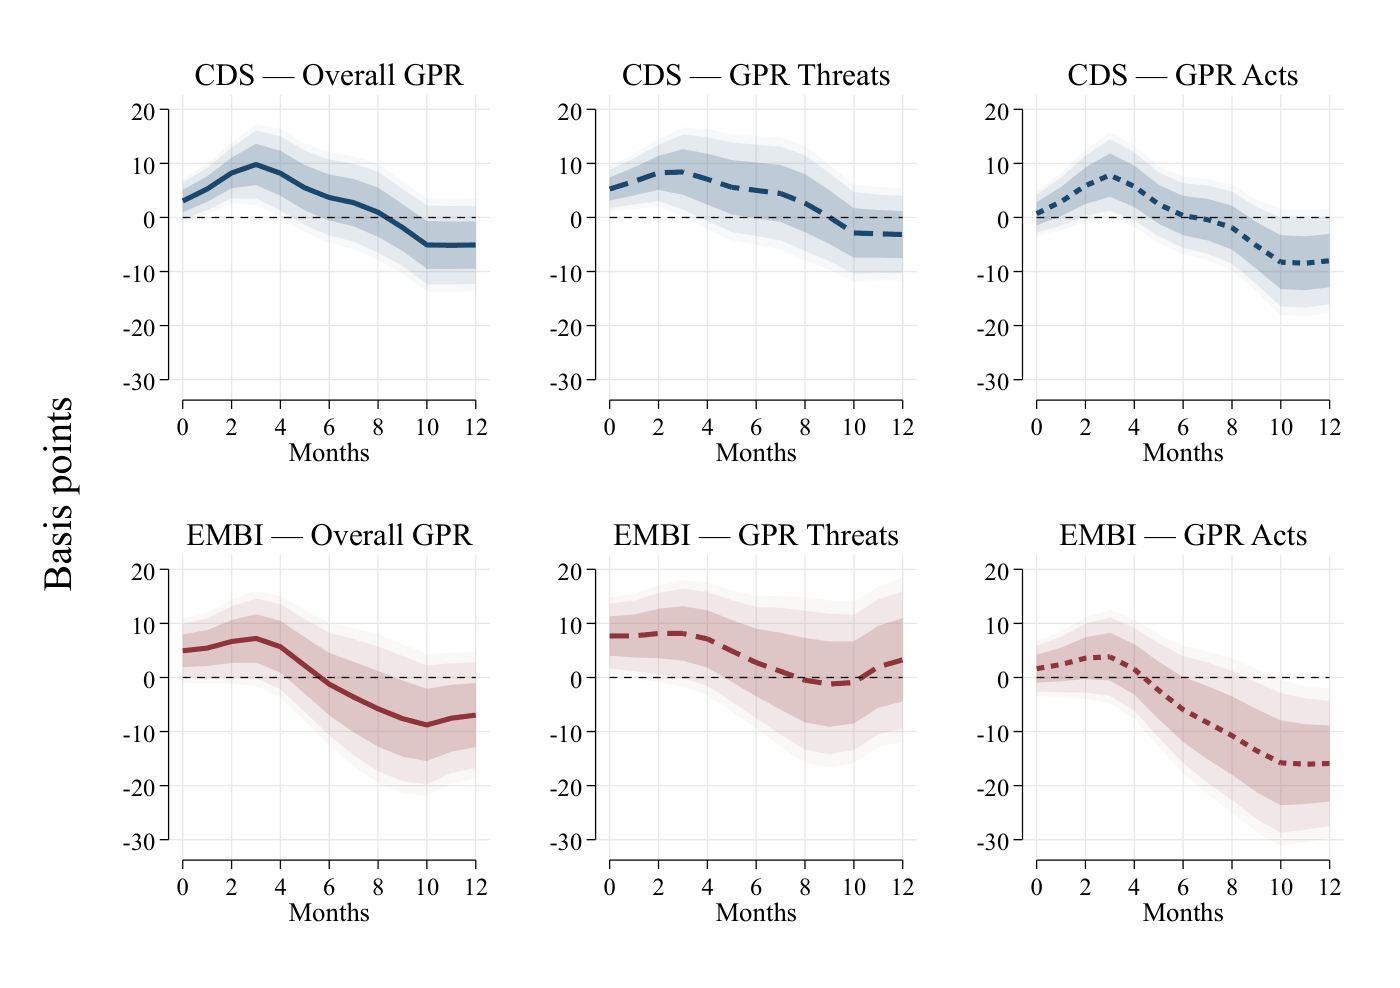
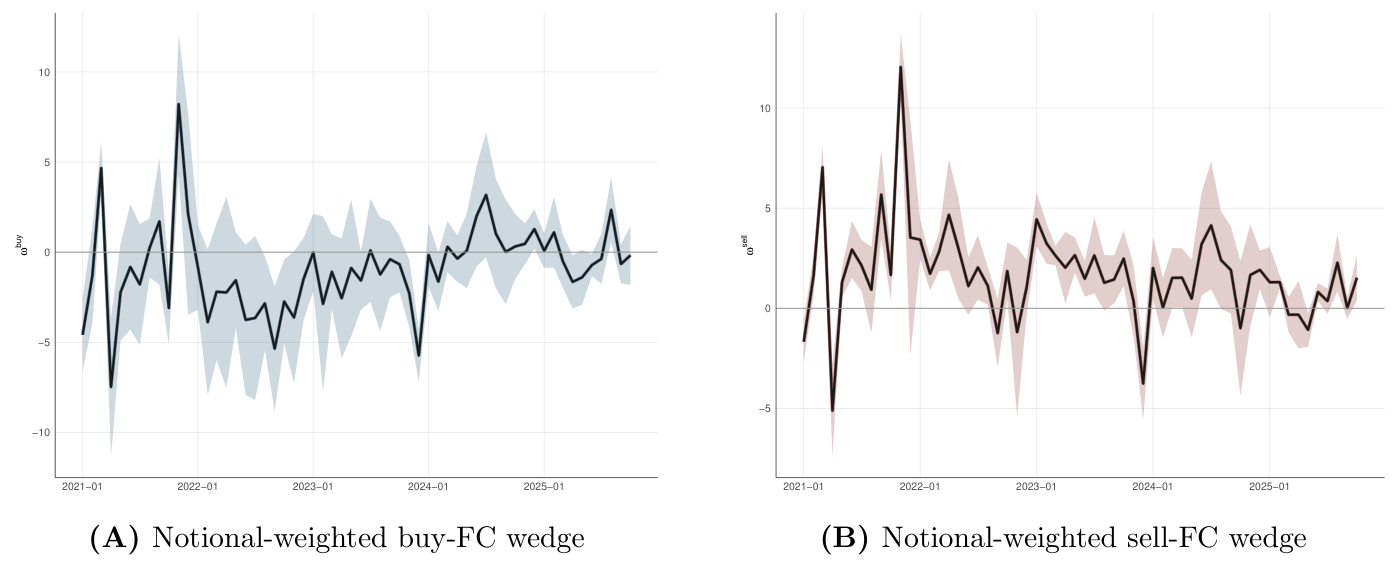
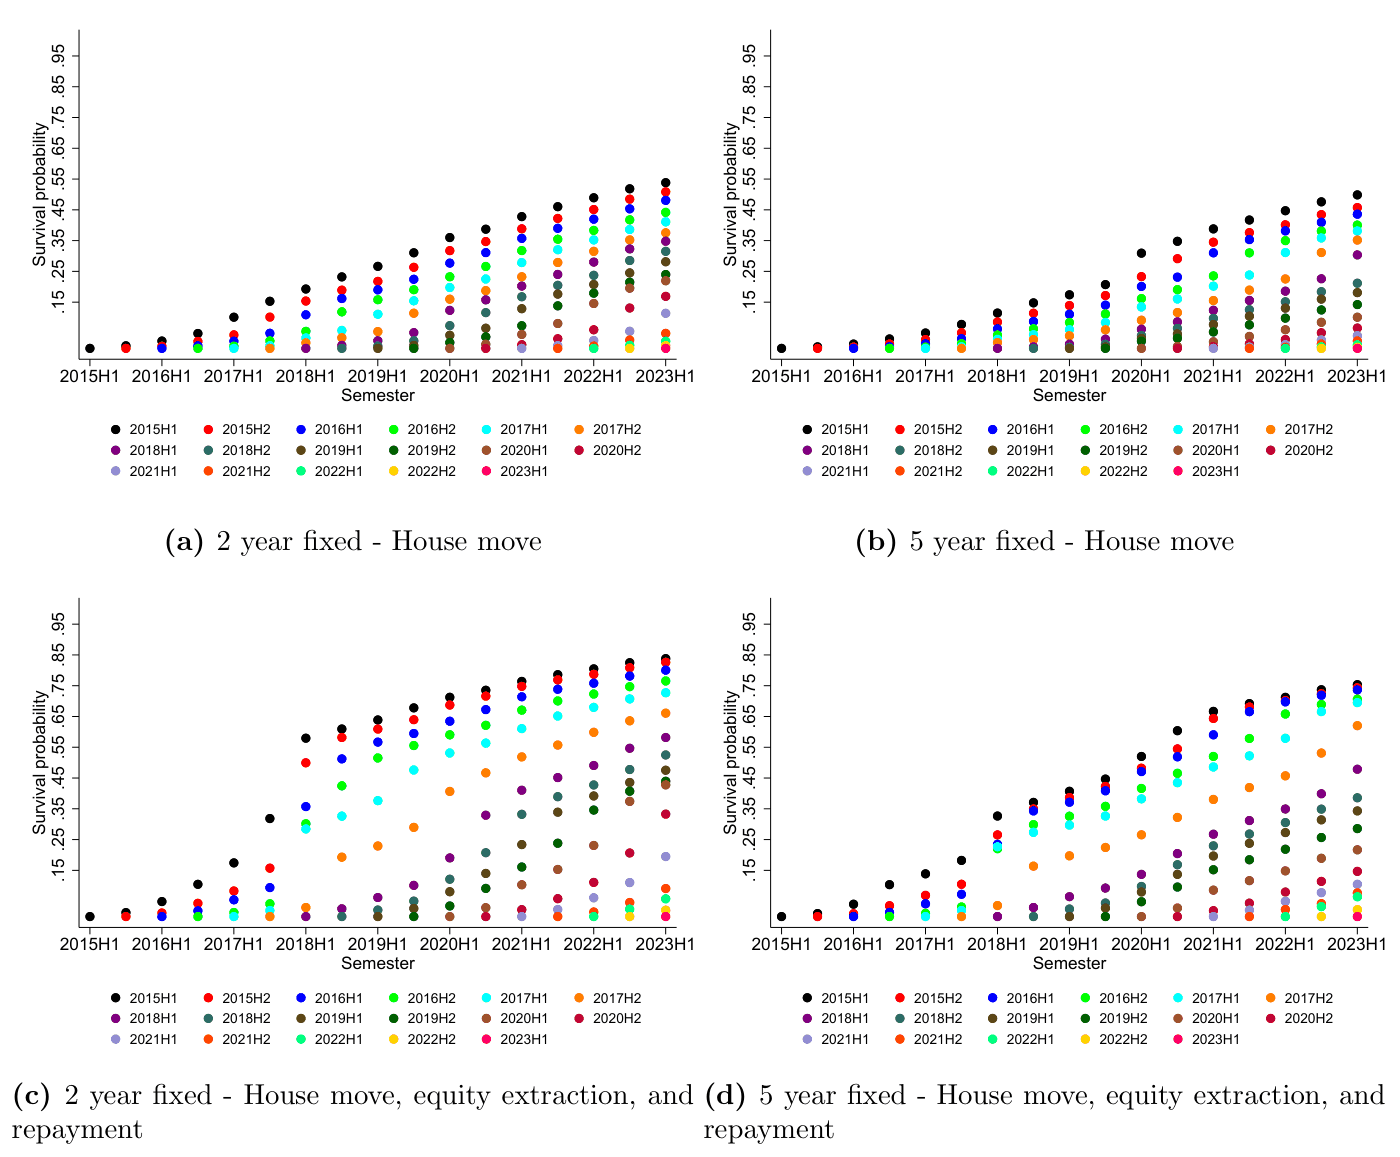
This week centers on AI's expanding role in trading and markets, alongside persistent microstructure patterns and monetary policy transmission. Key papers: "AI Trading Methods: Backtests Versus Real Markets" measures the live-market gap for machine learning and LLM strategies; "Certified Alpha Capacity and Decay" derives exact deployment thresholds before signal decay; "AlphaPareto" applies reinforcement learning to multi-objective alpha discovery. Corporate bond signals predict equity returns; FOMC surprises persist; US rate shocks widen global spreads.