Beyond Point Forecasts: Tail Information and Equity Portfolio Formation
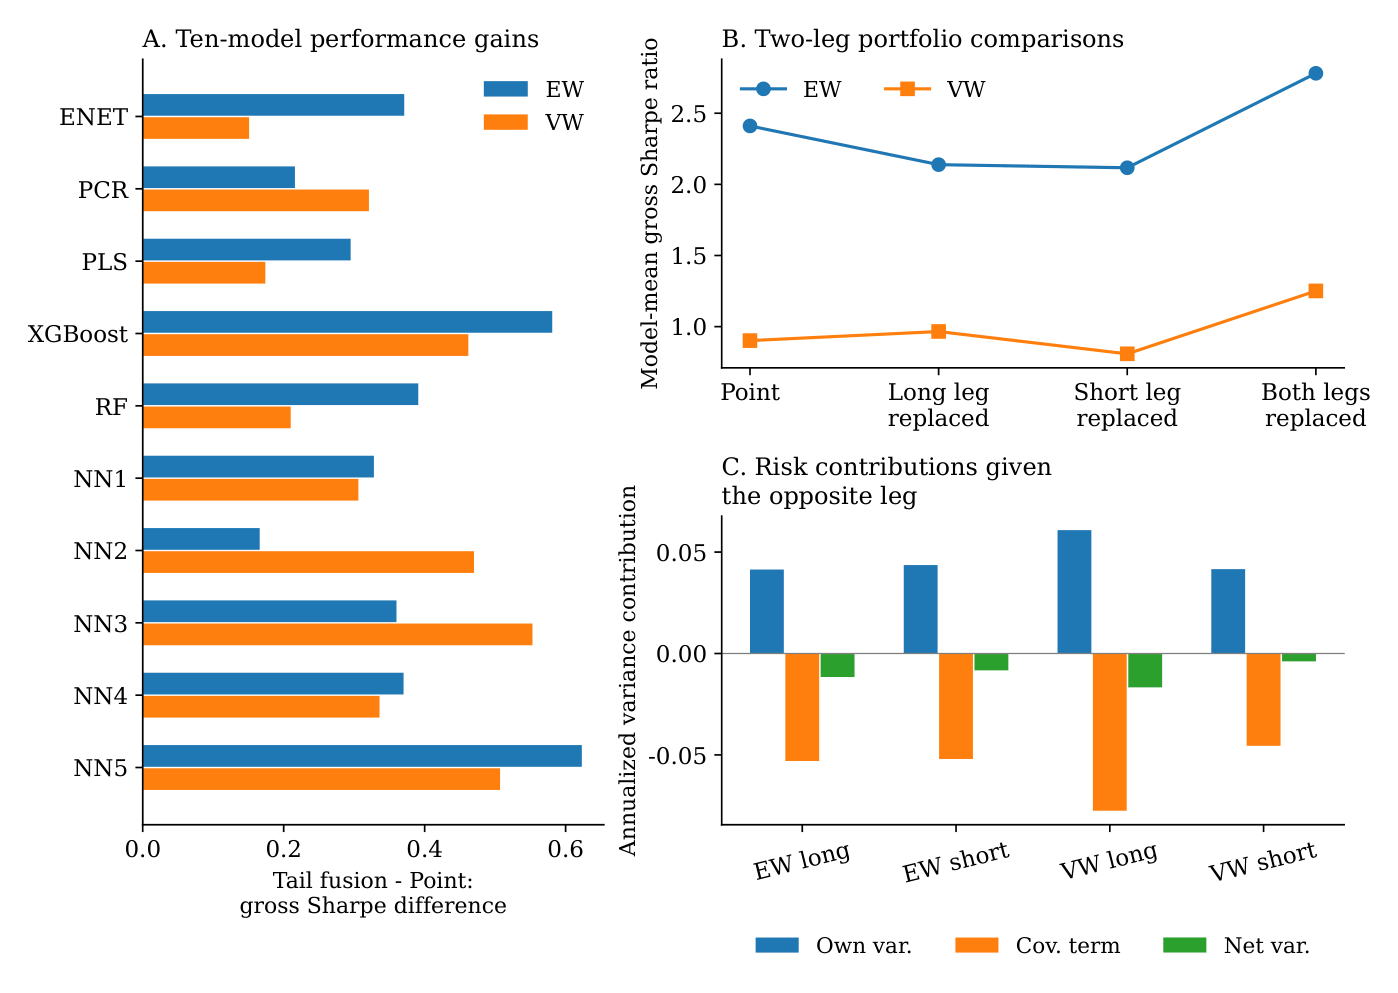
Incorporating upper and lower tail information from machine learning models increases Sharpe ratios for long-short equity portfolios across ten prediction models from 1992 to 2024.
Featured in No. 139 on 13 Nov 2026 · 2 days after release
- Released
- 11 Nov 2026
- First featured
- No. 139 · 13 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- SSRN 7685651
- Authors
- Yifei Wang
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).