SSRNTrading, Microstructure & Execution
Buy the Rumor, Sell the News: When is News Priced in?
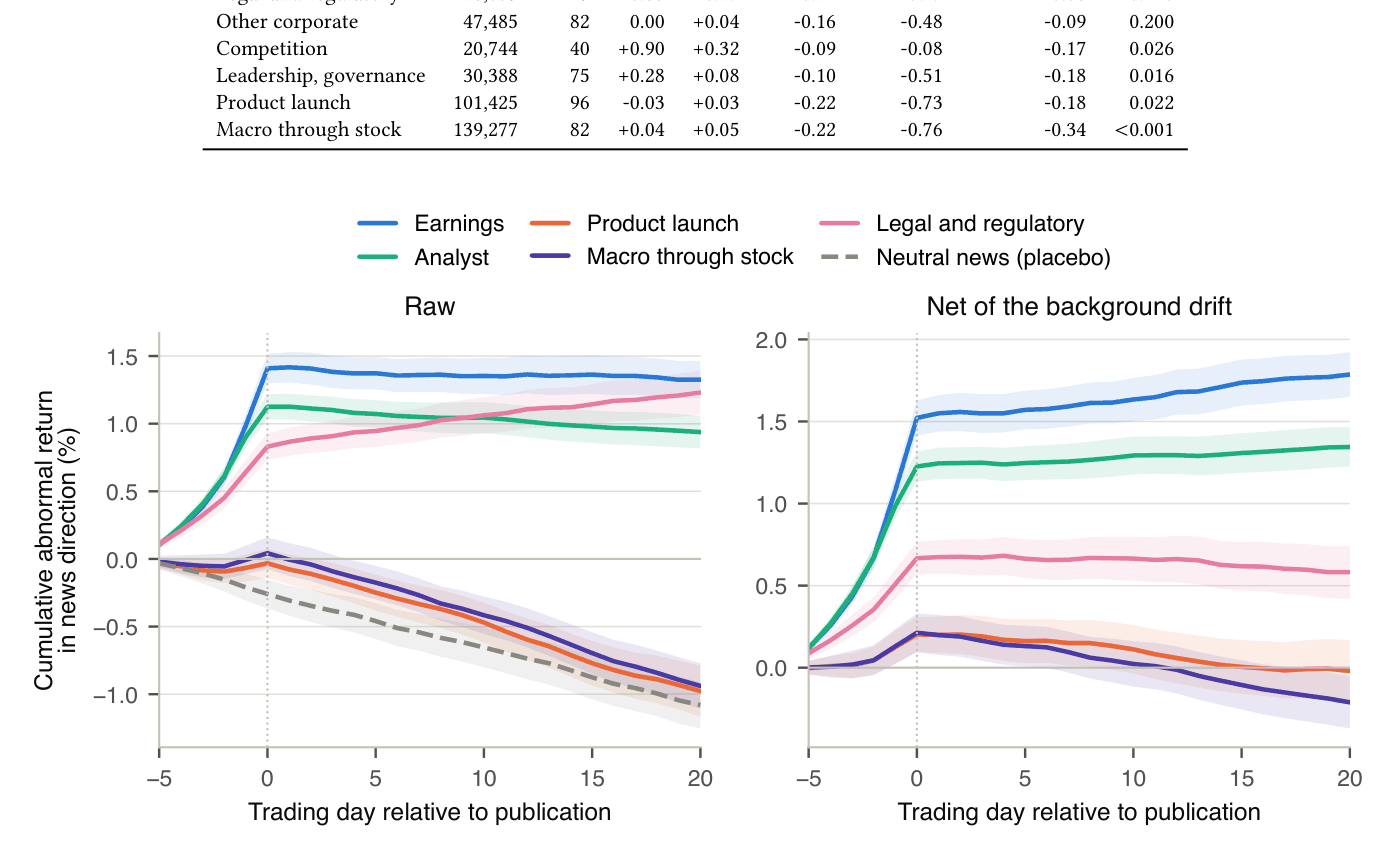
Analyzing 1.68 million stock-day events from 4.57 million articles, the study finds that directional price moves concentrate before and at publication day, with little incremental return later.
Featured in No. 138 on 6 Nov 2026 · 2 days after release
- Released
- 4 Nov 2026
- First featured
- No. 138 · 6 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- SSRN 7673798
- Authors
- Alireza Kargarzadeh et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).