arXivTrading, Microstructure & Execution
SwingGuard: Risk-Conditioned Multi-Agent Swing Trading with Dual-Timescale Governance
A dual-timescale multi-agent framework generates trading strategies conditioned on current risk and maintains ongoing position governance between strategy revisions on cryptocurrency, preserving returns after transaction costs.
Featured in No. 135 on 16 Oct 2026 · 4 days after release
- Released
- 12 Oct 2026
- First featured
- No. 135 · 16 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2610.12988
- Authors
- Junzhou Su et al.
Abstract
From arXiv (CC0).
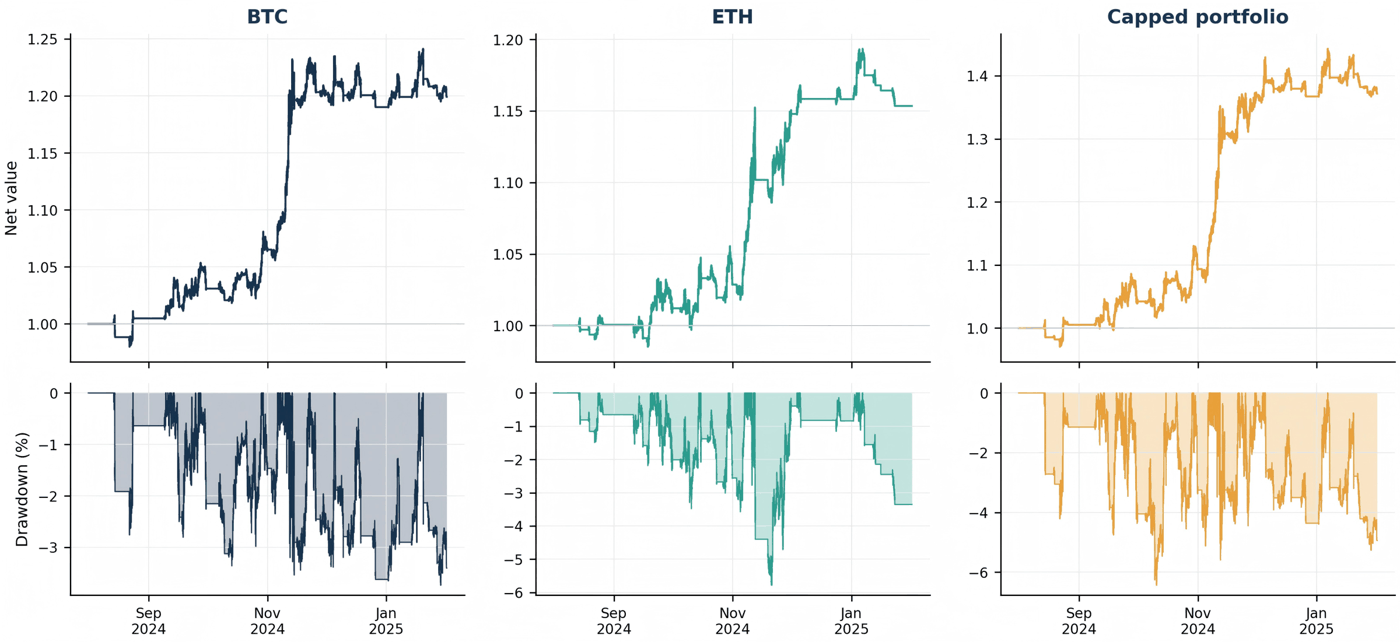
Cryptocurrency swing trading spans mismatched timescales: positions remain active while market and event risk can change within minutes. However, many predictive and large language model (LLM)-based trading systems assess risk after strategy generation or run both functions at the same cadence, leaving proposals unconditioned by current risk and exposure weakly governed between revisions. We propose SwingGuard, a dual-timescale, long-only multi-agent framework for risk-conditioned strategy generation. At the strategy timescale, specialized analysts synthesize point-in-time technical, sentiment, on-chain, and macroeconomic evidence through bullish-bearish deliberation. The resulting evidence and current risk context are then combined by a Portfolio Architect to form a target position. At the governance timescale, a five-minute Risk Controller performs conditional diagnosis, maintains persistent risk states with staged recovery, audits the proposal, and constrains execution until the next strategy revision. This design allows risk to shape the feasible strategy before proposal finalization while continuing to govern the active position afterward. Evaluations on Bitcoin (BTC) and Ether (ETH) show that SwingGuard preserves positive returns after transaction costs while maintaining shallow drawdowns and strong risk-adjusted performance on both assets. The exposure-capped joint portfolio achieves a Sharpe ratio of 2.98, compared with 2.79 for an otherwise identical Post-hoc Risk variant. Structured traces further link risk evidence and state transitions to strategy constraints and executed position changes, providing an auditable framework for asynchronous cryptocurrency swing trading. Overall, the results indicate that conditioning strategy formation on current risk, together with persistent high-frequency governance, improves risk-adjusted performance without sacrificing auditability.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).