RePEcEconometrics & Forecasting
Improving inflation forecasting by modeling expectation de-anchoring in low-inflation periods
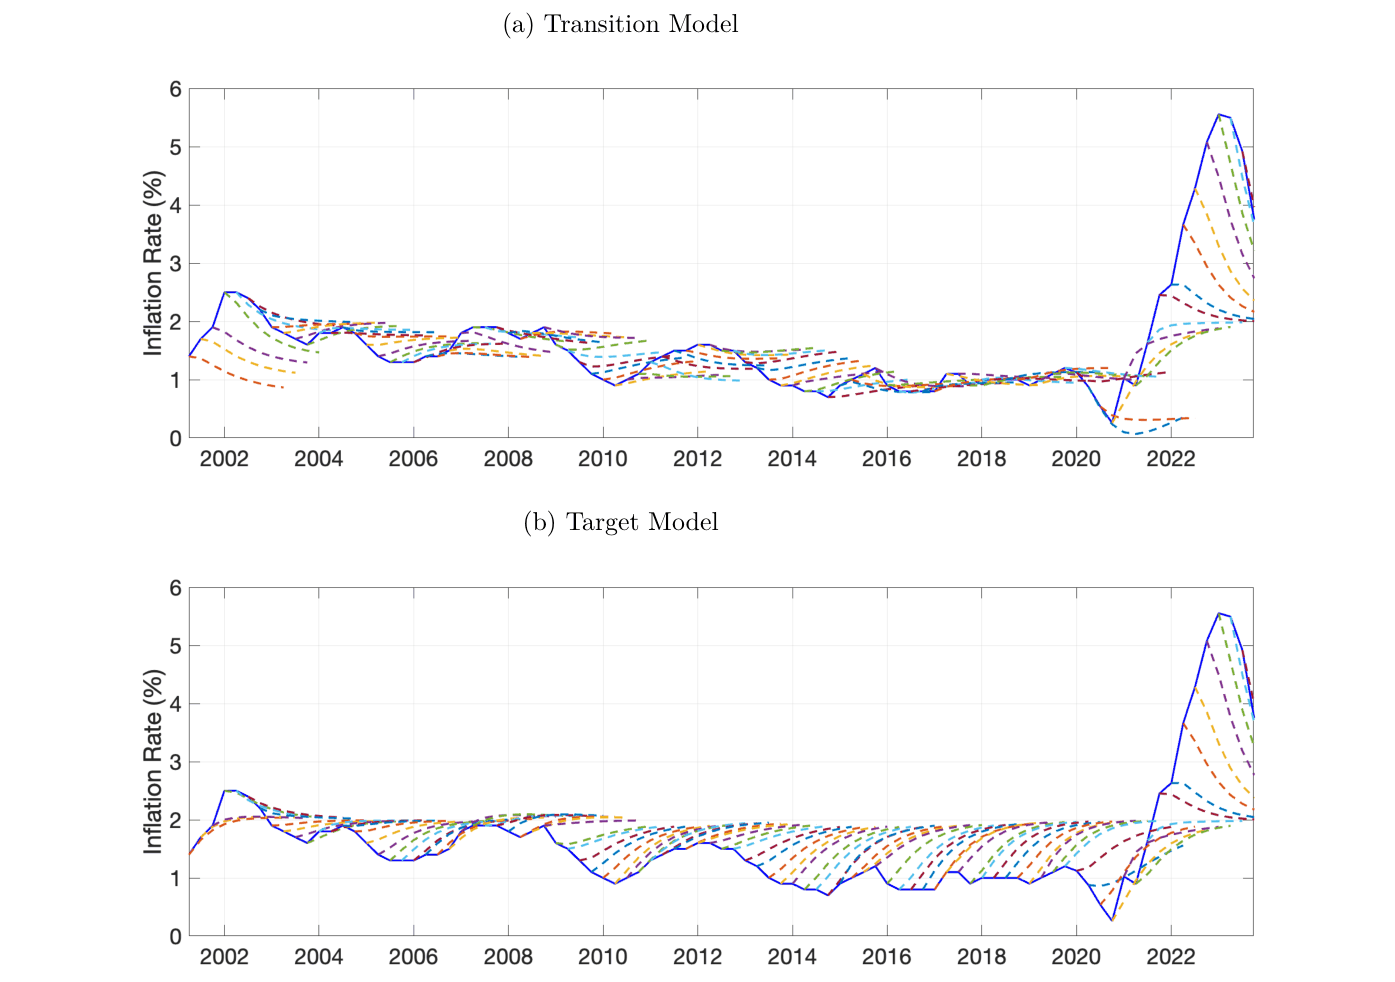
A model allowing expectations to shift to a low-inflation equilibrium cuts forecast errors roughly 50 percent versus central bank projections for euro area core inflation in the 2010s.
Featured in No. 138 on 6 Nov 2026 · 4 days after release
- Released
- 2 Nov 2026
- First featured
- No. 138 · 6 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:zbw:imfswp:344239
- Authors
- Alicia Pita Marcet et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).