RePEcEconometrics & Forecasting
Behind the curve: Reassessing inflation risks with a High-dimensional Distributional VAR (HiDVAR)
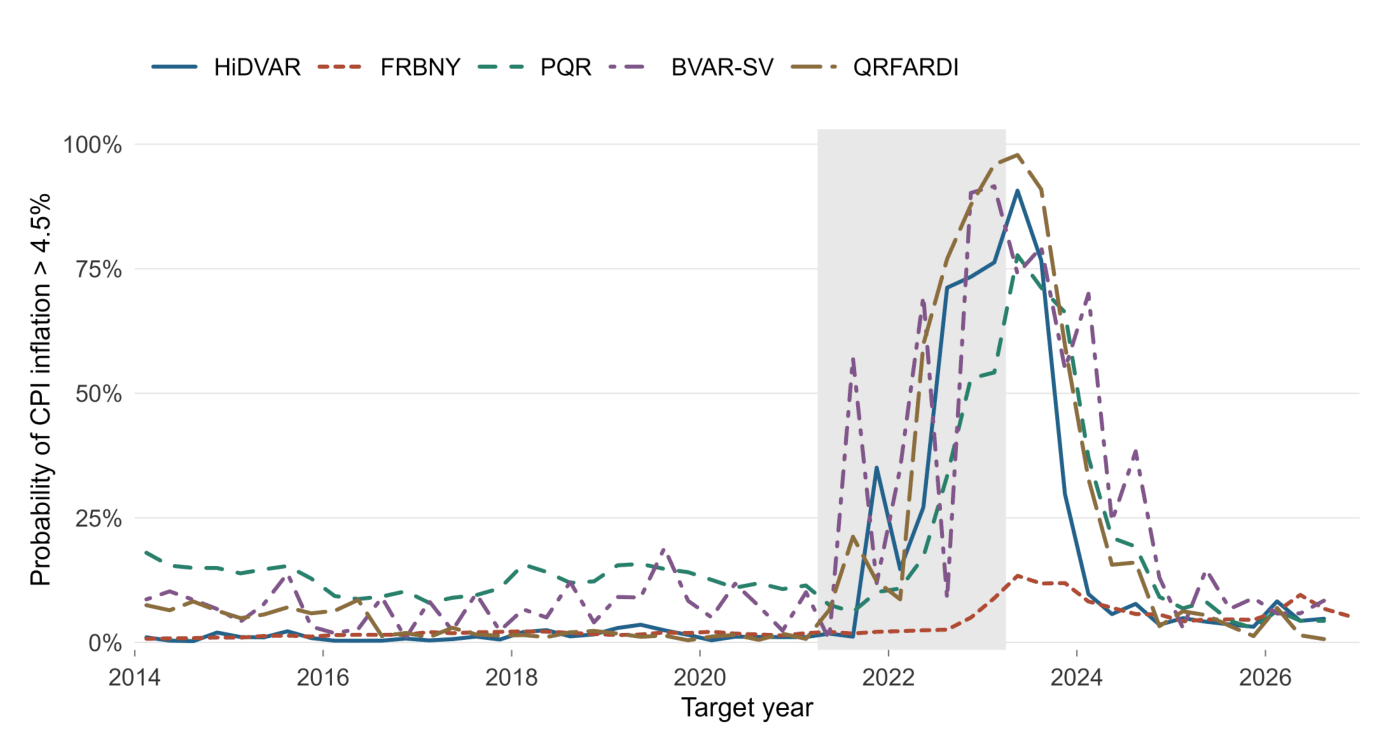
HiDVAR, a data-rich distributional framework, improves inflation tail-risk assessment by 28% in CRPS relative to standard benchmarks and performs well in real-time evaluation.
Featured in No. 138 on 6 Nov 2026 · 4 days after release
- Released
- 2 Nov 2026
- First featured
- No. 138 · 6 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 4 of 5
- Identifier
- RePEc:zbw:imfswp:344237
- Authors
- Luca Schmitz
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).