Bank Runs and Gold-Price Returns and Volatility: Evidence from Centuries of Data
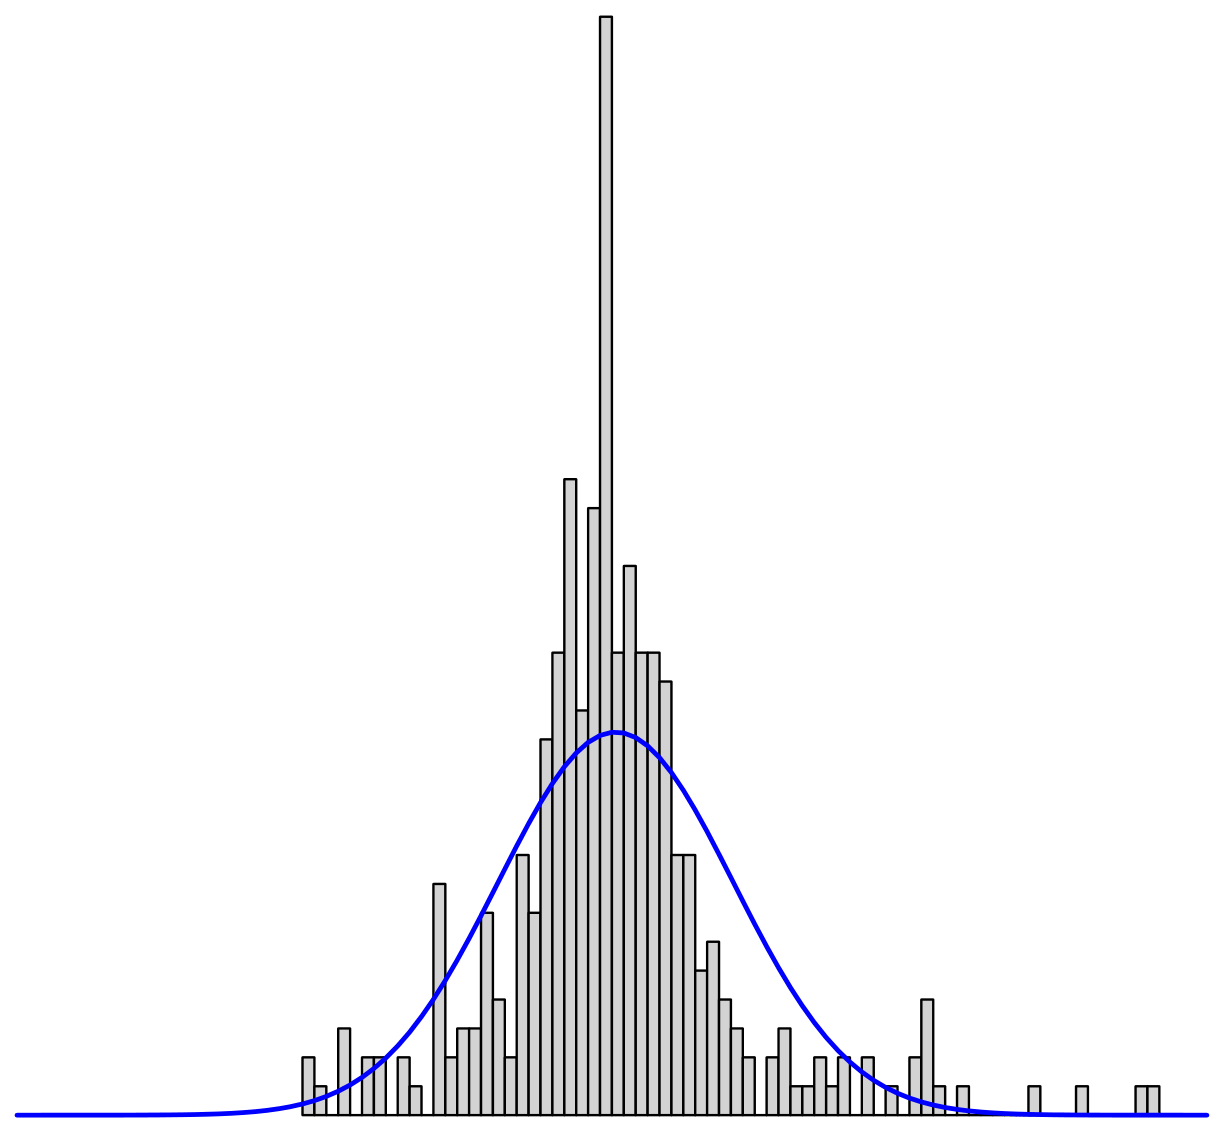
Accounting for bank runs in GARCH models improves in-sample and out-of-sample performance for modeling gold price returns and volatility using annual data since 1694.
Featured in No. 139 on 13 Nov 2026 · 4 days after release
- Released
- 9 Nov 2026
- First featured
- No. 139 · 13 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:pre:wpaper:202637
- Authors
- Ruipeng Liu et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).