Fiscal transmission to asset prices in the United States: evidence from deficit shocks, 2002-2024
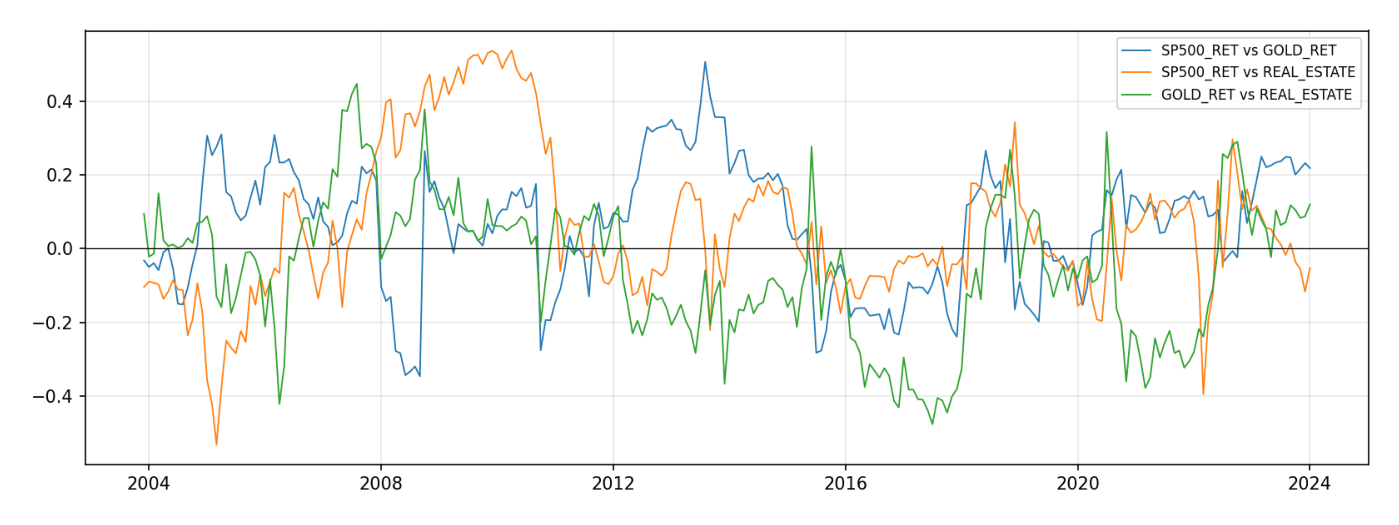
A VAR analysis finds deficit shocks raise S&P 500 prices by 1.97% and house prices by 0.55% on average over twelve months, but the relationship is unstable after 2009.
Featured in No. 140 on 20 Nov 2026 · 4 days after release
- Released
- 16 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:osf:socarx:ngcy6_v1
- Authors
- Jorge Aníbal Restrepo-Morales et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).