Risk and Return in Government Bonds
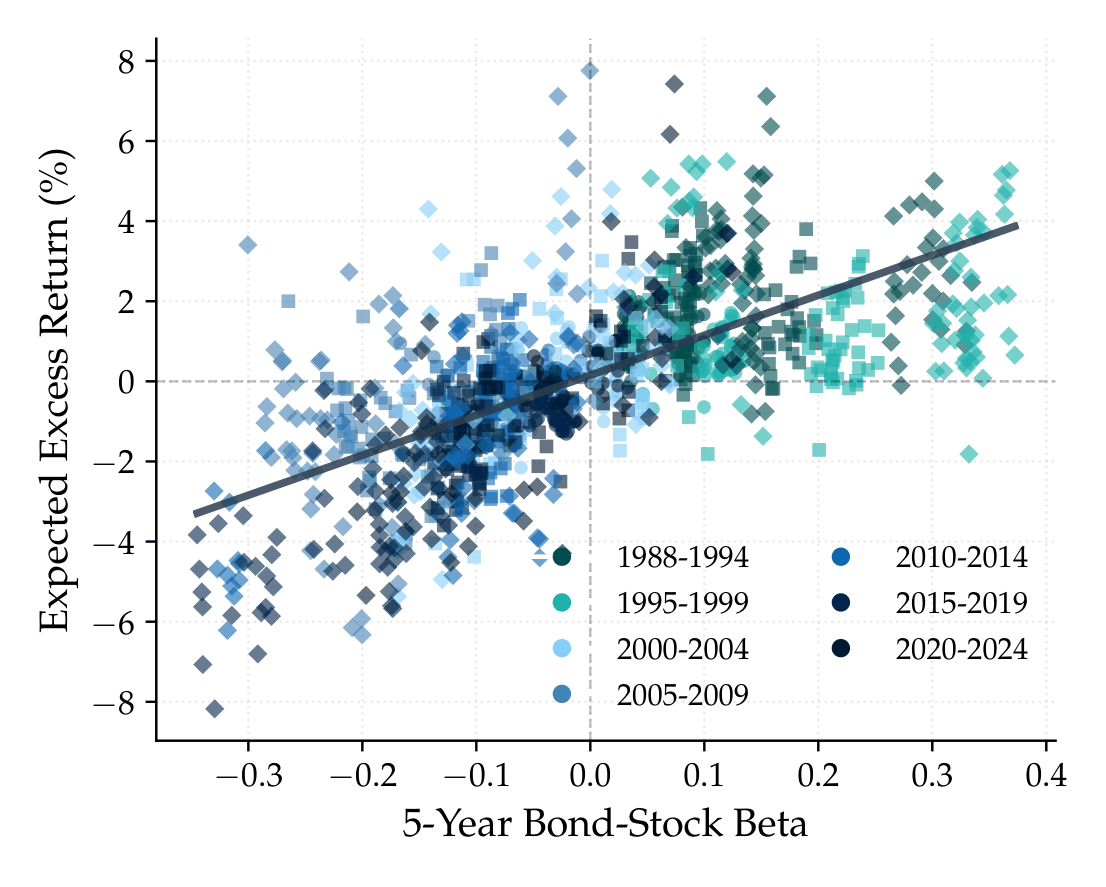
Expected excess returns on government bonds correlate 67% with bond-stock betas and account for more than half of long-term yield moves since the mid-1980s.
Featured in No. 139 on 13 Nov 2026 · 4 days after release
- Released
- 9 Nov 2026
- First featured
- No. 139 · 13 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:nbr:nberwo:35973
- Authors
- Matteo Leombroni et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).