Asymmetric Reversals
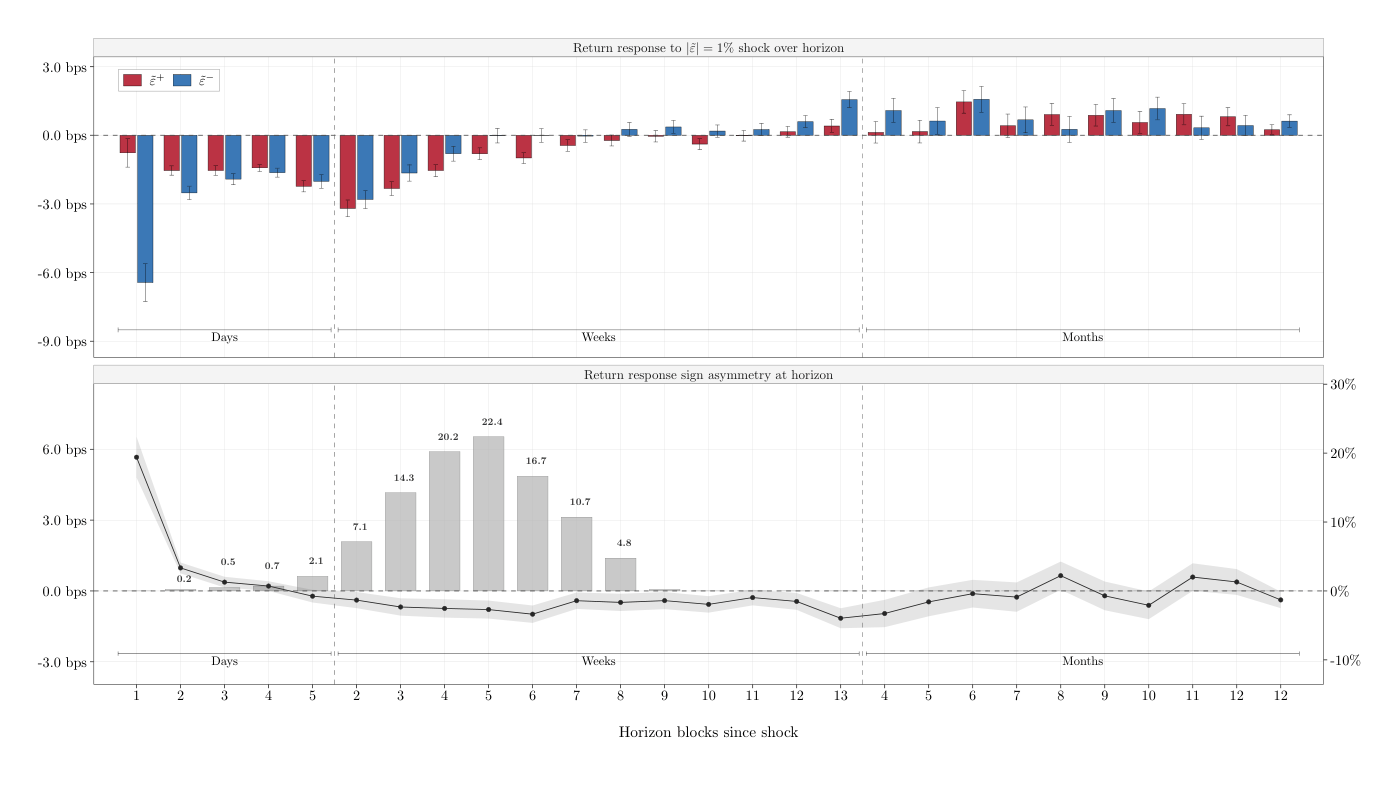
Positive residual stock shocks reverse slower than negative shocks, and this asymmetric reversal explains short-term predictability better than idiosyncratic volatility alone.
Featured in No. 139 on 13 Nov 2026 · 4 days after release
- Released
- 9 Nov 2026
- First featured
- No. 139 · 13 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 4 of 5
- Identifier
- RePEc:nbr:nberwo:35840
- Authors
- Federico Baldi-Lanfranchi et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).