Volatility Disagreement in the Options Market
Cross-sectional dispersion in volatility forecasts predicts delta-hedged straddle losses of 5.14% per month, consistent with mispricing rather than risk compensation.
Featured in No. 134 on 9 Oct 2026 · 2 days after release
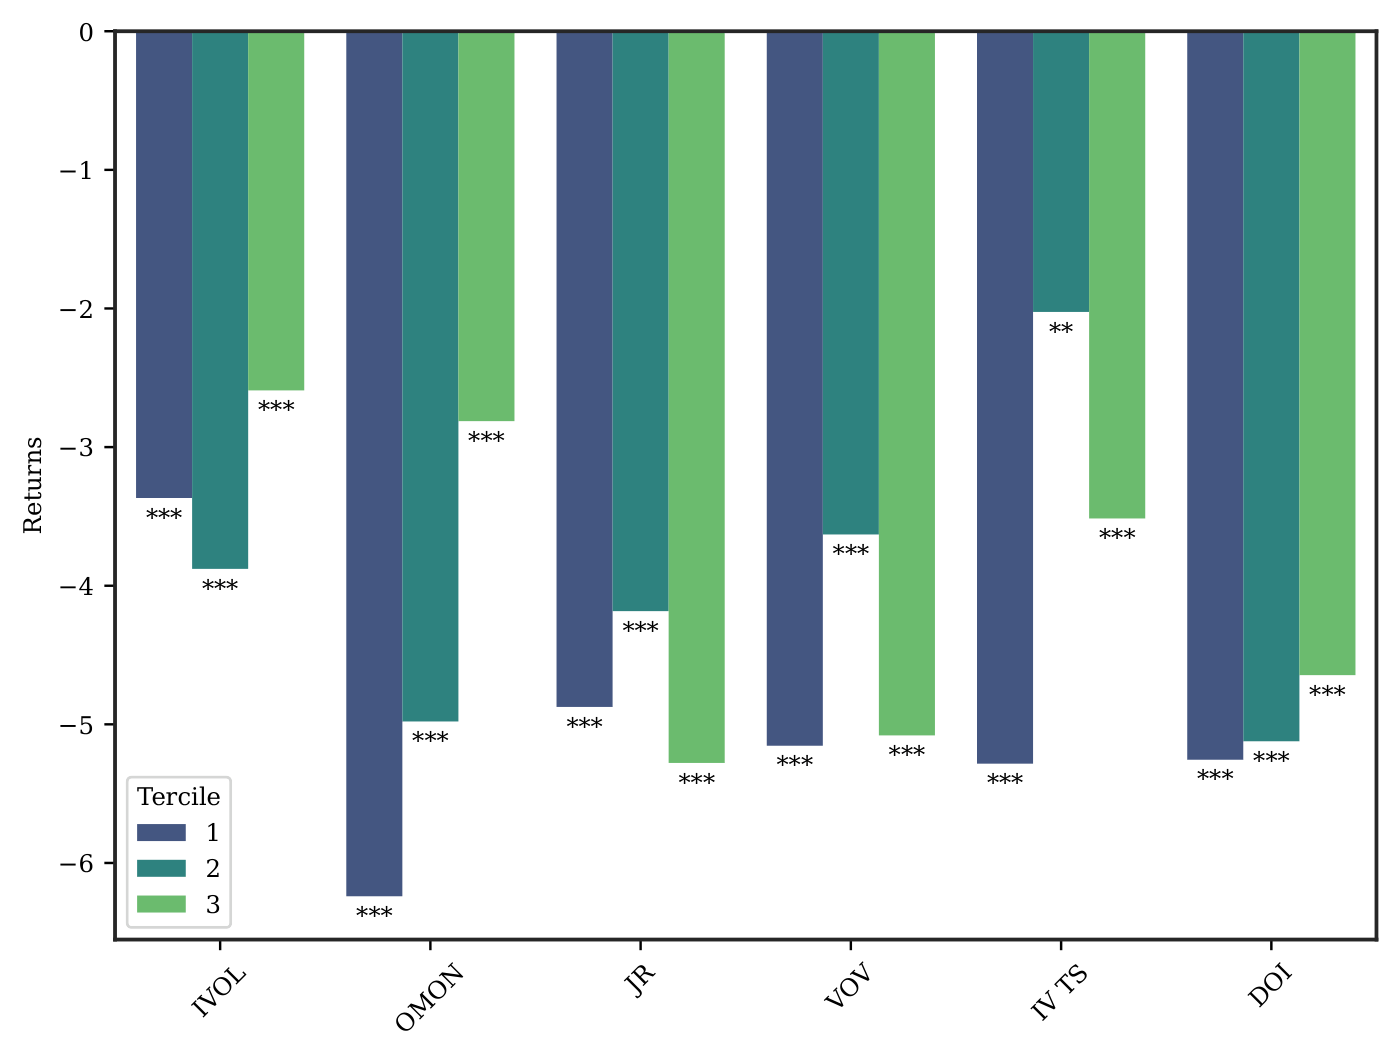
- Released
- 7 Oct 2026
- First featured
- No. 134 · 9 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:nbr:nberwo:35500
- Authors
- Turan G. Bali et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).