ML-QuantSubscribe

Quant Letter

October 2026, Week 2

The week in quantitative finance research: 90 papers from arXiv, SSRN and RePEc, screened and ranked, 3–9 Oct 2026.

Papers
90
New this week
90
With figures
52
High fanfare
13

From the editor

This week centers on AI systemic risk, factor discovery limits, and monetary transmission channels. Agentic AI systems create non-diversifiable contagion floors despite fleet size; automated factor mining shows no paradigm dominates; and Fed policy transmits primarily through risk appetite shifts rather than rates. See "Agentic AI and Systemic Risk," "FactorBench," and "Risk Appetite and Monetary Transmission."

Top picks

If you read five papers this week, read these.

  1. Agentic AI and Systemic Financial Risk

    The study shows that agentic AI systems sharing a foundation model create non-diversifiable common exposure whose systemic risk floor does not shrink as the fleet grows, shifting concern from individual model risk to population-level contagion.

    Fanfare 4Risk, Credit & Banking
    2: The set-valued risk measure \rho(X) . The acceptable set of containment configurations (green), coloured elsewhere
  2. Surveys fifty years of quantitative investing as a history of changing implementation boundaries from diversification through machine learning, emphasizing alpha decay and the gap between research and production systems.

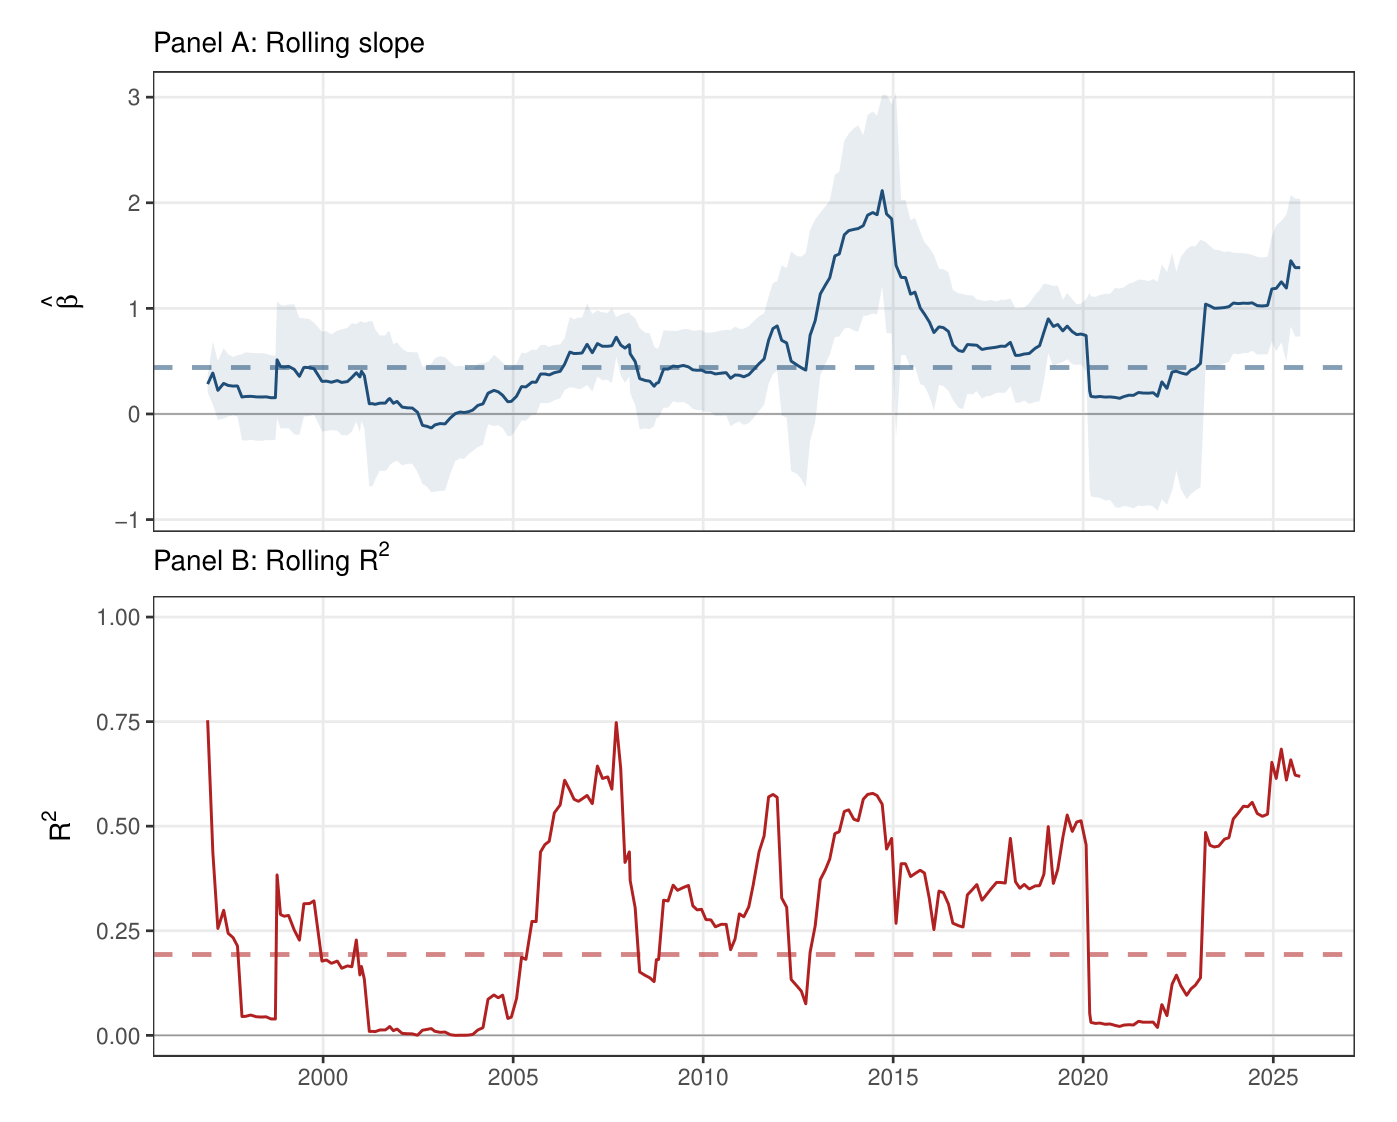
  3. Rolling regression of RISK on MPS
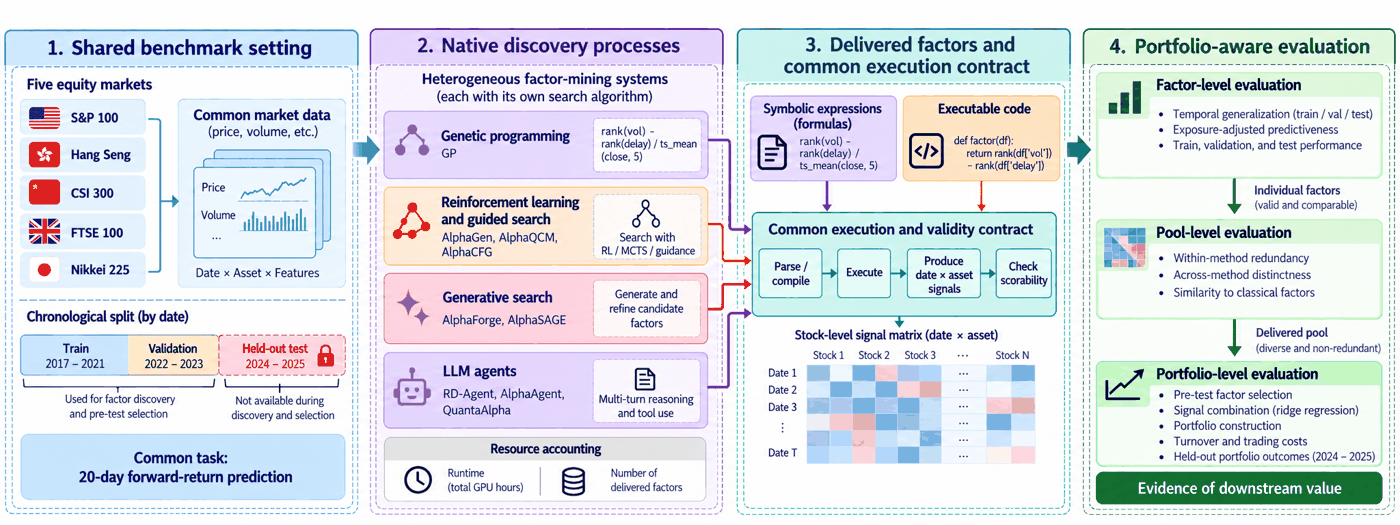
  4. Overview of FactorBench
  5. An autonomous agent evolved 940 factors over 17 days and finds that reusing backtest data inflates edge by a quarter to a third and in-sample improvement predicts worse performance.

What's rising

Topics drawing unusually many papers this week.

  1. Housing

    1.8×

    4.6% of this week's 776 new papers, 1.8x its share over the previous 2 weeks (2.6%).

  2. ETFs and funds

    1.6×

    4.4% of this week's 776 new papers, 1.6x its share over the previous 2 weeks (2.8%).

  3. Volatility forecasting

    1.5×

    2.6% of this week's 776 new papers, 1.5x its share over the previous 2 weeks (1.8%).

GitHub radar

What the quant community starred on GitHub this week, from a panel of 10,589 developers who follow financial machine learning (271 of the 860 we checked starred something). Counts only: we never publish who starred what.

Quant repos rising

  1. AI trading agent executing trades on Monad blockchain.

    ★ 2,912+167 this weekTypeScriptNew repo

  2. Autonomous financial deep research framework.

    ★ 196+8 this weekPythonNew repo

  3. AI stock monitoring for A-shares, HK and US markets.

    ★ 2,047+104 this weekPython

What quants are playing with

  1. morluto/rea35 quants

    Reverse engineer apps and binaries using AI agents.

    ★ 37.0k+36.6k this weekTypeScript

  2. Open-source Rust reimplementation of Adobe Photoshop.

    ★ 32.1k+32.0k this weekRustNew repo

  3. openai/math21 quants

    Mathematics library in Lean.

    ★ 12.8k+12.8k this weekLeanNew repo

  4. Run Qwen3.8-Flash on consumer hardware with local APIs.

    ★ 19.2k+12.3k this weekC++New repo

  5. End-to-end testing framework for web and mobile apps.

    ★ 8,332+6,418 this weekTypeScriptNew repo

  6. Tool for porting PS5 executables to Linux and Windows.

    ★ 19.6k+16.6k this weekC++New repo

  1. Now publishedDynamic resource allocation with karma: An experimental study

    Now published in Journal of Economic Behavior & Organization · featured 8 Jan 2025; 4 citations

  2. 50 citationsAttention-based Dynamic Multilayer Graph Neural Networks for Loan Default Prediction

    Passed 50 citations · featured 7 Feb 2024, 6 days after release

  3. 25 citationsA comparison of cryptocurrency volatility-benchmarking new and mature asset classes

    Passed 25 citations · featured 10 Apr 2024, 3 days after release

All papers

Filter by venue, topic or fanfare.

Venue
Topic
Fanfare
90 papers

arXiv

Quantitative finance and ML-for-finance preprints

30 papers · 30 figures

Risk, Credit & Banking3

01

Agentic AI and Systemic Financial Risk

The study shows that agentic AI systems sharing a foundation model create non-diversifiable common exposure whose systemic risk floor does not shrink as the fleet grows, shifting concern from individual model risk to population-level contagion.

Fanfare 4Risk, Credit & BankingSriram Nagaraj and Seung Jung LeePDF
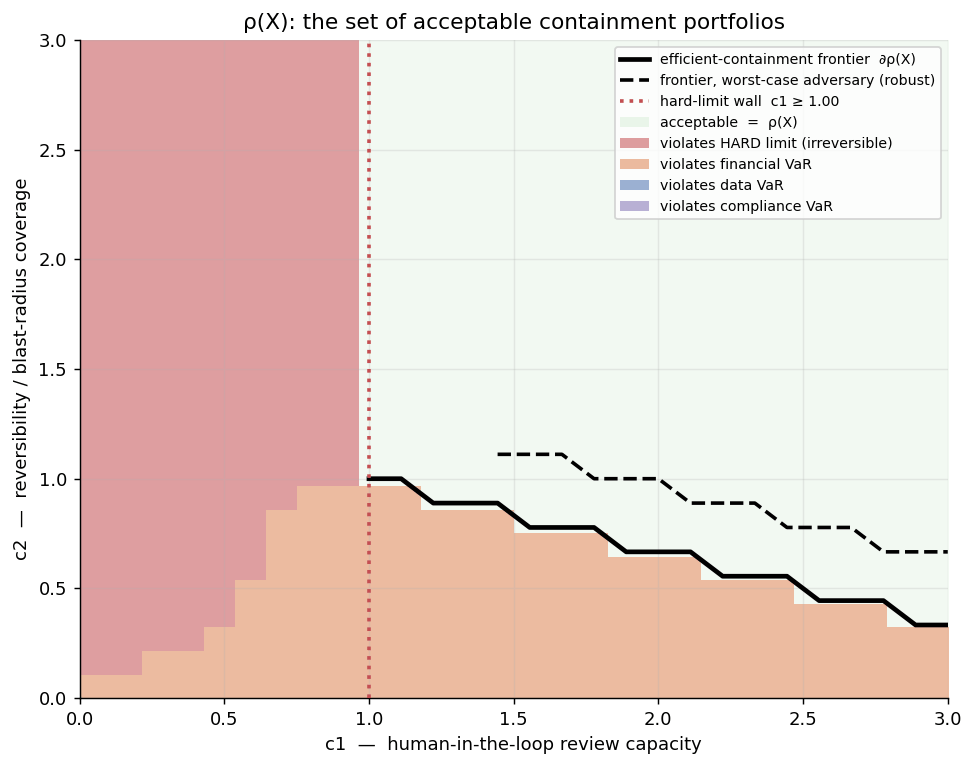
2: The set-valued risk measure \rho(X) . The acceptable set of containment configurations (green), coloured elsewhere
Figure 1.2: The set-valued risk measure \rho(X) . The acceptable set of containment configurations (green), coloured elsewhere by the binding constraint. The red wall is…
21

Ranking Prior Alignment for Credit Risk

A model-agnostic framework distills ranking priors from experts or teacher models into credit scorers via KL divergence, improving cold-start performance with scarce labeled data.

Fanfare 3Risk, Credit & BankingQiye Lu et al.PDF

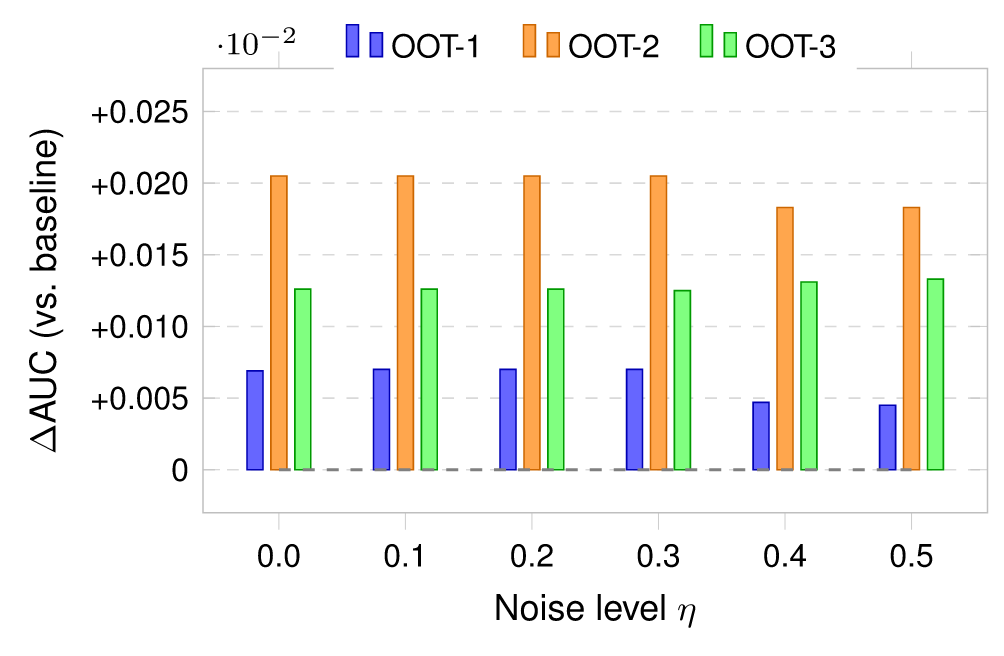
Robustness checks and ablation studies
Figure 4. Robustness checks and ablation studies. Alignment remains beneficial across all prior noise levels \eta\leq 0.5 for tree-based models, demonstrating tolerance…
27

Regime-Aware Equity Correlation Matrices

Fitting separate dependence matrices to lower-tail, central, and upper-tail regimes reveals tail-driven co-movements that single Gaussian-copula structures systematically miss.

Fanfare 2Risk, Credit & BankingKatherine B. Ensor et al.PDF

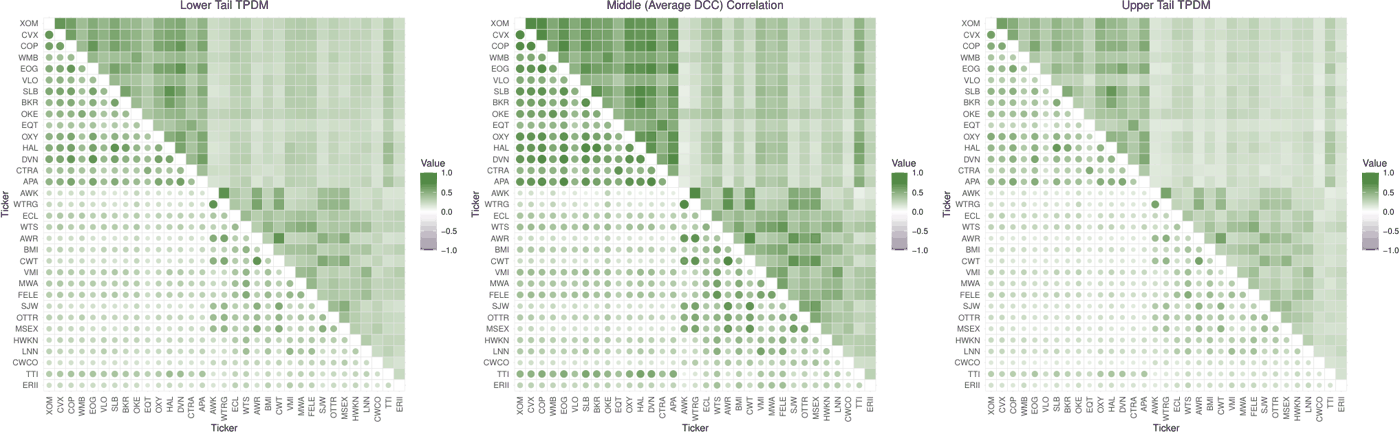
Three regime-specific correlation matrices: lower-tail, middle-regime, and upper-tail heatmaps.
Figure 7 : Three-panel comparison of the regime-specific correlation / dependence matrices on a common [-1,1] color scale: lower-tail TPDM (left, off-diagonal range [0.1…

Asset Pricing & Factors4

02

FactorBench: Benchmarking Automated Factor Mining

A portfolio-aware benchmark comparing five thousand factors from nine automated mining methods across five equity markets finds that no discovery paradigm consistently dominates in signal quality or portfolio performance.

Fanfare 4Asset Pricing & FactorsZhuohan Wang and Carmine VentrePDF
Overview of FactorBench
Figure 1: Overview of FactorBench.
05

AlphaPADI: Pool-Aware Formulaic Alpha Discovery

Introduces a hierarchical discrete diffusion framework that generates pools of formulaic alphas by reconstructing complete candidate pools under current context and maximizing joint predictive performance and inner diversity.

Fanfare 3Asset Pricing & FactorsYanzheng Jin et al.PDF
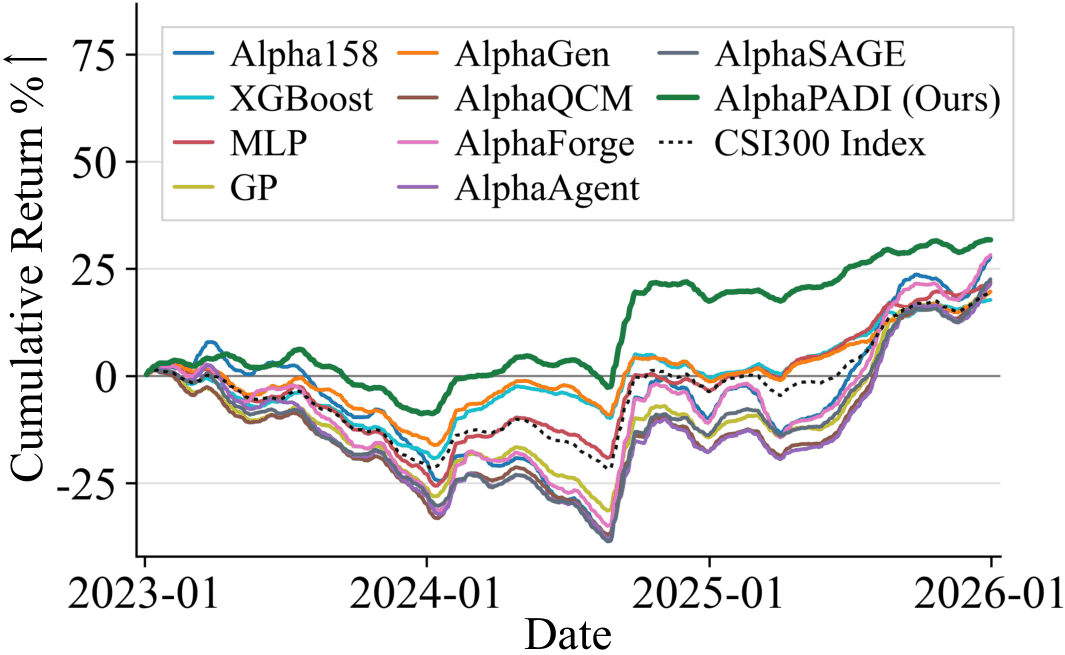
Cumulative returns comparison of AlphaPADI against baseline methods on CSI300 from 2023-2025.
Figure 2: Cumulative returns on CSI300 (2023–2025): AlphaPADI, baseline methods, and the CSI300 index.
10

Admission Gates for Strategy Research

An injected-truth protocol reveals that statistical admission gates eliminate false discoveries in weak-signal regimes but cut adoption rates to 1–7 percent, while criteria computed on absolute rather than excess returns reject all candidates.

Fanfare 3Asset Pricing & FactorsTianlun ZhengPDF
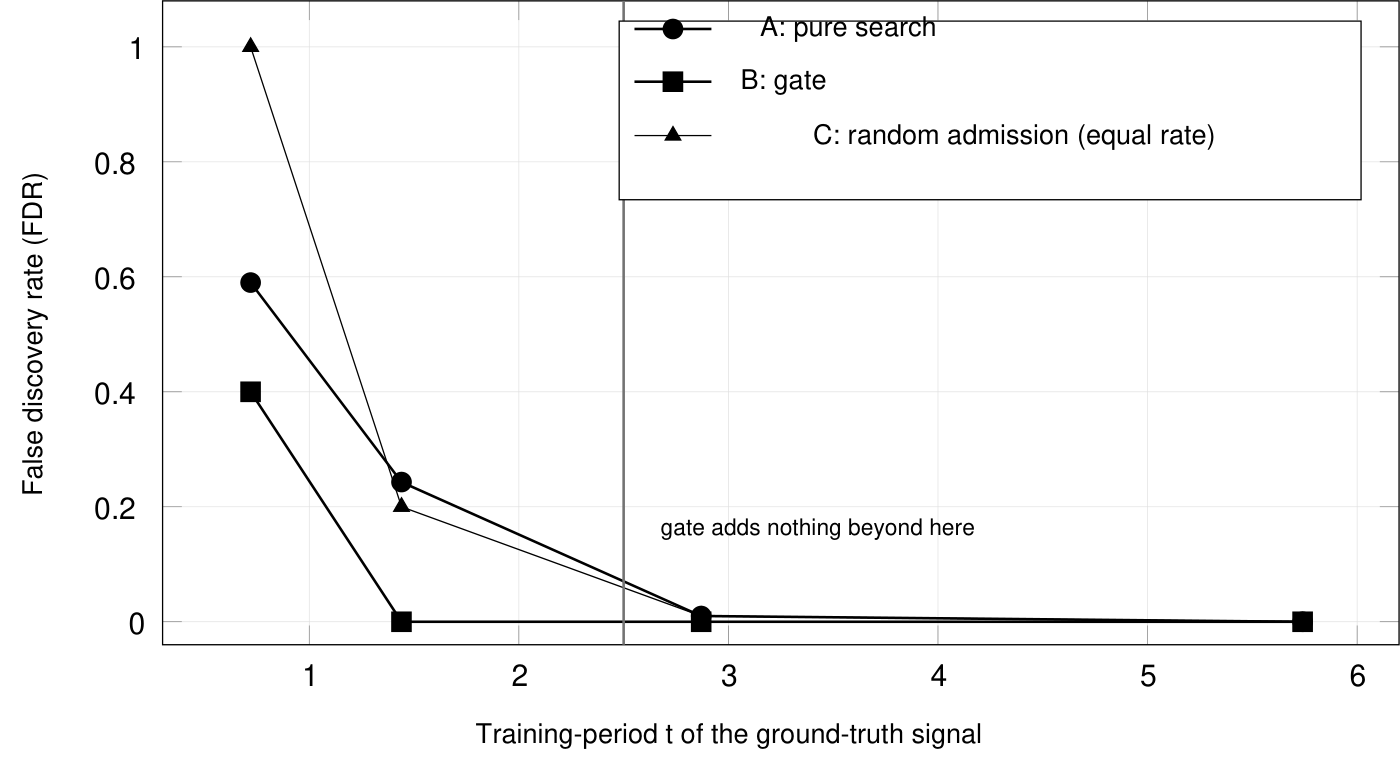
Panel I (400 repetitions)
Figure 2: Panel I (400 repetitions). Pure search errs on 24\% – 59\% of weak-signal adoptions; the gate drives FDR to zero but only below t\approx 2.5 . To the right of…
11

Earnings Disclosure Alignment via Optimal Transport

Decomposing earnings press releases and conference calls into shared and unique textual components shows that unique call content predicts returns better than repeated material.

Fanfare 3Asset Pricing & FactorsYuntao Wu et al.PDF
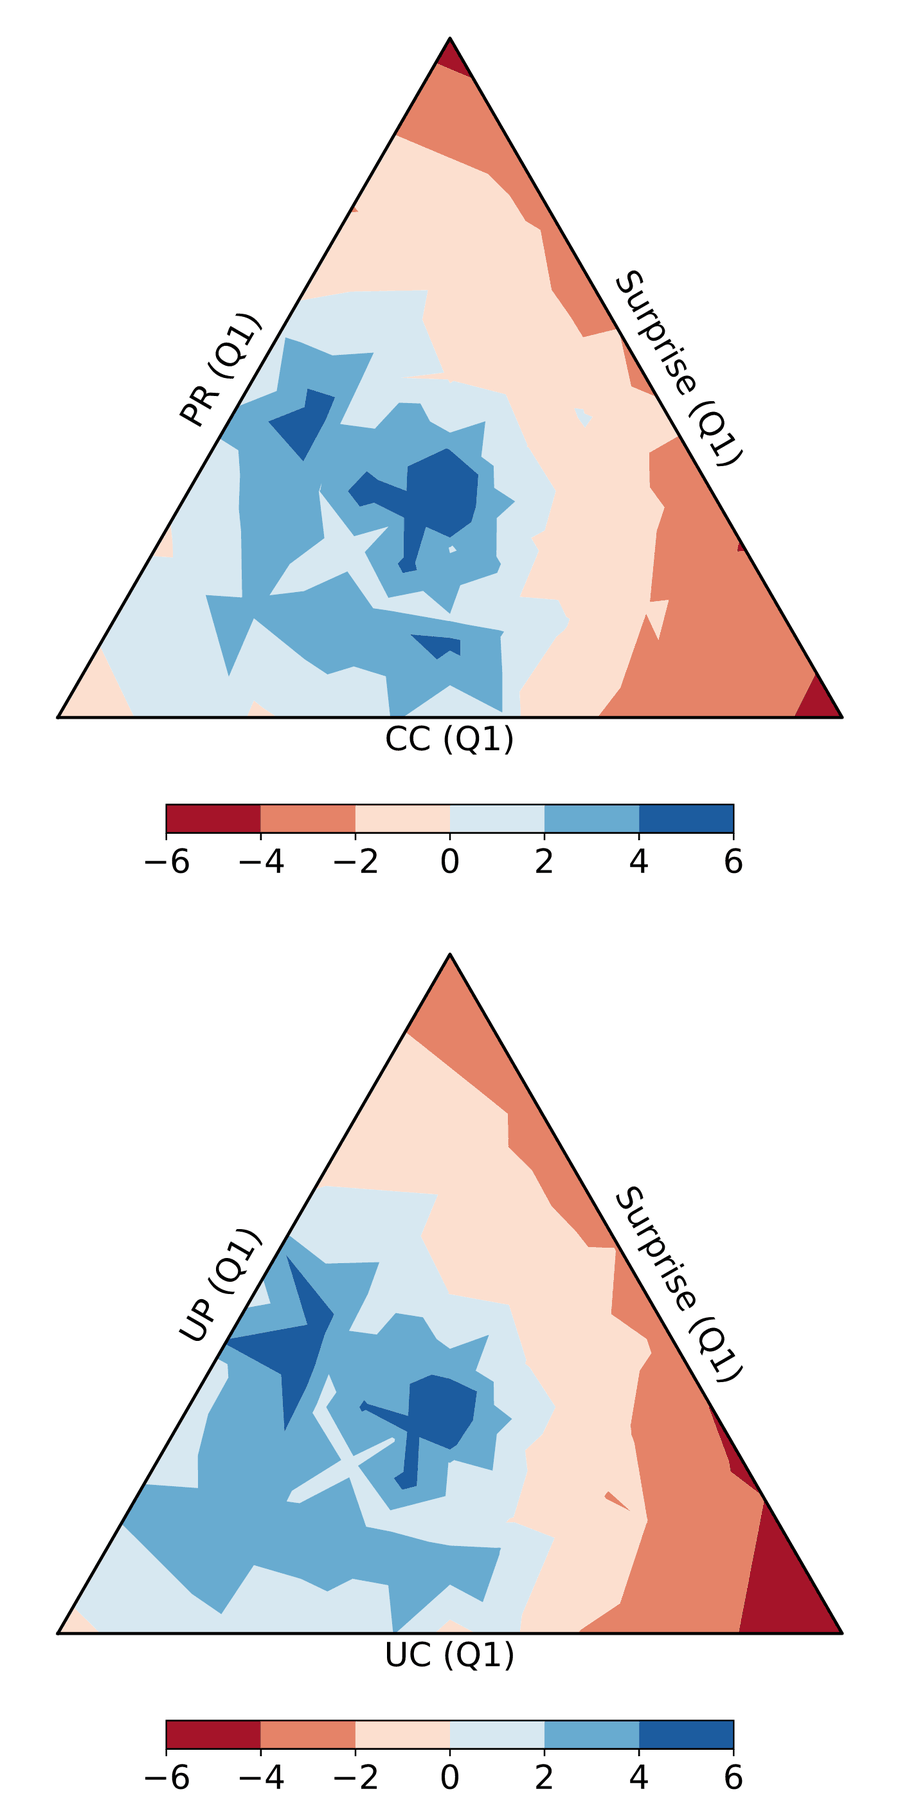
Average Returns (%) Sorted by Surprise and Soft Average return heatmap, sorted by soft and surprise
Figure 3 . Average Returns (%) Sorted by Surprise and Soft Average return heatmap, sorted by soft and surprise

ML & AI Methods6

03

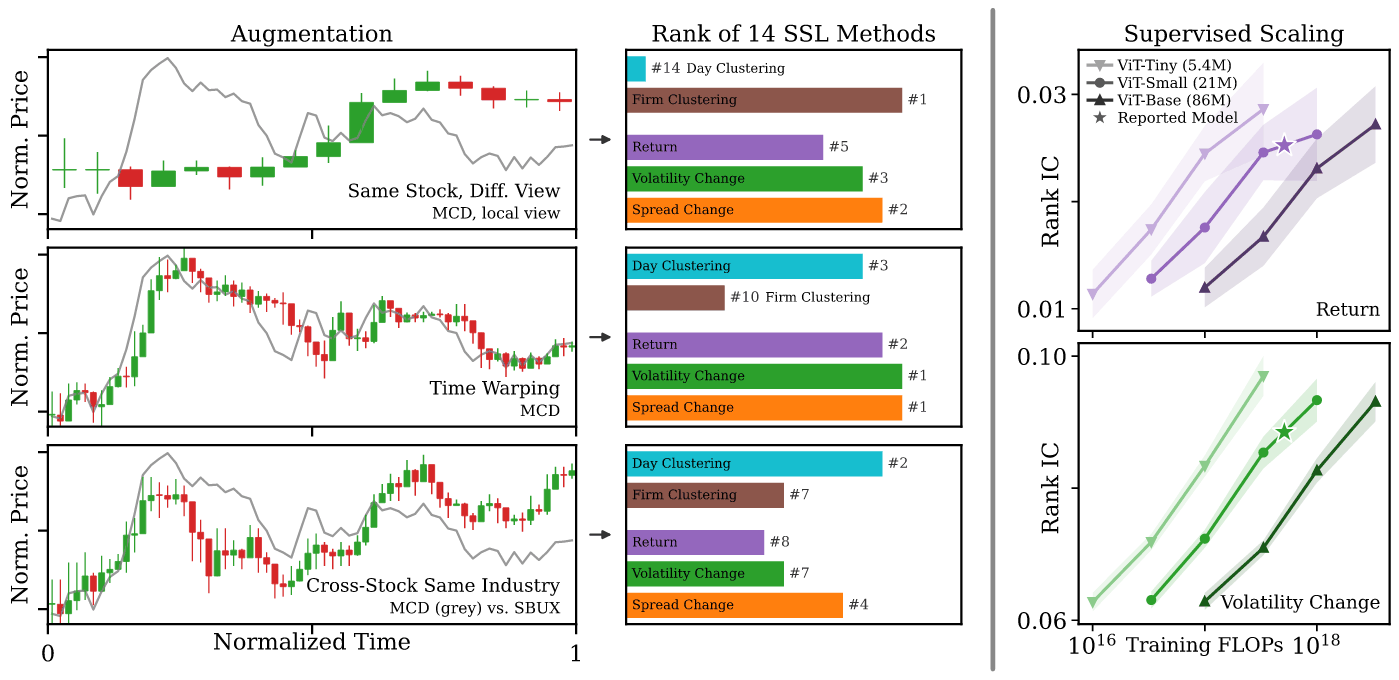
Financial World Modeling with Market-1T

The study introduces a trillion-observation U.S. equity dataset and systematically evaluates 18 representation-learning methods across nearly two decades, finding that encoders with similar predictive performance organize market state very differently.

Fanfare 4ML & AI MethodsHumzah Merchant et al.PDF

Paper overview
Figure 1 : Paper overview. Left: We systematically study how the pre-training objective and data augmentation shape the organization of the latent space and performance…
07

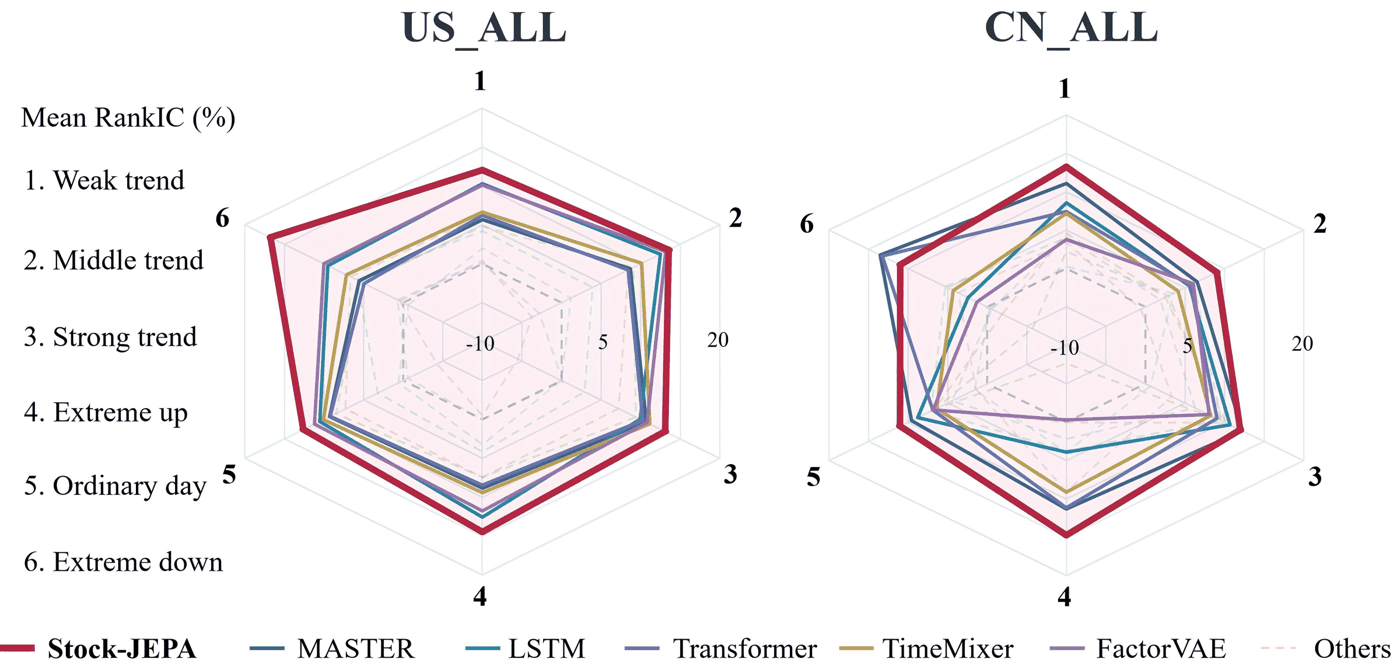
Stock-JEPA: Prior-Anchored Representation Learning

A joint-embedding framework learns predictable incremental revisions from market data relative to a financial prior, combining interpretability from classic models with the pattern-capture strength of deep learning.

Fanfare 3ML & AI MethodsYizhi Luo et al.PDF

Predictive utility across market states
Figure 7: Predictive utility across market states. Mean RankIC (%) over three runs on US_ALL (left) and CN_ALL (right), using a common radial scale. Trend states (axes 1…
12

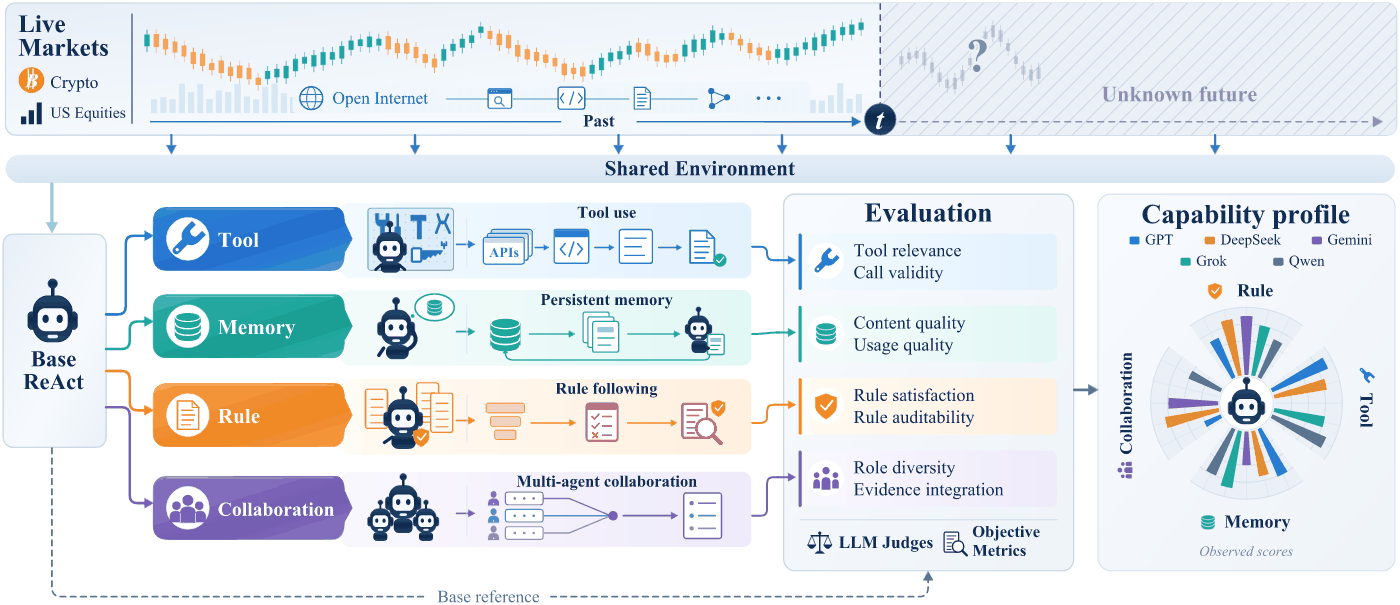
LiveMACE: Process-Aware LLM Agent Evaluation

A benchmark evaluates frontier LLMs as live trading agents and finds that realized returns often diverge from capability-specific measurements, revealing outcome-capability gaps through decision traces.

Fanfare 3ML & AI MethodsJun Zhao et al.PDF

LiveMACEBench overview
Figure 1 : LiveMACEBench overview. Agents interact with a shared, continuously evolving live-market environment along persistent trajectories. Evaluation combines realiz…
13

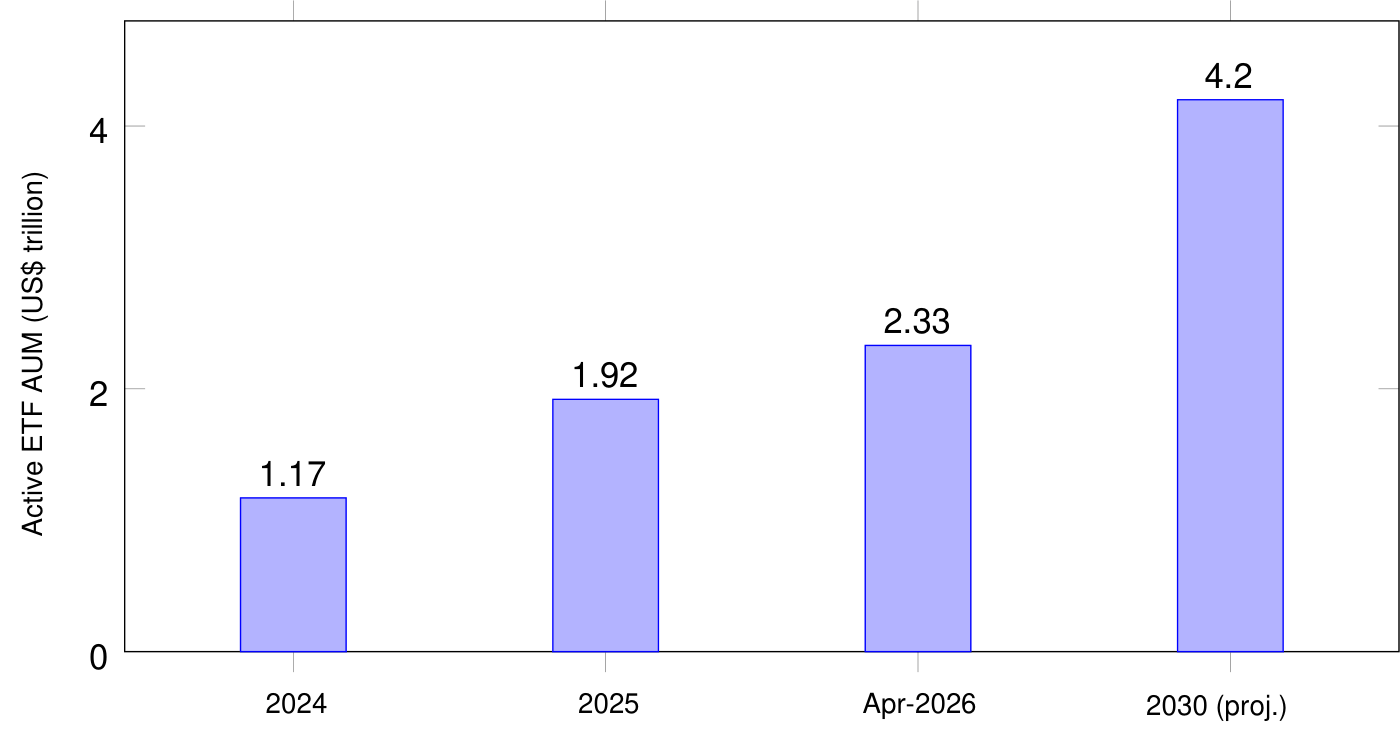
Agentic ETFs as Emerging Asset Class

Proposes that large-language-model-driven trading agents delegated to autonomous execution define a nascent asset class, mapping infrastructure layers and projecting potential trillions in assets by 2030.

Fanfare 3ML & AI MethodsAmandeep SinghPDF

Actively managed ETF assets under management, actuals and industry projection
Figure 1: Actively managed ETF assets under management, actuals and industry projection.
15

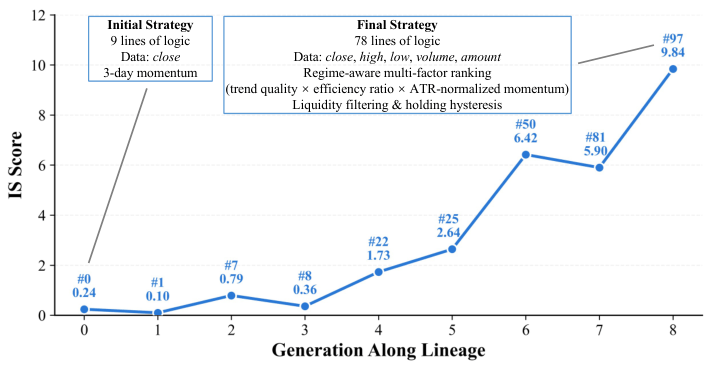
TradeGrad: Textual Gradient Strategy Optimization

Proposes an LLM-guided framework for trading strategy refinement using accumulated experience and cross-period robustness, achieving 27.99% annualized return on Chinese equities with 1.63 Sharpe ratio.

Fanfare 3ML & AI MethodsChaoqun Yang et al.PDF

Evolution of a final strategy along its ancestral lineage
Figure 5: Evolution of a final strategy along its ancestral lineage. Labels indicate program IDs and IS Scores.
17

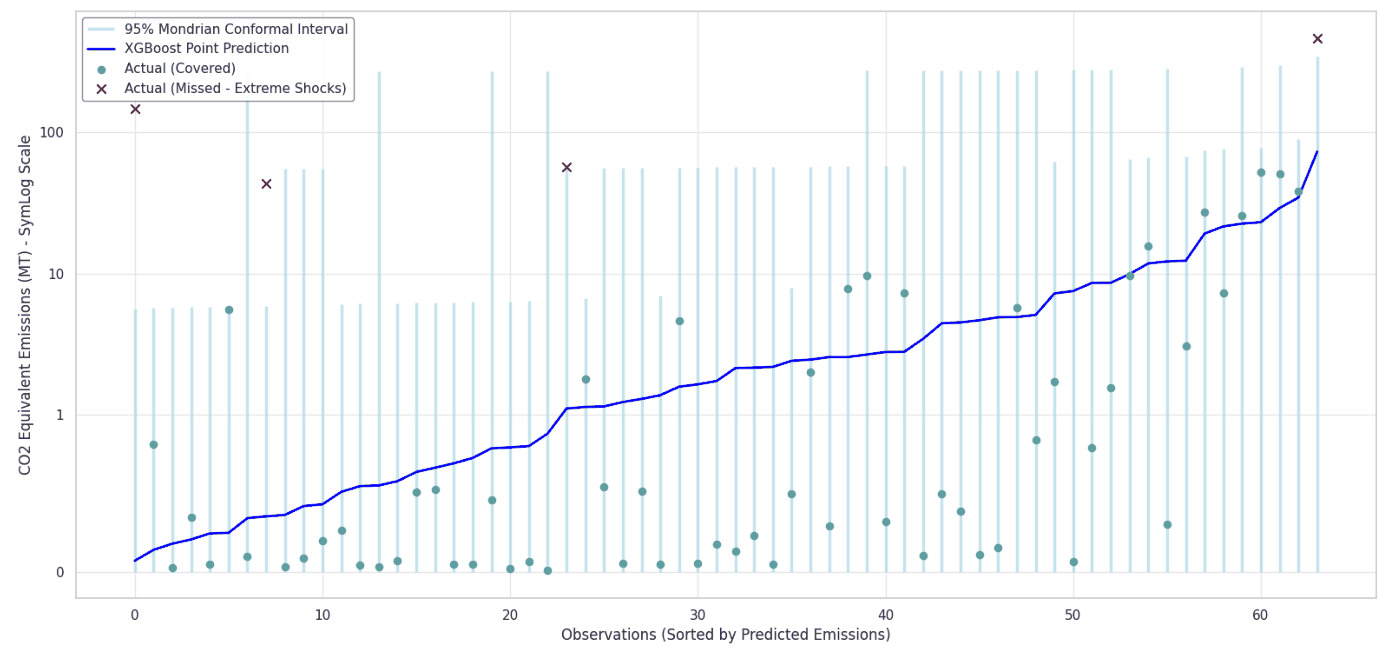
Algorithmic Greenwashing Detection in ESG

Fuses SEC financials with EPA emissions data and conformal machine learning to quantify divergence between self-reported and physical emissions, finding algorithmic divergence predicts lower valuation and profitability.

Fanfare 3ML & AI MethodsSourav Bose and Taoufik BouraouiPDF

Uncertainty Quantification via Mondrian Conformal Prediction (Discrete Bounds)
Figure 7: Uncertainty Quantification via Mondrian Conformal Prediction (Discrete Bounds)

LLMs & Text2

04

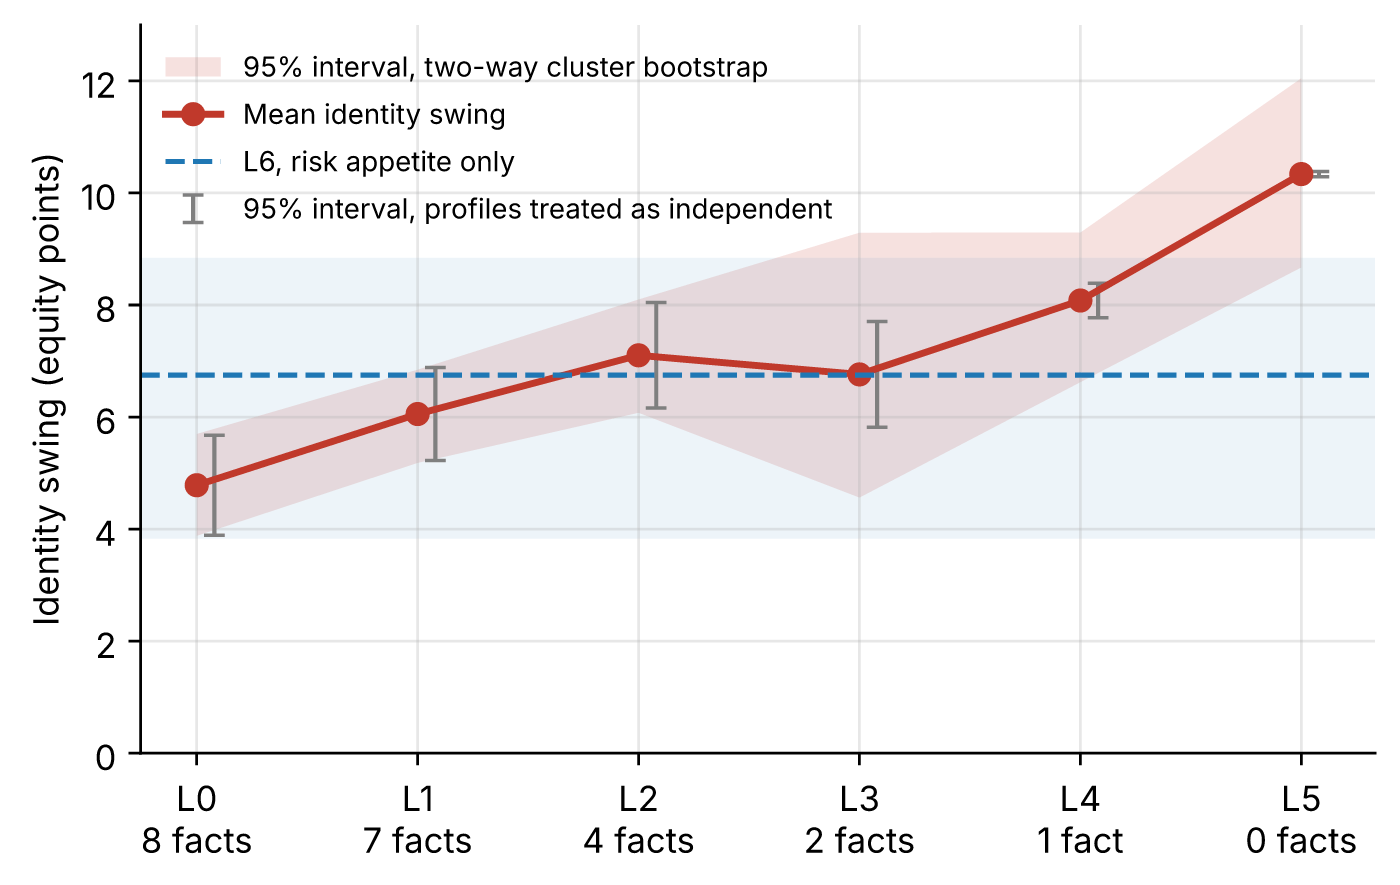
How LLMs Fill Missing Financial Information

When financial facts are withdrawn from prompts, identity attributes explain 96% of variation in equity allocation advice from a language model, replacing missing evidence.

Fanfare 4LLMs & TextSaanvi Khetan and Sankar BalasubramanianPDF

Mean identity swing in equity allocation versus evidence level with 95% confidence interval band.
Figure 1 : The prior substitution curve. Mean identity swing in recommended equity allocation at each level of the evidence dial. The shaded band is the 95% interval fro…
14

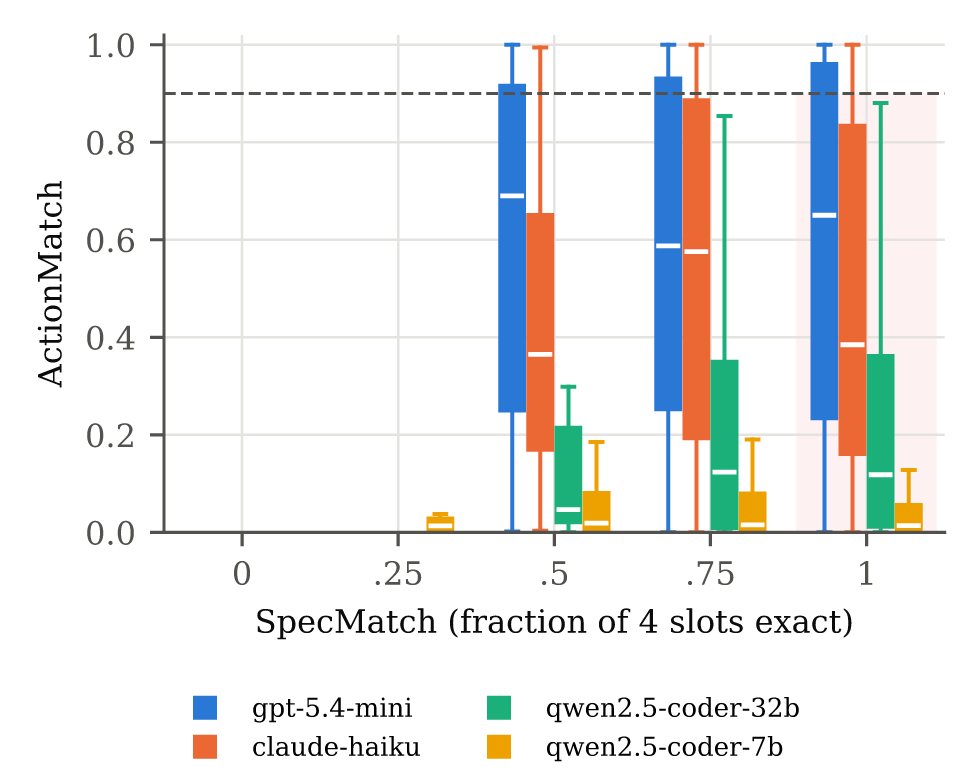
MintEval: Behavioral Testing for Trading Code

Introduces a benchmark that compares LLM-generated trading code to reference strategies bar by bar on identical data, revealing silent failures in implementation despite passing functional tests.

Fanfare 3LLMs & TextSiyu Wang et al.PDF

Closed setting: SpecMatch vs ActionMatch per task
Figure 2. Closed setting: SpecMatch vs ActionMatch per task. Shaded: specification fully correct but behaviour diverges. Scatter plot of ActionMatch against SpecMatch fo…

Derivatives & Volatility3

06

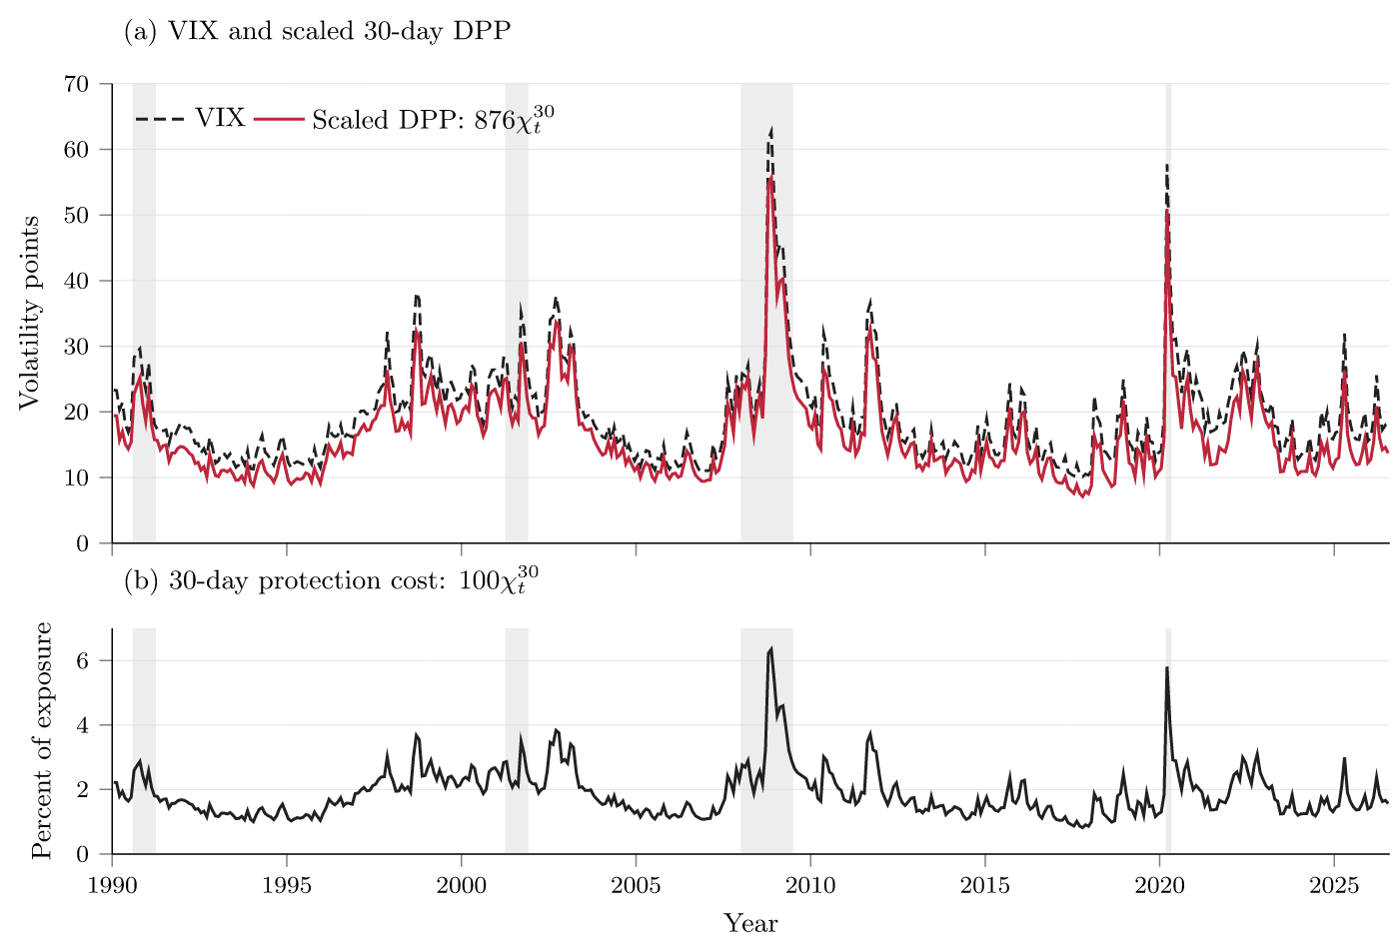
VIX Decomposition: Probability and Severity

Separating risk-neutral shortfall probability from conditional severity in option prices shows that severity accounts for 91.5 percent of recession log premium movements, supplying joint empirical restrictions on uncertainty and economic activity.

Fanfare 3Derivatives & VolatilityTodd B. WalkerPDF

Monthly 30-day downside protection premium and VIX. Panel (a) compares the VIX with the fixed benchmark
Figure 2 : Monthly 30-day downside protection premium and VIX. Panel (a) compares the VIX with the fixed benchmark 876\chi_{t}^{30} in volatility points. Panel (b) repor…
19

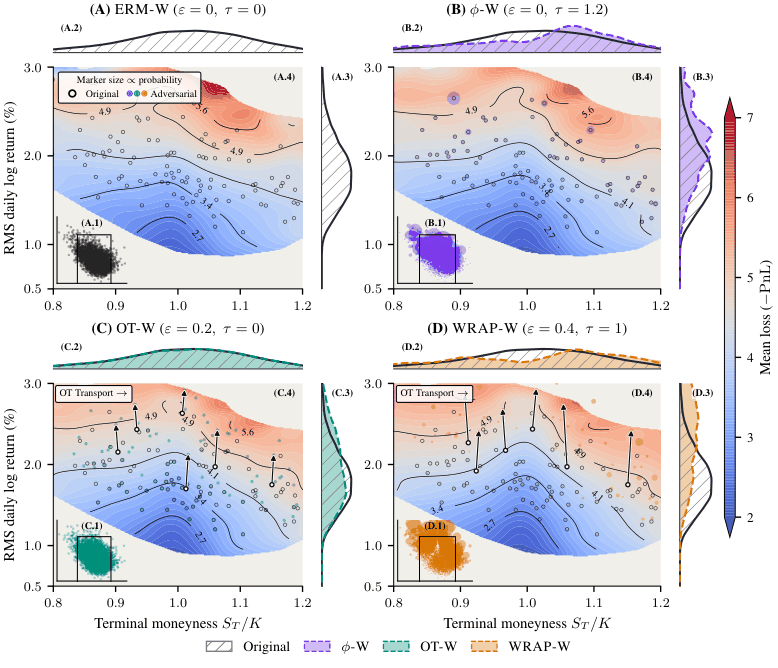
Adversarial Training for Deep Hedging

WRAP combines Wasserstein reweighting and optimal-transport perturbations in a distributionally robust framework to make deep hedging policies robust to nonstationarity and distributional drift in market conditions.

Fanfare 3Derivatives & VolatilityPhilipp J. Schneider et al.PDF

Loss landscapes across deep-hedging training schemes from Table 1 : (A) ERM-W , (B) \phi -W , (C) OT-W , and (D) WRAP-W
Figure 1 : Loss landscapes across deep-hedging training schemes from Table 1 : (A) ERM-W , (B) \phi -W , (C) OT-W , and (D) WRAP-W . Each surface depicts the mean hedgin…
25

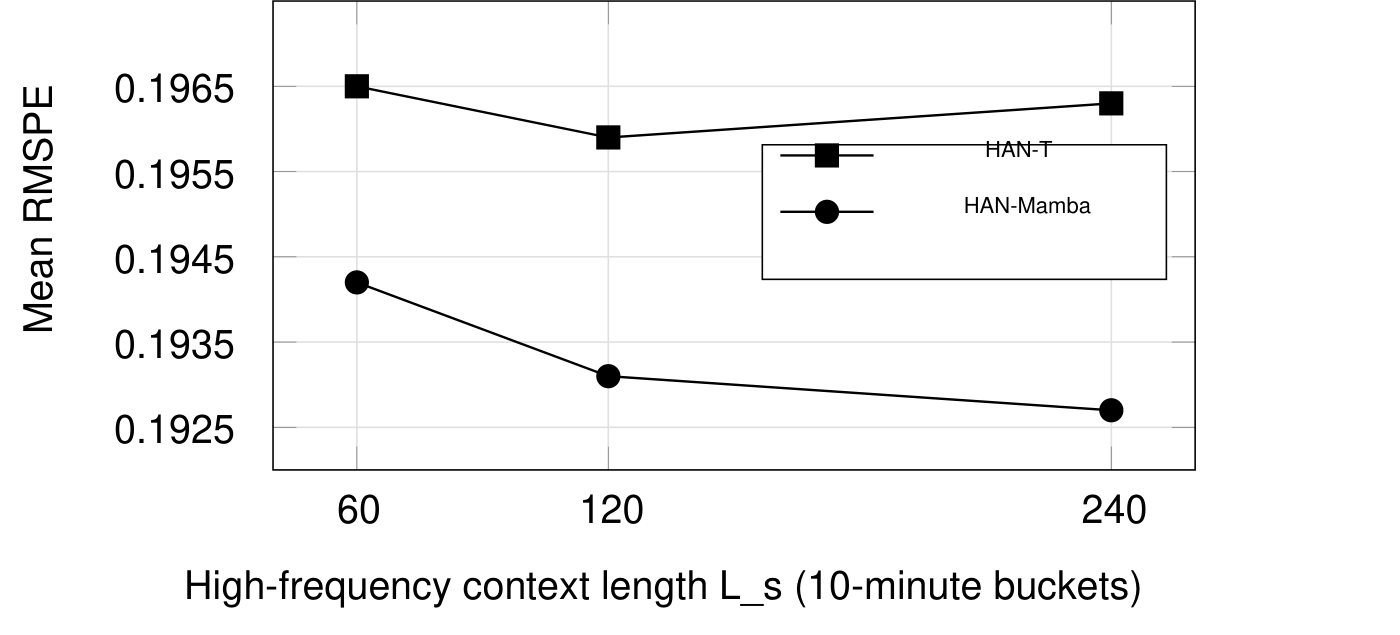
HAN-Mamba: Multi-Scale Volatility Forecasting

Replaces transformers with selective state space encoders in a hierarchical architecture for realized volatility forecasting, reducing error to 0.1927 on the Optiver benchmark with 33 percent fewer parameters than the attention variant.

Fanfare 2Derivatives & VolatilityMihai Bogdan Deaconu and Ioan Daniel PopPDF

Context-length scaling
Figure 2: Context-length scaling. The attention encoders saturate and then regress as L_{s} grows, while the selective state space encoders improve monotonically with di…

Trading, Microstructure & Execution4

08

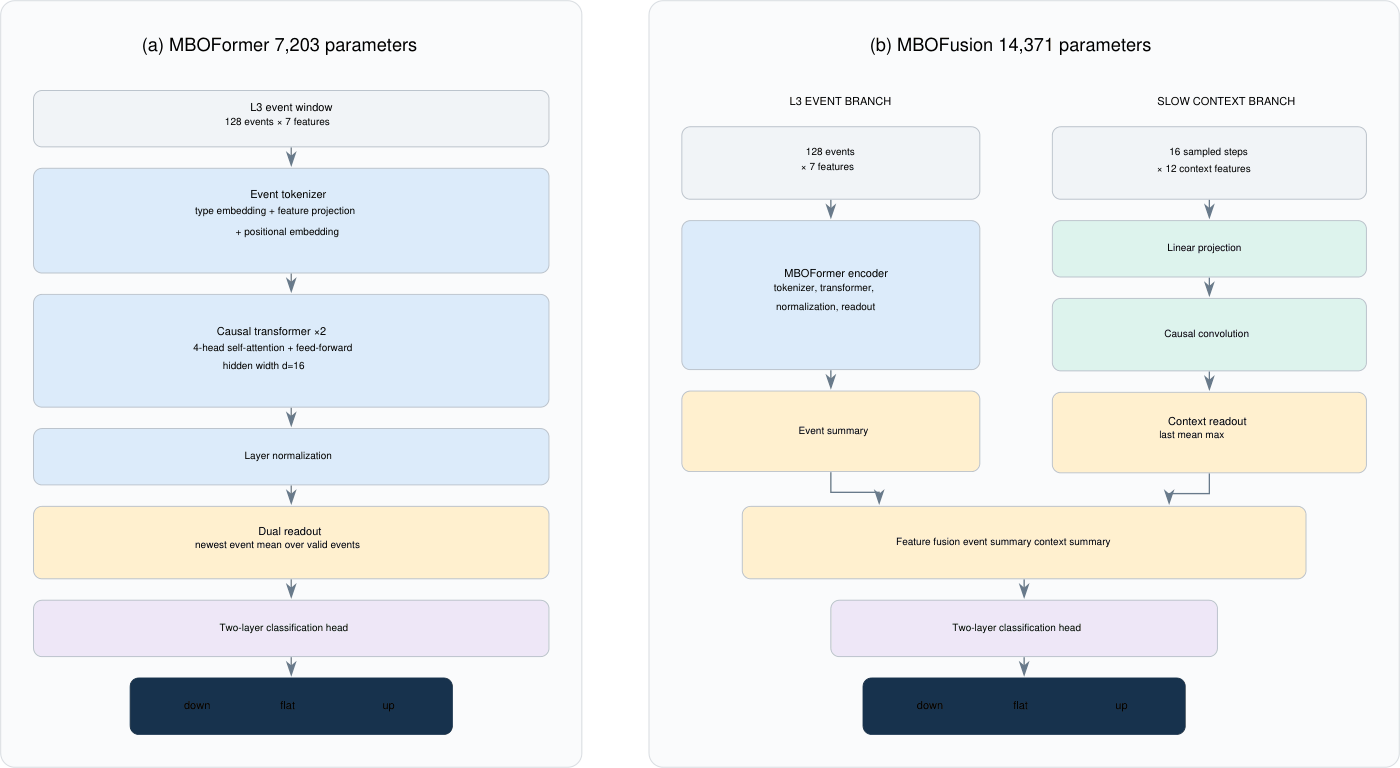
Compact Transformers for Limit Order Forecasting

MBOFormer and MBOFusion, two causal transformers with under 70 kilobyte serialized state, predict limit order book price trends with sub-millisecond latency across three markets and four prediction horizons.

Fanfare 3Trading, Microstructure & ExecutionDavid Schaurecker et al.PDF

Architectures of our two L3-based models
Figure 2: Architectures of our two L3-based models. Blue denotes event-sequence processing, green denotes the slow context branch, gold denotes aggregation or fusion, an…
16

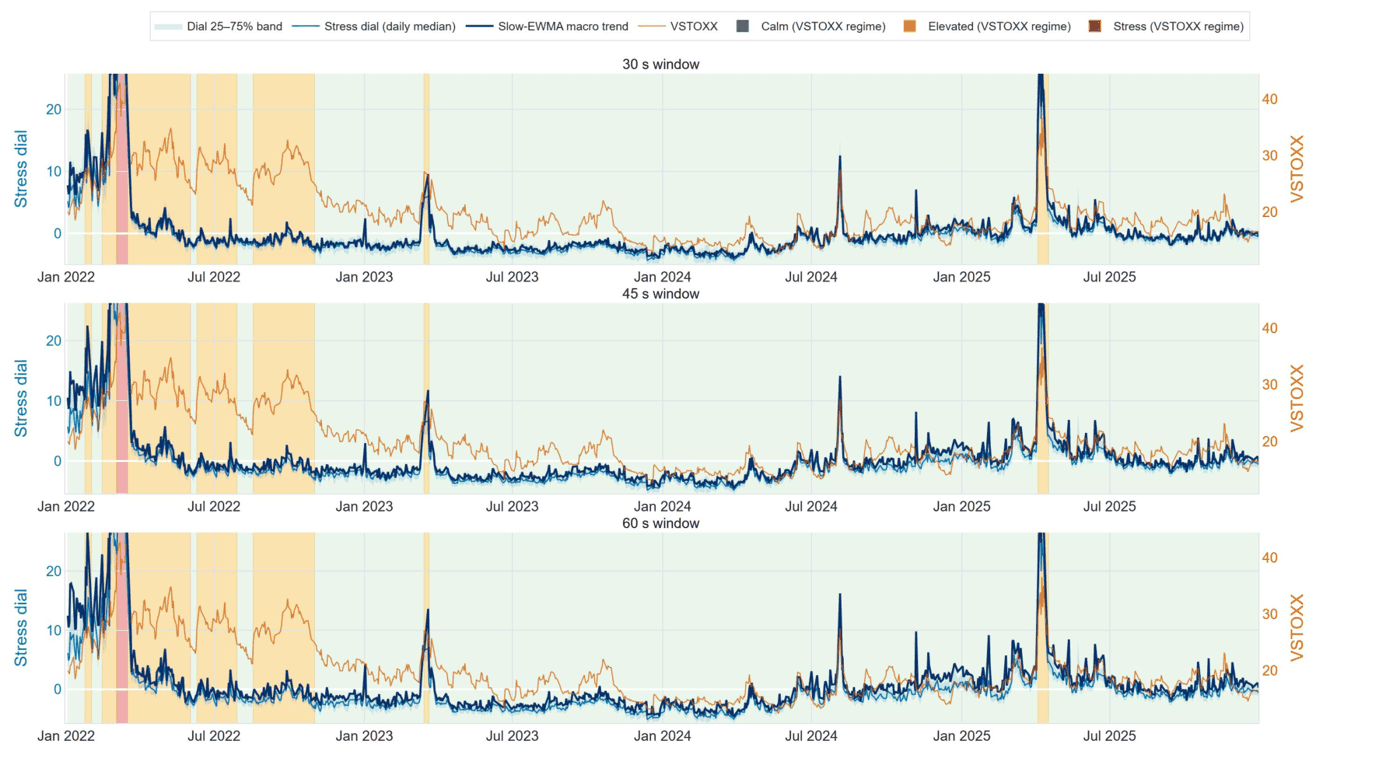
Latent Continuum of Limit Order Book Regimes

Analysis of high-frequency limit-order-book geometry finds market states form a continuous structure with a dominant latent coordinate capturing between 83.66% and 85.27% of covariance variation.

Fanfare 3Trading, Microstructure & ExecutionAnjali ThawaitPDF

Time series of stress-dial dynamics across three covariance windows, 2022-2025.
Figure 9: Continuous stress-dial dynamics across covariance durations, 2022-2025.
22

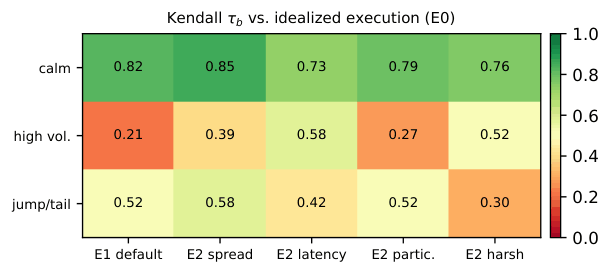
Execution Assumptions in LLM Trading Benchmarks

Varying execution realism from ideal fills to latency and impact reshuffles rankings of LLM and classical trading policies, showing how backtest conventions affect headline results.

Fanfare 3Trading, Microstructure & ExecutionWeicheng XuePDF

Kendall \tau_{b} between the E0 ranking and each stressed ranking
Figure 1. Kendall \tau_{b} between the E0 ranking and each stressed ranking. Rows are market regimes and columns are execution settings. Each cell contains 12 policies r…
28

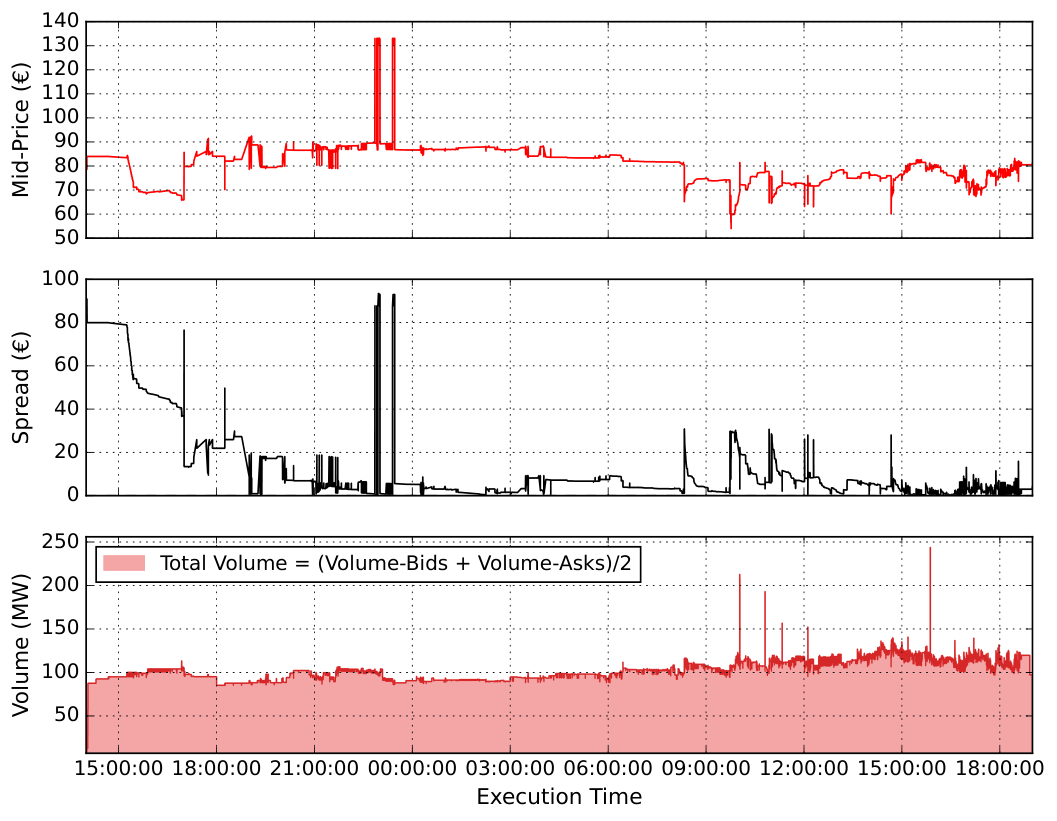
State-Dependent Hawkes Models in Electricity

A regime-switching Hawkes process models intraday electricity order flow across liquidity conditions, showing that stress mainly strengthens self-excitation rather than reshaping cross-side dynamics.

Fanfare 2Trading, Microstructure & ExecutionAyoub Jhabli et al.PDF

Intraday electricity market evolution: mid-price, bid-ask spread, and trading volume over time.
Fig. 2: Intraday evolution of the XBID market for the delivery hour 20:00–21:00 on the 16th of January 2024. The top panel shows the mid-price trajectory in euros, the m…

Portfolio & Allocation7

09

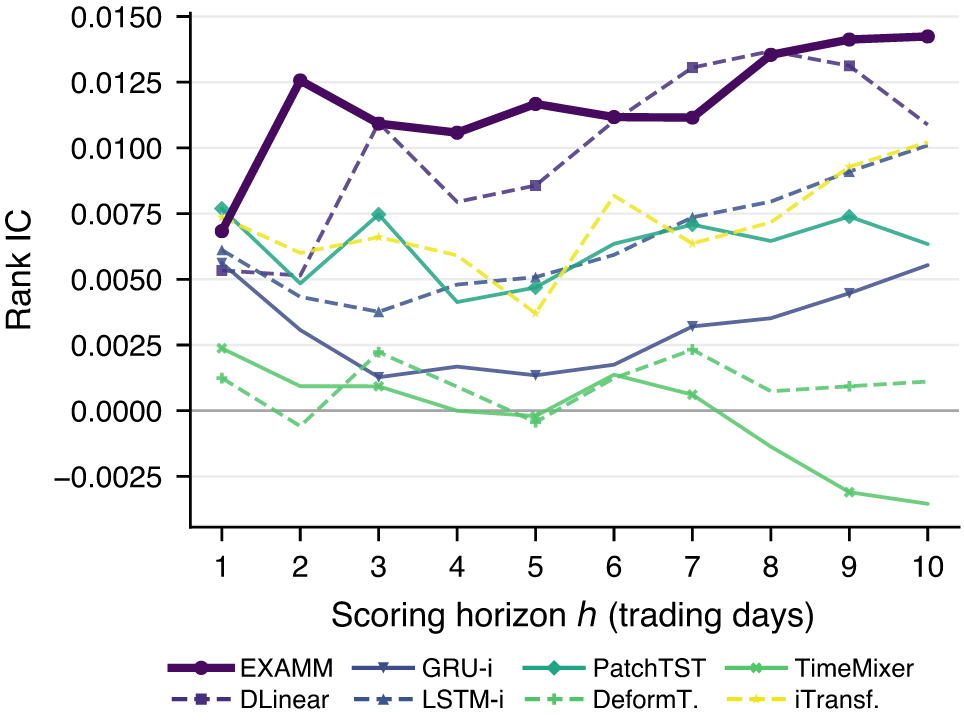
Neuroevolution for Stock Return Prediction

Tiny neuroevolved recurrent networks rank first on both forecast accuracy and daily long-short returns across four portfolios, outperforming larger transformers and proving that forecast accuracy does not guarantee trading profit.

Fanfare 3Portfolio & AllocationJonathan Chang and Zimeng LyuPDF

Rank IC as a function of scoring horizon Plot showing Rank IC as a function of scoring horizon
Figure 2. Rank IC as a function of scoring horizon Plot showing Rank IC as a function of scoring horizon.
18

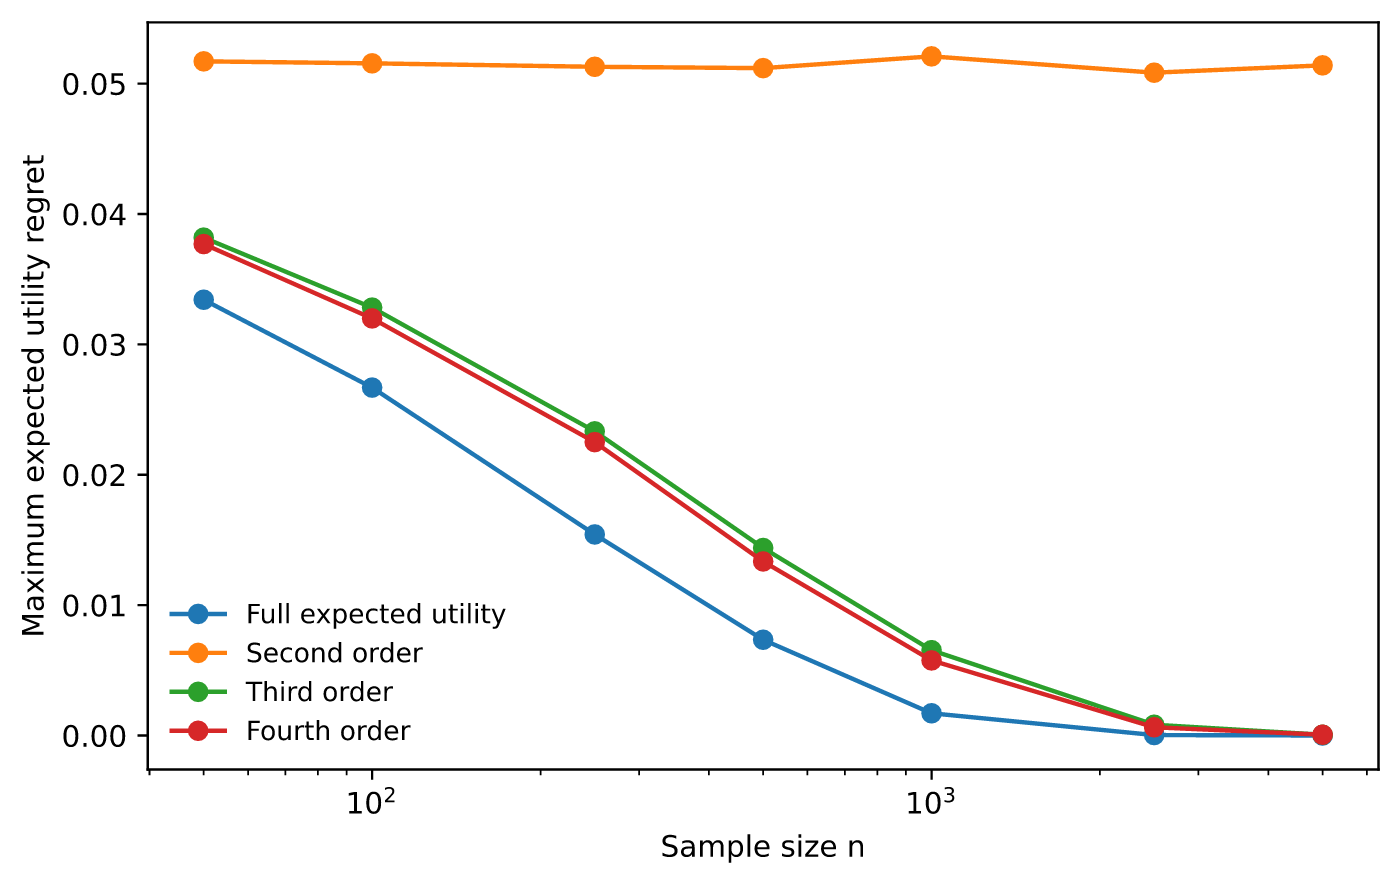
Expected Utility Regret Rule for Portfolio Choice

Proposes a portfolio rule that simultaneously selects class and estimates weights to minimize expected utility regret, attaining both minimax and Bayes lower bounds without requiring prior information.

Fanfare 3Portfolio & AllocationMasahiro KatoPDF

Moment separation: worst-case expected utility regret over the two orderings of return distributions with identical
Figure 4: Moment separation: worst-case expected utility regret over the two orderings of return distributions with identical means and second moments.
20

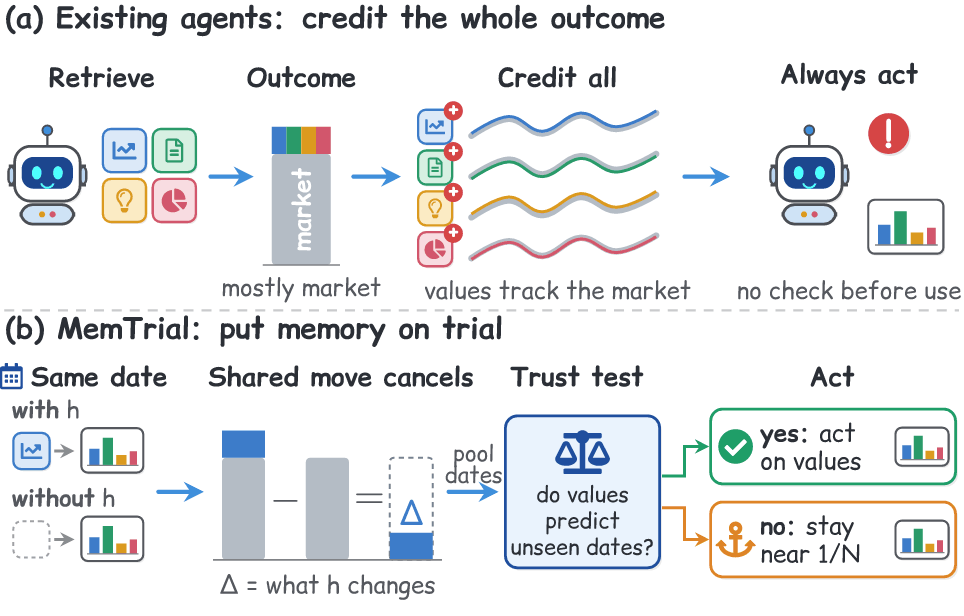
When LLM Agents Should Trust Memory

MemTrial uses factorial design to isolate what each memory contributes to portfolio decisions by crediting experiences with their marginal effect rather than shared market moves.

Fanfare 3Portfolio & AllocationGuanghao Wu et al.PDF

Comparison of existing agent approach versus MemTrial's memory trust mechanism with factorial design
Figure 1. (a) Existing agents credit experiences with market-driven outcomes and always use these credits. (b) MemTrial measures what each experience changes on the same…
23

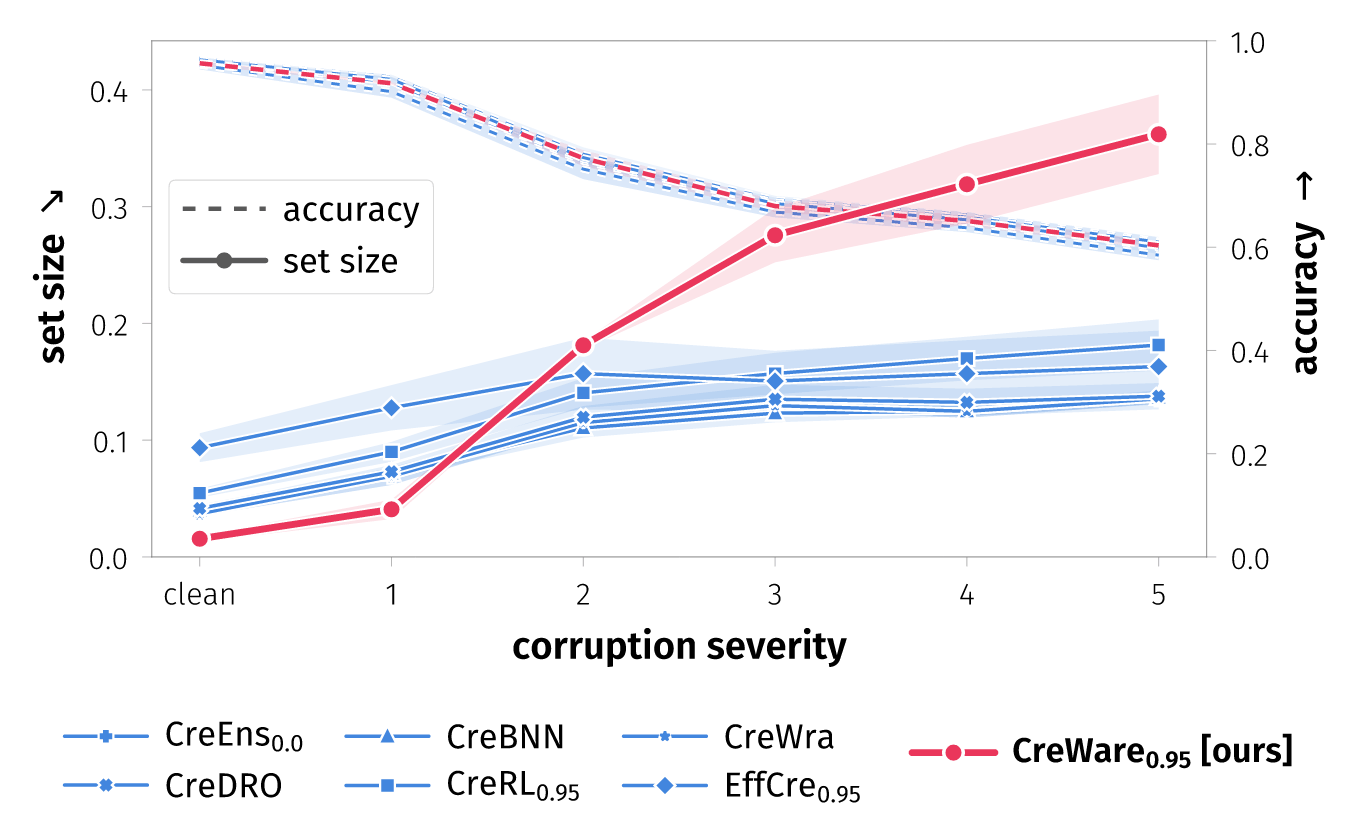
Credal Machine Learning for Risk-Averse Decisions

A method represents epistemic uncertainty with credal sets and combines them with a decision rule that avoids catastrophic predictions under conditional value-at-risk minimization.

Fanfare 3Portfolio & AllocationTimo Löhr et al.PDF

Set size and accuracy versus corruption severity, showing CreWare adapting set size with degraded accuracy.
Figure 2: Distribution shift on BloodMNIST. Set size and accuracy against shift severity, mean and standard deviation over three seeds. CreWare’s sets grow as accuracy d…
24

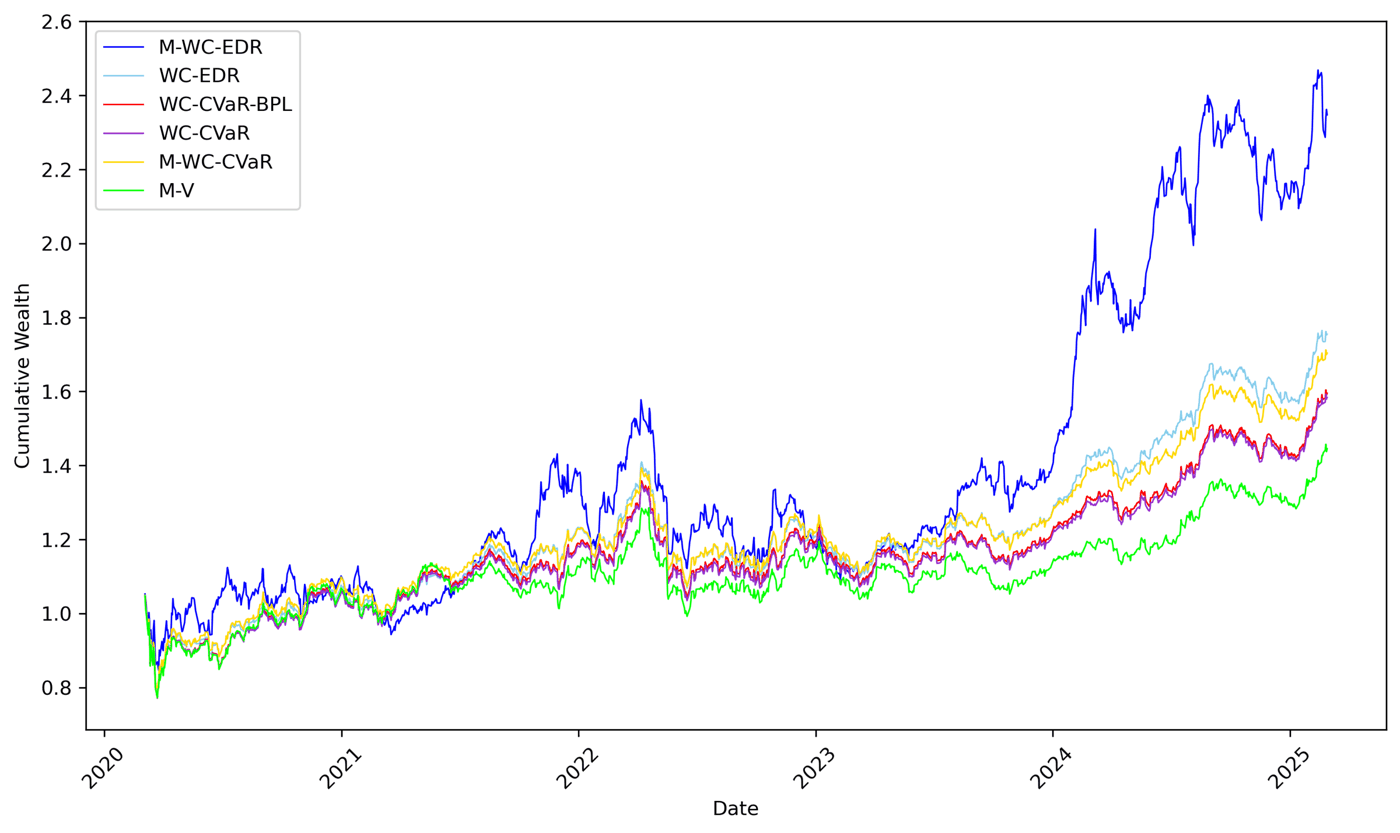
Robust CVaR Portfolio Selection with Penalties

Derives a closed-form expression for worst-case conditional value-at-risk under reward-penalty mechanisms and distribution uncertainty, enabling optimal portfolio allocations that balance losses with downside risk.

Fanfare 2Portfolio & AllocationJun Cai et al.PDF

Cumulative wealth comparison of six portfolio models from 2010-2025 with clear legend and time series.
Figure 1 : Cumulative wealth and worst-case CVaRs of portfolios based on the M-WC-EDR, WC-EDR, WC-CVaR-BPL, WC-CVaR, M-WC-CVaR, and M-V models, with r_{0}=0.0003 , \alph…
29

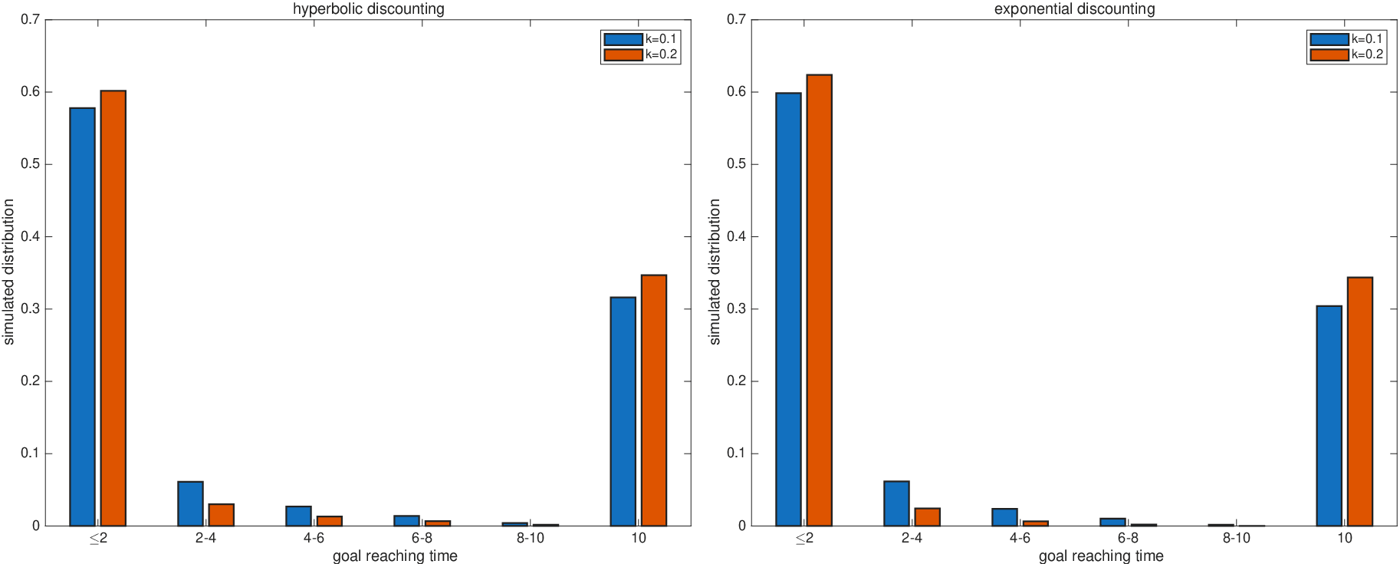
Stochastic Control for Goal-Based Investing

A framework characterizes optimal investment policies for reaching financial goals by deadline, revealing that policies can decrease in asset drift and need not converge to risk-free allocation.

Fanfare 2Portfolio & AllocationGechun Liang et al.PDF

Goal reaching time distributions comparing hyperbolic and exponential discounting with different parameters
图 4: Simulated distribution of the goal reaching time under different specifications. The category 10 denotes paths on which the goal is not reached before the terminal…
30

Robust Enhanced Index Tracking Under Uncertainty

Robust optimization models minimize worst-case loss and downside risk for enhanced indexing under distributional uncertainty, beating benchmarks and standard robust approaches in out-of-sample wealth.

Fanfare 2Portfolio & AllocationJun Cai and Zhiqiao SongPDF

Cumulative wealth and Sharpe ratios of portfolios based on the M-ER, M-TSV, and M-V models under the uncertainty set
Figure 2 : Cumulative wealth and Sharpe ratios of portfolios based on the M-ER, M-TSV, and M-V models under the uncertainty set {\cal M}_{n+1}(\bm{\mu},\bm{\Sigma}) , wi…

Also notable1

26

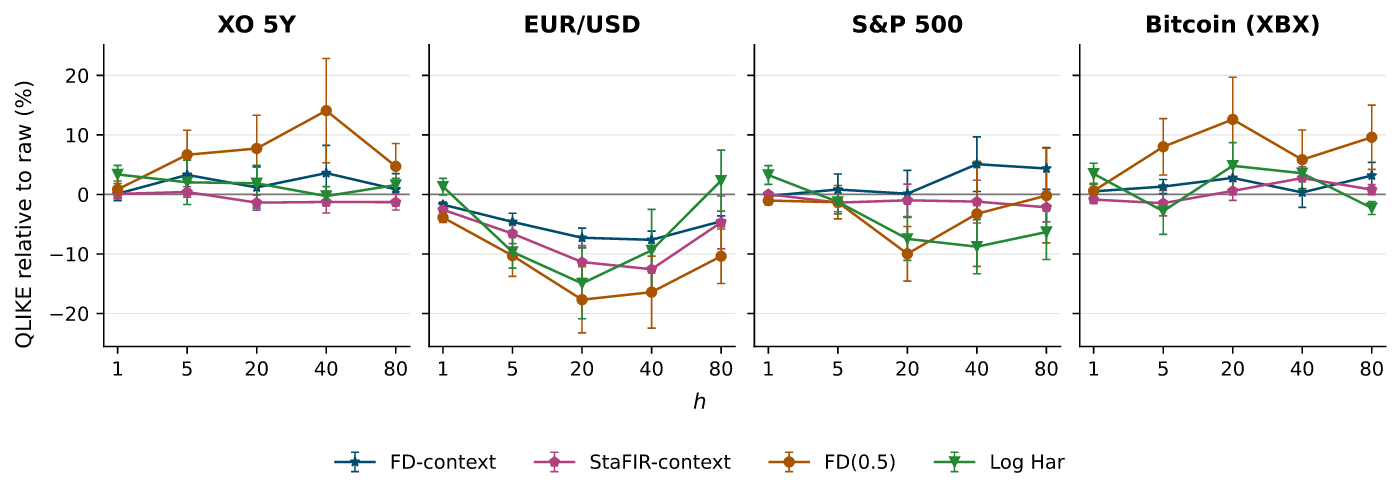
StaFIR: Learned Stationarity-Aware Filters

A convex method learns causal filters that balance stationarity and input preservation for financial time series, adapting filtering strength to persistence while preserving signal similarity.

Fanfare 2Econometrics & ForecastingLorena Egger and Mathis LingerPDF

Per-series forecast performance on the log five-day realized-variance series
Figure 5 : Per-series forecast performance on the log five-day realized-variance series. At each forecast horizon h , points report QLIKE relative to raw , in percent. W…

SSRN

New working papers in finance, economics and ML

30 papers

Portfolio & Allocation3

01

Quantitative Equity Evolution: Constraints and Alpha Decay

Surveys fifty years of quantitative investing as a history of changing implementation boundaries from diversification through machine learning, emphasizing alpha decay and the gap between research and production systems.

Fanfare 4Portfolio & AllocationXuan Feng et al.

06

Volatility Targeting Over a Century

Analyzing 100 years of daily data, the study finds volatility scaling harmed returns before 1985 but improved them after, a shift attributed to derivatives markets and deregulation, with walk-forward Sharpe ratio of 1.01.

Fanfare 4Portfolio & AllocationSparsh Patel

07

Multi-Strategy Quantitative Portfolio

Eleven systematic strategies across equities, futures, and currencies achieve a 1.91 Sharpe ratio net of costs from January 2012 to June 2026, with 23.6% compound annual return.

Fanfare 4Portfolio & AllocationOliver Navarro

ML & AI Methods6

02

LLM Factor Discovery and Evidence Scarcity

An autonomous agent evolved 940 factors over 17 days and finds that reusing backtest data inflates edge by a quarter to a third and in-sample improvement predicts worse performance.

Fanfare 4ML & AI MethodsKamer Ali Yuksel

04

Firm-Level AI Exposure Predicts Returns Post-Launch

A natural-language analysis of 13,757 firms finds AI exposure surged after ChatGPT and predicts 1.37 percent higher annual returns, though the effect is concentrated after the launch and driven by firm-specific factors.

Fanfare 4ML & AI MethodsSakshi Basu et al.

12

LLM Agents Build Auditable Equity Alpha Models

An autonomous research loop in which agents propose factor candidates and code verifies them builds multi-factor alpha models, screening 212 predictors and admitting 14 that raise baseline information coefficient out-of-sample.

Fanfare 3ML & AI MethodsErfan Sadeghi

13

White-Box Alpha Mining with Quality-Control Loops

GFlowAlpha uses neuro-symbolic search and internalizes econometric quality control as online rewards to mine white-box factors, delivering mean out-of-sample daily ICIR of 0.485 with Fama-MacBeth t-statistics of 4.99 on Chinese stocks.

Fanfare 3ML & AI MethodsHongwei Yue et al.

14

Deflated Sharpe Ratios Fail Under Adaptive Search

The research proves that query-counted Deflated Sharpe Ratios certify noise in adaptive research and proposes sealed-holdout verification, where validity depends on bits revealed rather than strategy count.

Fanfare 3ML & AI MethodsShlok Singh Sobti

28

Hybrid Graph Neural Network for RV Forecasting

A graph neural network combining temporal and cross-asset volatility patterns reduces mean squared error and quasi-likelihood loss by approximately 9.9% and 3.4% on Dow stocks.

Fanfare 3ML & AI MethodsJongu Lee et al.

Asset Pricing & Factors5

03

Fed Surprises: Rate-Path, Information, and Tone

The study decomposes Federal Reserve announcements into three orthogonal shocks and traces each through the equity cross-section, finding rate-path surprises dominate while standard balance-sheet characteristics carry no additional power beyond beta and size.

Fanfare 4Asset Pricing & FactorsPablo De Diego Leguina

08

Demographics, Debt, and Equity Risk Premia

A two-country model attributes 251 basis points of U.S. equity premium gains and 71 basis points of global rate decline since 1980 to demographic aging.

Fanfare 4Asset Pricing & FactorsChristopher Hyland and Tim Willems

10

Cross-Sectional Risk and Corporate Bond Returns

Constructs a characteristics-based systematic risk measure using rate jumps that predicts out-of-sample corporate bond returns, with high-minus-low decile portfolio earning 9.12% annually and 7.80% alpha.

Fanfare 3Asset Pricing & FactorsYongfu Feng et al.

11

The Price of Conviction in Asset Markets

The study shows that high-conviction beliefs exert outsized influence on prices, with a long-short portfolio exploiting conviction-weighted disagreement earning 13.2 percent annualized six-factor alpha.

Fanfare 3Asset Pricing & FactorsChristian Goulding et al.

20

AI Exposure and Financial Stability Risk

The study measures AI exposure across 284 U.S. firms and finds that an AI-factor explains only 18% variance alongside conventional factors, suggesting AI is a distinct cross-industry risk lens separate from traditional spillovers.

Fanfare 3Asset Pricing & FactorsVamsidhar Ambatipudi

Macro-Finance & Rates4

05

Monetary Policy Risk and Asset Prices

Asset prices respond to monetary policy uncertainty around FOMC announcements; a New Keynesian model shows policy risk accounts for much of equity and inflation-bond risk premia and weakens activity when elevated.

Fanfare 4Macro-Finance & RatesCorey Feldman and Thomas King

22

Exchange Rate Regimes and Term Premium Spillovers

U.S. monetary tightening raises term premia sharply in pegged economies but not floating ones; a DSGE model shows pegs force adjustment through domestic rates, tightening leverage constraints and amplifying spillovers.

Fanfare 3Macro-Finance & RatesPawan Gopalakrishnan and Ankit Kumar

23

Geopolitical Skewness Risk and Bond Premia

A measure of cross-country geopolitical risk skewness predicts U.S. Treasury risk premia out-of-sample and forecasts weaker activity, adding incremental value beyond yield curves and standard macroeconomic predictors.

Fanfare 3Macro-Finance & RatesFuwei Jiang et al.

29

Expectations and Monetary Policy Transmission

Optimal rate-setting creates time-inconsistency: market expectations become too sensitive to policy surprises, amplifying real effects of central bank forecast errors; less aggressive rules cut output volatility.

Fanfare 3Macro-Finance & RatesVicente Jimenez-Gimpel and Tomás Caravello

Trading, Microstructure & Execution2

09

Pre-registered Testing of Trading Signals

Applies a strict pre-registered protocol to eleven trading signals across equity and futures markets, finding only trend survives development and hold-out periods with borderline significance after multiple-testing adjustment.

Fanfare 3Trading, Microstructure & ExecutionYasanji Ratnaike

30

Anomalies in Indian Equities and Real Costs

Well-documented Indian equity anomalies replicate strongly in-sample but all fail to survive 12 to 32 basis point retail transaction costs; required directional accuracy reaches 72% at hourly horizons.

Fanfare 3Trading, Microstructure & ExecutionKarthikeya Voocha

Derivatives & Volatility2

15

Long-Horizon Credit Spreads Test Pricing Kernels

The study shows that Baa-Aaa spreads at 27-year maturity test pricing kernels better than shorter maturities, with a structural refinancing model matching observed spreads while prior kernels overpredict by 27 to 68 basis points.

Fanfare 3Derivatives & VolatilitySöhnke M. Bartram et al.

27

Delta-Guided RL for Derivative Hedging

A reinforcement learning method embedding Black-Scholes delta guidance cuts hedging error by 19-38% across simulated and real options data with robust statistical significance.

Fanfare 3Derivatives & VolatilitySparsh Patel

LLMs & Text2

16

LLMs Reduce Information Frictions in Bonds

Shows that large-language-model scores of default risk from earnings calls predict bond rating migration one year ahead where analysts disagreed, capturing information not yet priced in spreads.

Fanfare 2LLMs & TextMoazzam Khoja

24

Geoeconomic Fear and Sovereign Spreads

The study constructs a geoeconomic fear index from news articles and finds that higher fear predicts wider emerging-market sovereign spreads, especially for speculative-grade issuers.

Fanfare 3LLMs & TextHui Ding et al.

Crypto & DeFi3

17

DeFi Token Revenue Surprises Predict Short-Term Returns

Revenue surprises on 95 DeFi protocols predict abnormal token returns, with one-standard-deviation surprises associated with 28.8 basis points higher returns over three days when tokens have direct revenue claims.

Fanfare 3Crypto & DeFiSimon Harre et al.

18

Machine Learning Predicts Cryptocurrency Contagion

The study forecasts time-varying return spillovers among cryptocurrencies using machine learning, finding monetary policy and funding rates drive connectedness and classifying events that shift spillover composition into contagion types.

Fanfare 3Crypto & DeFiEric Osmer et al.

19

Bitcoin ETFs Tighten Spillovers from Equities

The research shows that after U.S. Bitcoin ETF approval in January 2024, return and volatility linkages between Bitcoin and equities strengthened substantially, with volatility spillovers becoming markedly asymmetric from stocks to crypto.

Fanfare 3Crypto & DeFiYat Ming Eddie Lam

Risk, Credit & Banking2

21

Causal Uplift Modeling for Credit Restructuring

A causal framework compares six estimators of treatment effect to optimally assign debt restructuring interventions, revealing that targeting borrowers by predicted effect generates substantially positive value where blanket treatment fails.

Fanfare 3Risk, Credit & BankingAntonio Aguilera Gonzalez

26

Common Banks Limit Supply-Chain Shocks

Using Portuguese wildfire data, the research finds firms whose banks also lend to suppliers experience 10 percentage points smaller credit declines and face attenuated real losses.

Fanfare 3Risk, Credit & BankingMiguel Almeida Ferreira and Antonio R. dos Santos

Also notable1

25

Debt Maturity and Corporate Investment

A global study of 357,630 firm-years shows firms with more short-term debt cut capital expenditure by 2.156 percentage points, mainly due to refinancing availability constraints.

Fanfare 3Corporate FinanceMirza Muhammad Naseer et al.

RePEc

Working papers curated by RePEc's NEP field reports

30 papers · 22 figures

Asset Pricing & Factors4

01

Risk Appetite and Monetary Transmission

The research shows Fed policy affects risk asset prices primarily through risk appetite shifts, not interest rates; transmission via risk appetite dwarfs rate-channel effects.

Fanfare 4Asset Pricing & FactorsMichael D. Bauer et al.PDF

Rolling regression of RISK on MPS
Figure 4. Rolling regression of RISK on MPS
08

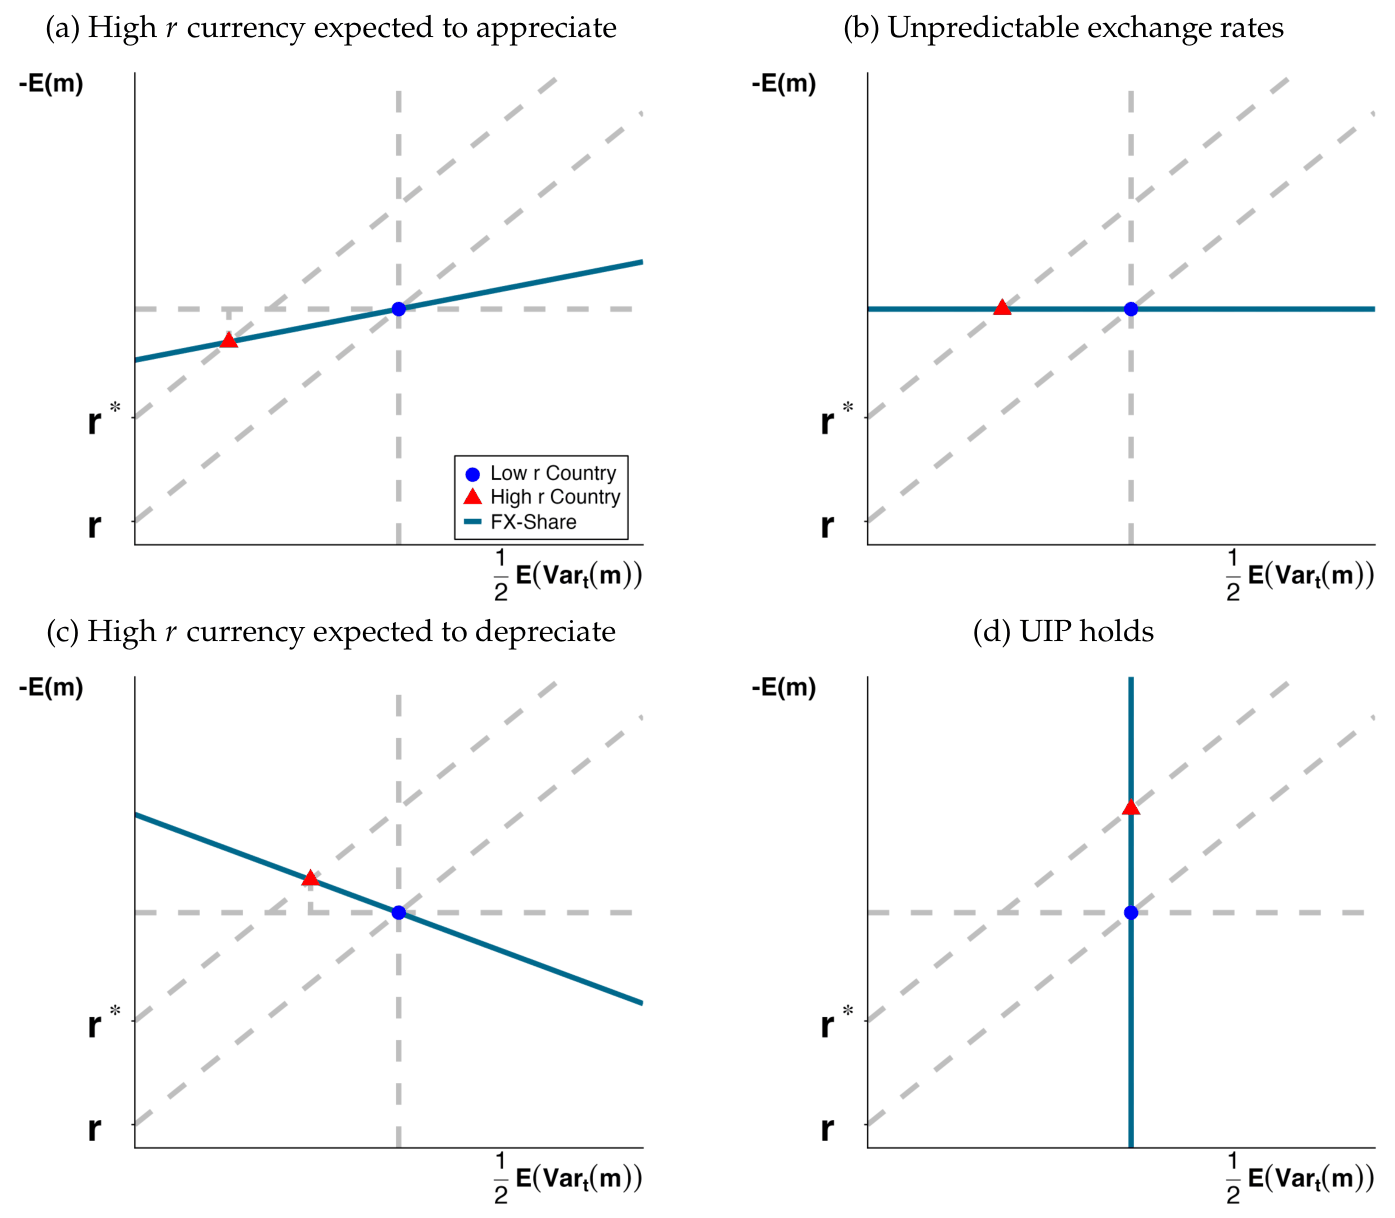
A Currency Premium Puzzle

The paper proves that asset pricing models solving equity and risk-free rate puzzles fail to generate observed interest-rate differentials between risky and safe currencies.

Fanfare 3Asset Pricing & FactorsTarek Alexander Hassan et al.PDF

Currency Premium in SDF Space
Figure 2: Currency Premium in SDF Space
09

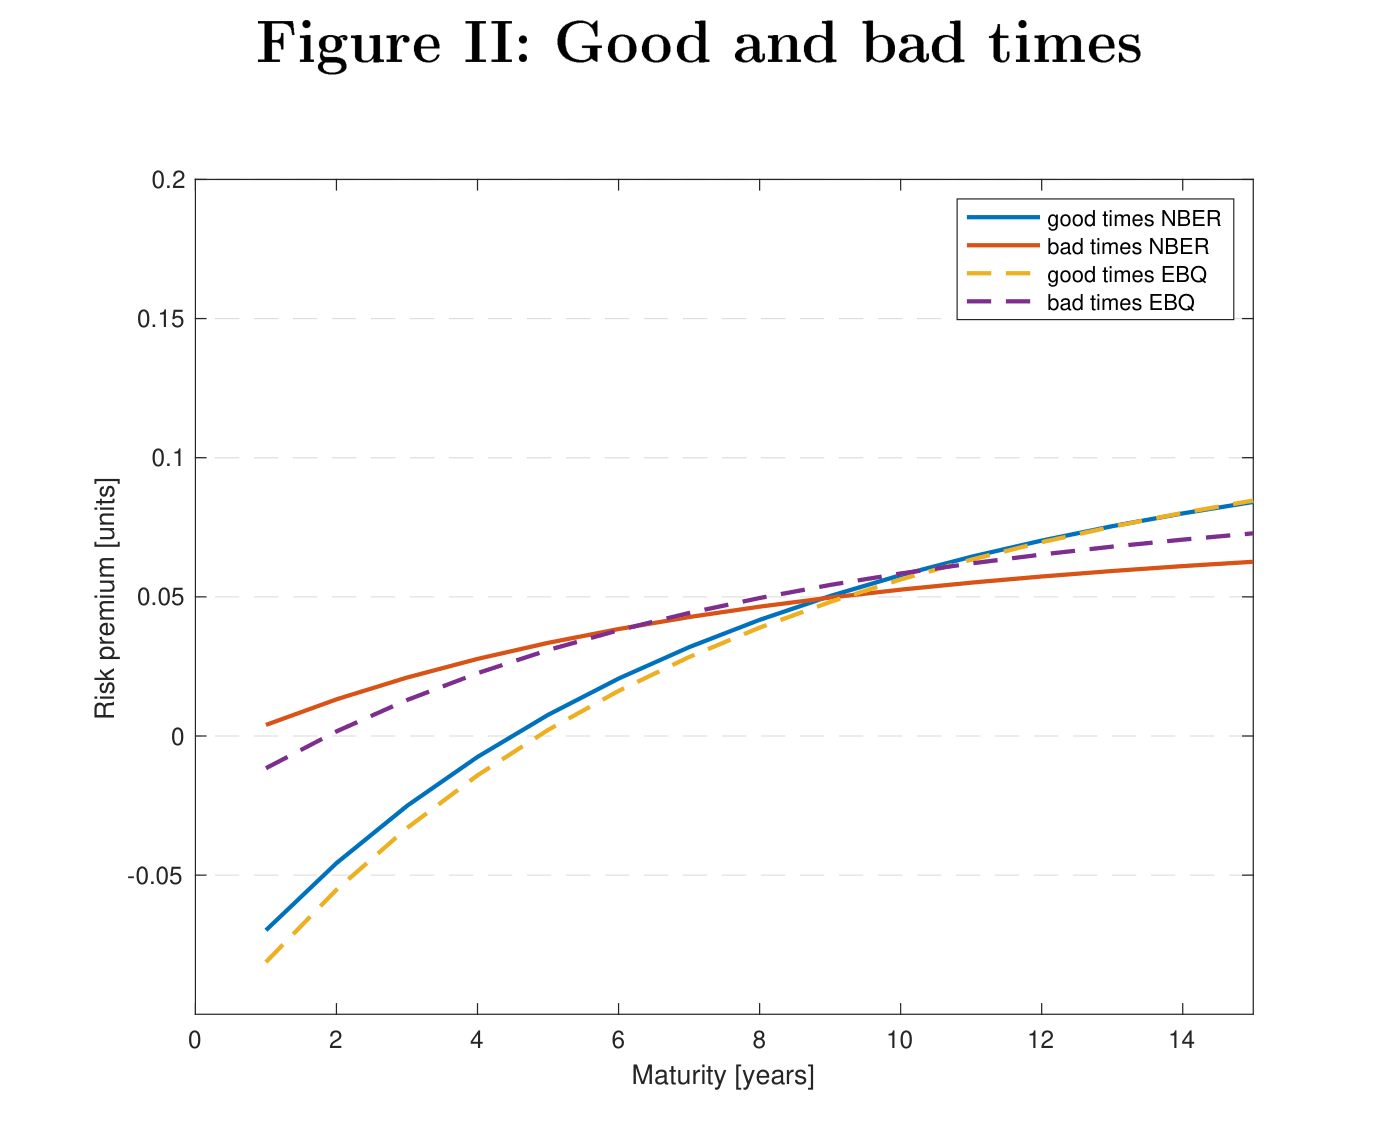
The Implied Equity Term Structure

Inferring expected returns from stock prices and cash flows reveals an upward-sloping equity term structure, but value and speculative-grade firms show flat or downward slopes.

Fanfare 3Asset Pricing & FactorsLieven Baele et al.PDF

Implied equity term structure showing return premia across maturity horizons in good and bad times.
12

Global Firms and Capital Allocation

A quantified general-equilibrium model of 23,000 firms across 48 countries shows financial and trade liberalization concentrate activity in largest firms with larger gains for emerging economies.

Fanfare 3Asset Pricing & FactorsLoukas Karabarbounis et al.PDF

Macro-Finance & Rates8

02

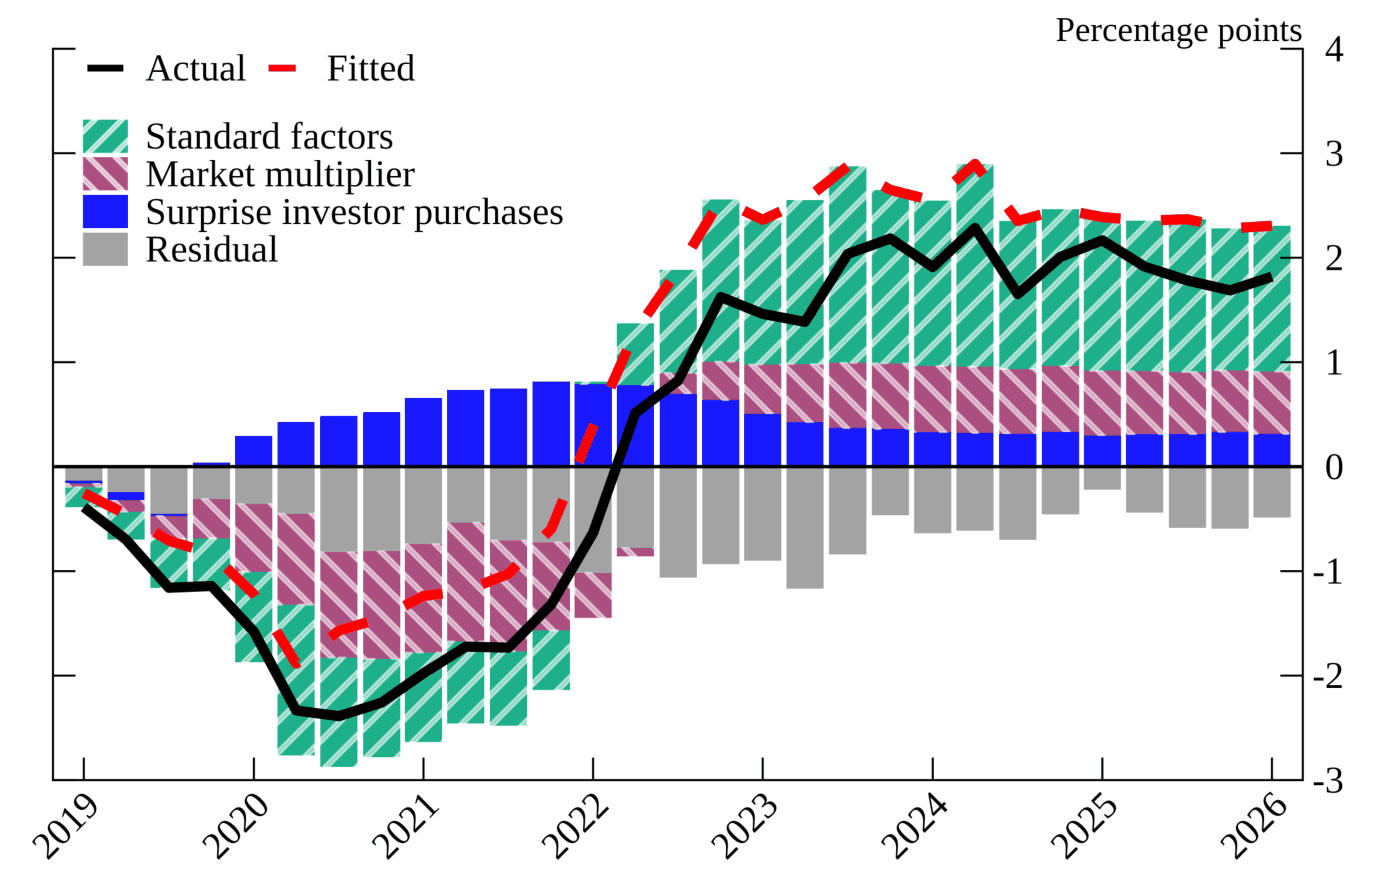
Treasury Yield Effects of Supply Demand

A demand-system framework quantifies that $100 billion in Treasury supply raises five-year yields by roughly 3 basis points, with effects driven by changing foreign and hedge-fund participation.

Fanfare 3Macro-Finance & RatesDaniel O. Beltran and Canlin LiPDF

Stacked area chart decomposing five-year yield changes into standard factors, market multiplier, and investor purchases
Figure 11. Decomposition of Cumulative Changes in Five-Year Yield
03

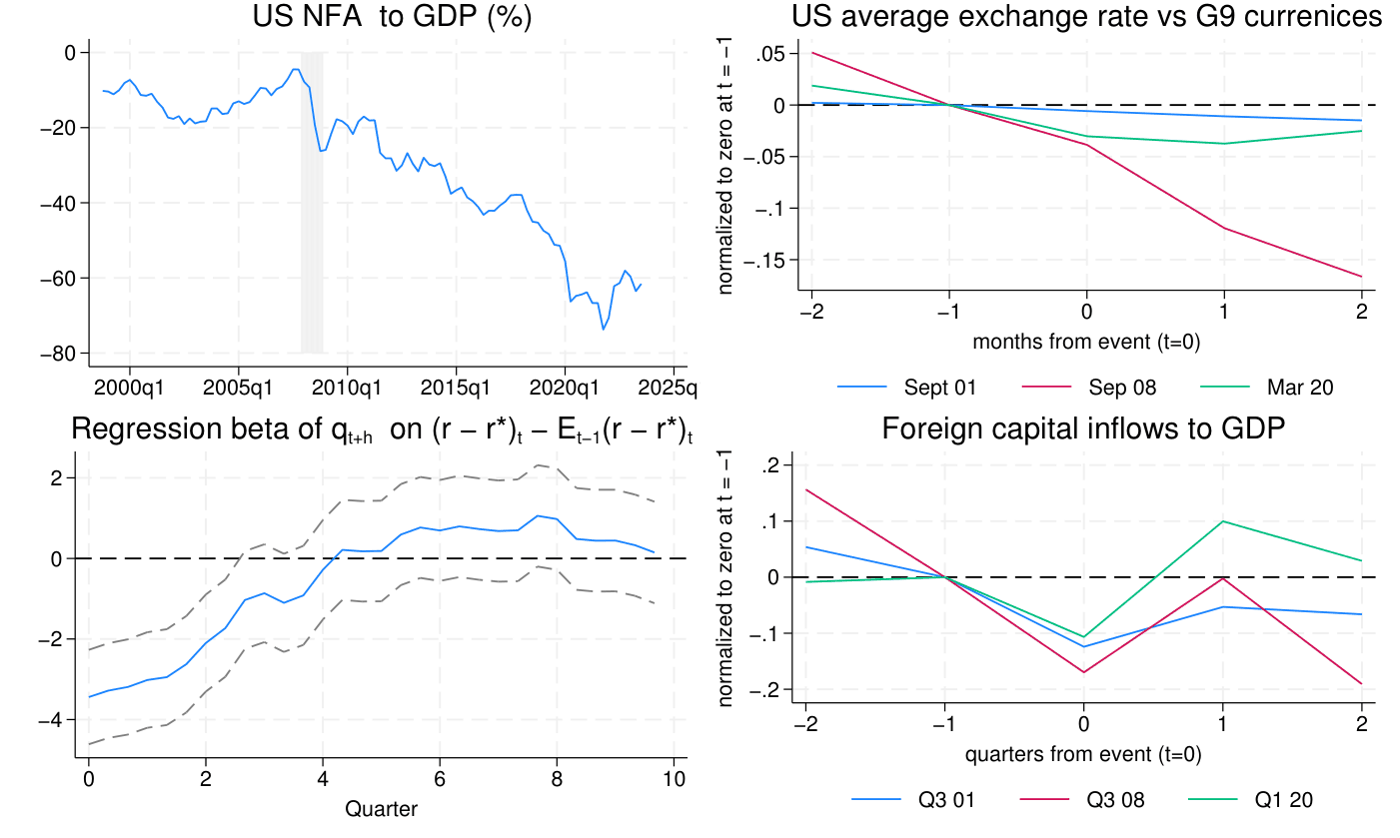
Dollar Collateral and Global Capital Flows

A model shows U.S. Treasury collateral advantage drives dollar appreciation during stress and reconciles exorbitant privilege, financial intermediation, and convenience yield perspectives.

Fanfare 3Macro-Finance & RatesMichael B. Devereux et al.PDF

US external dynamics during crises: NFA trends, exchange rates, capital inflows, and regression relationships.
Figure 1: US external dynamics during crises
04

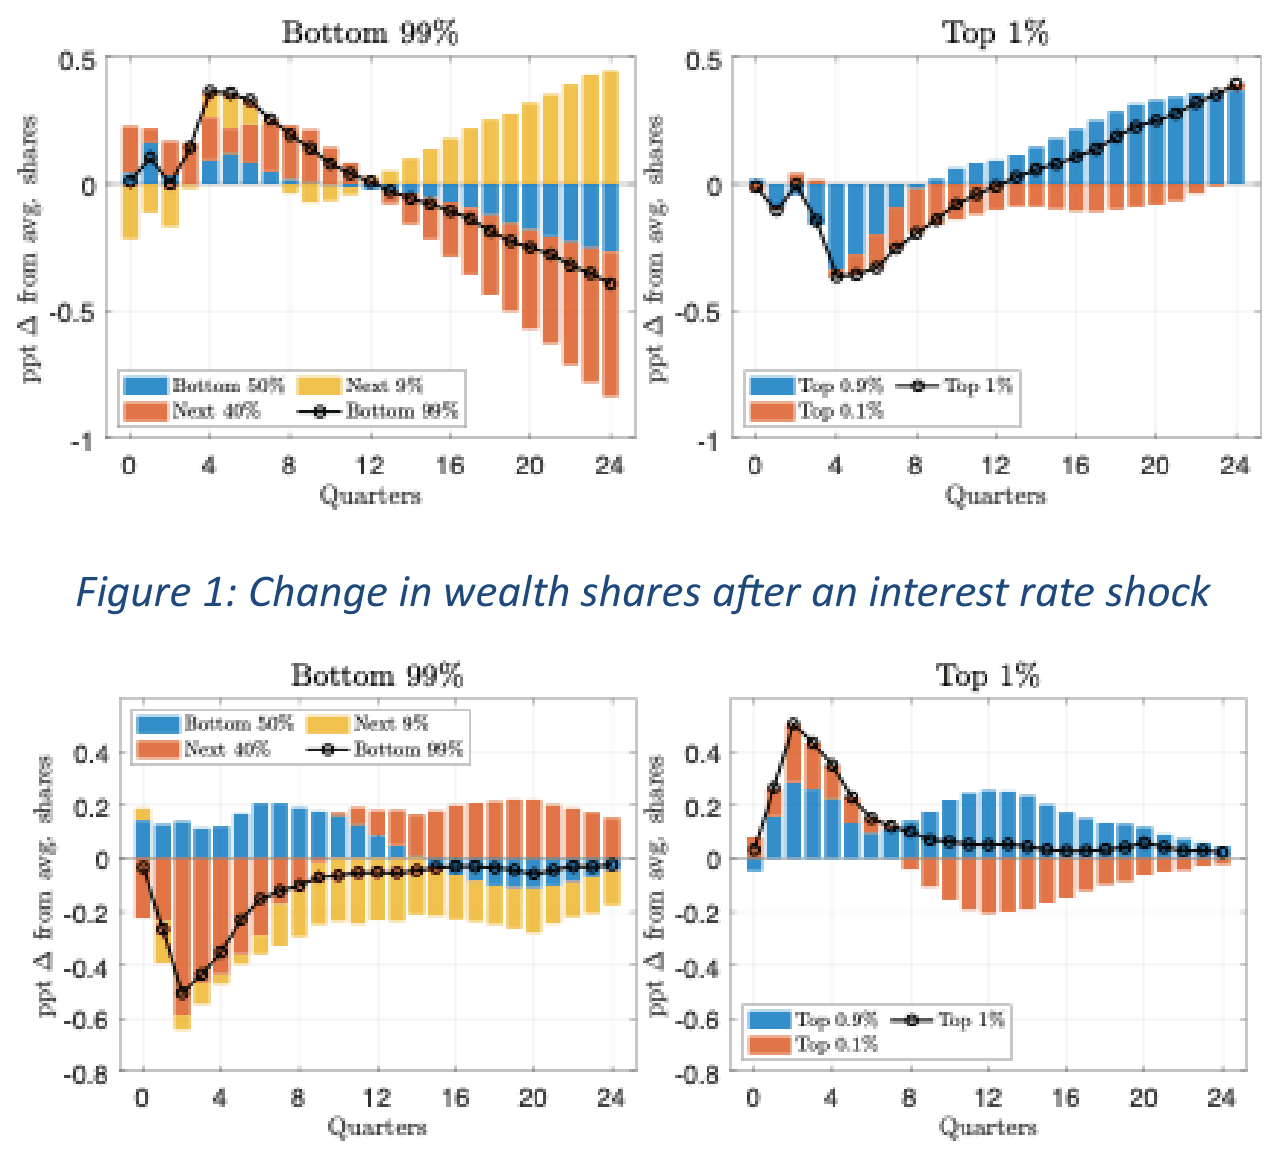
Monetary Policy and Wealth Distribution

Rate cuts initially reduce wealth inequality but increase it medium-term; housing drives effects at the bottom while equities drive them at the top.

Fanfare 3Macro-Finance & RatesAlessandro Franconi and Giacomo RellaPDF

Wealth share changes across distribution after interest rate shock over time
Figure 1: Change in wealth shares after an interest rate shock
19

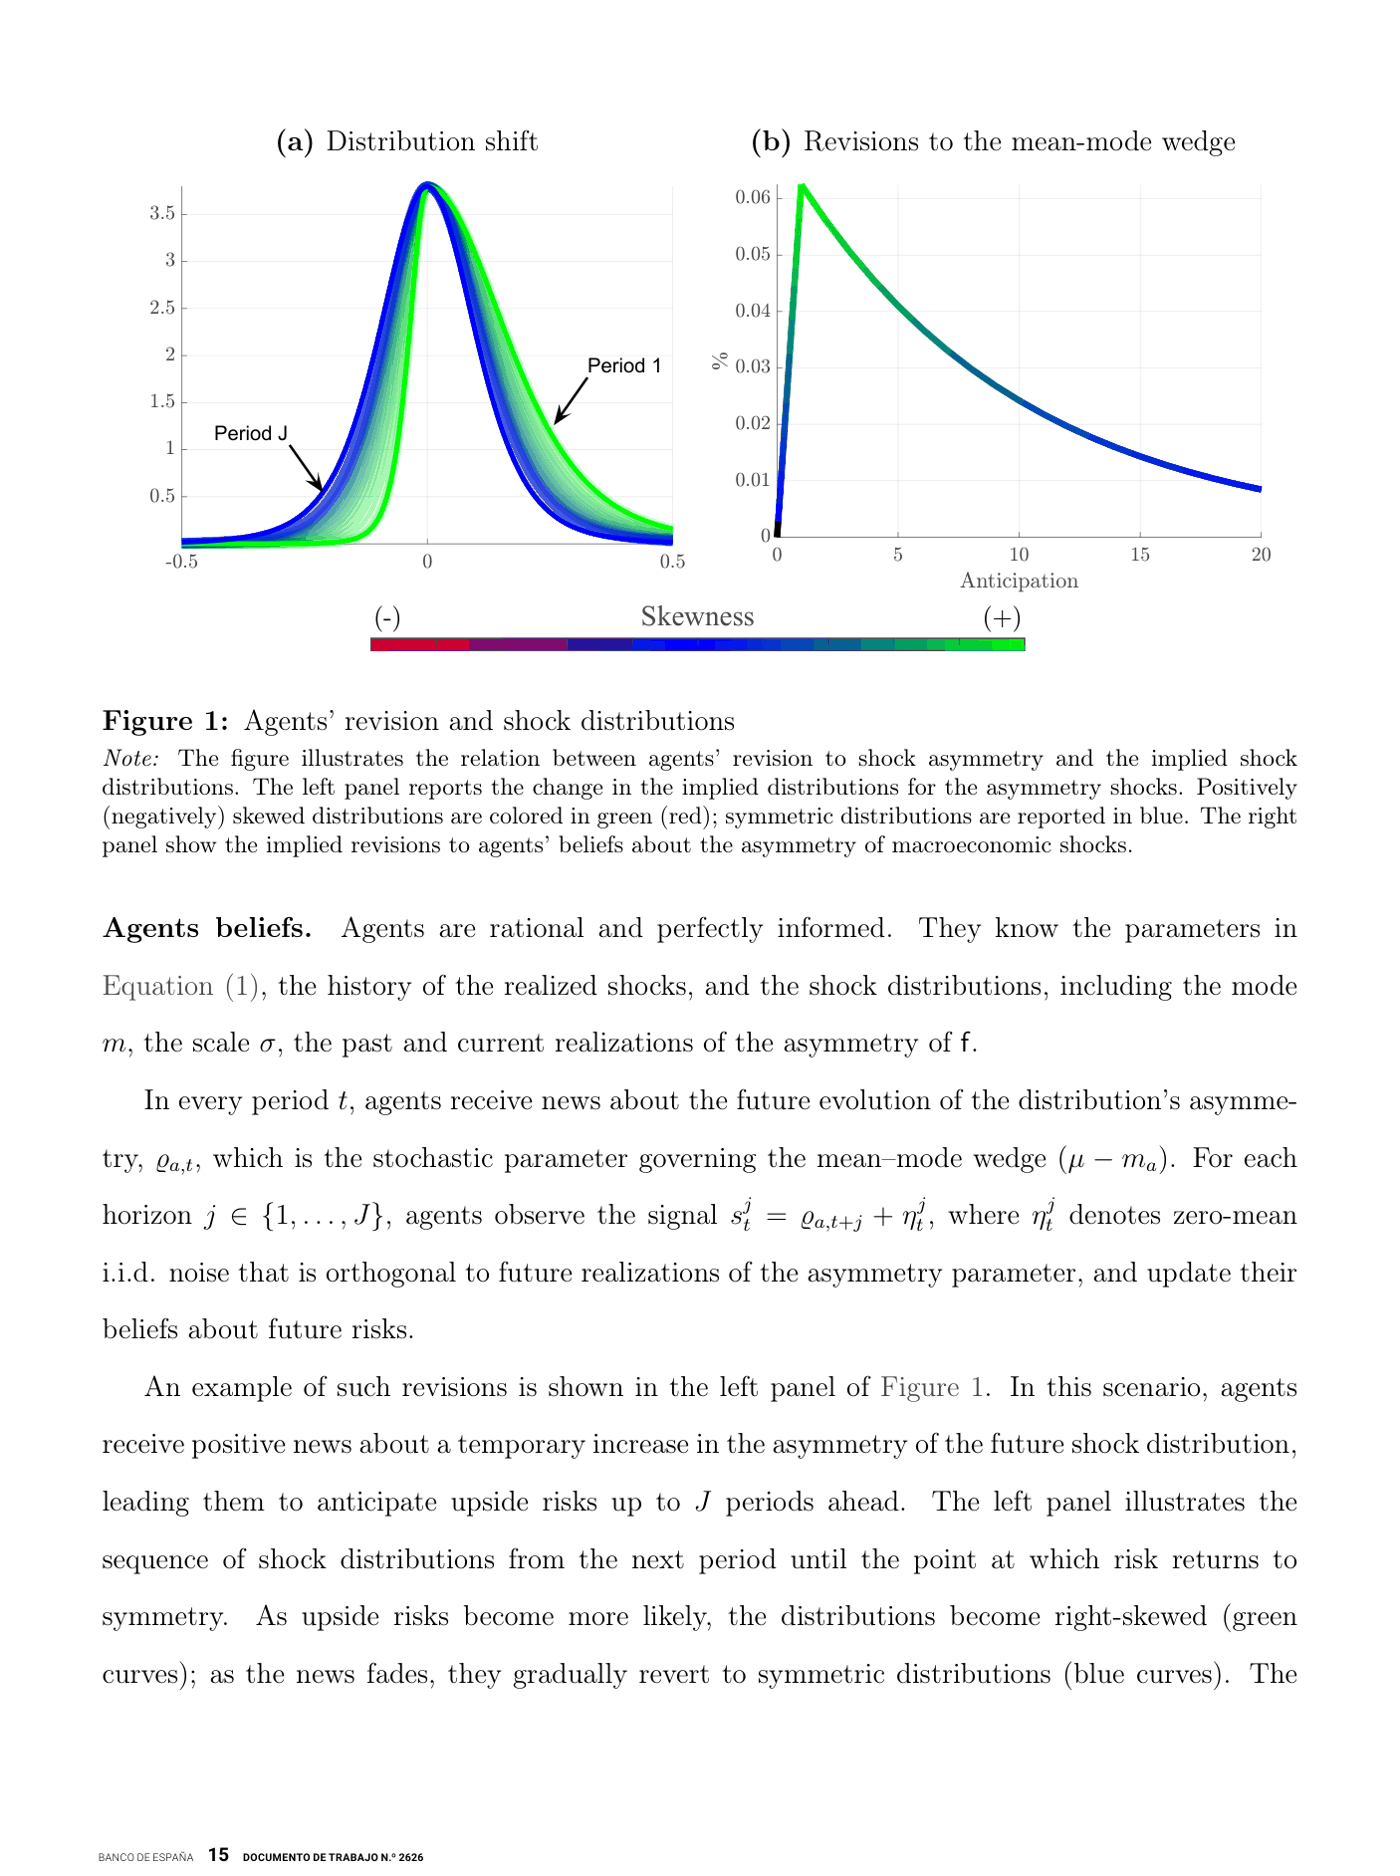
Asymmetric Inflation Risk and Monetary Policy

A model with time-varying skewness in cost-push shocks generates persistent stagflationary effects; optimal policy leans against the balance of inflation risks.

Fanfare 2Macro-Finance & RatesAndrea De Polis et al.PDF

Distribution shifts and responses to one-month shocks with asymmetric skewness distributions
20

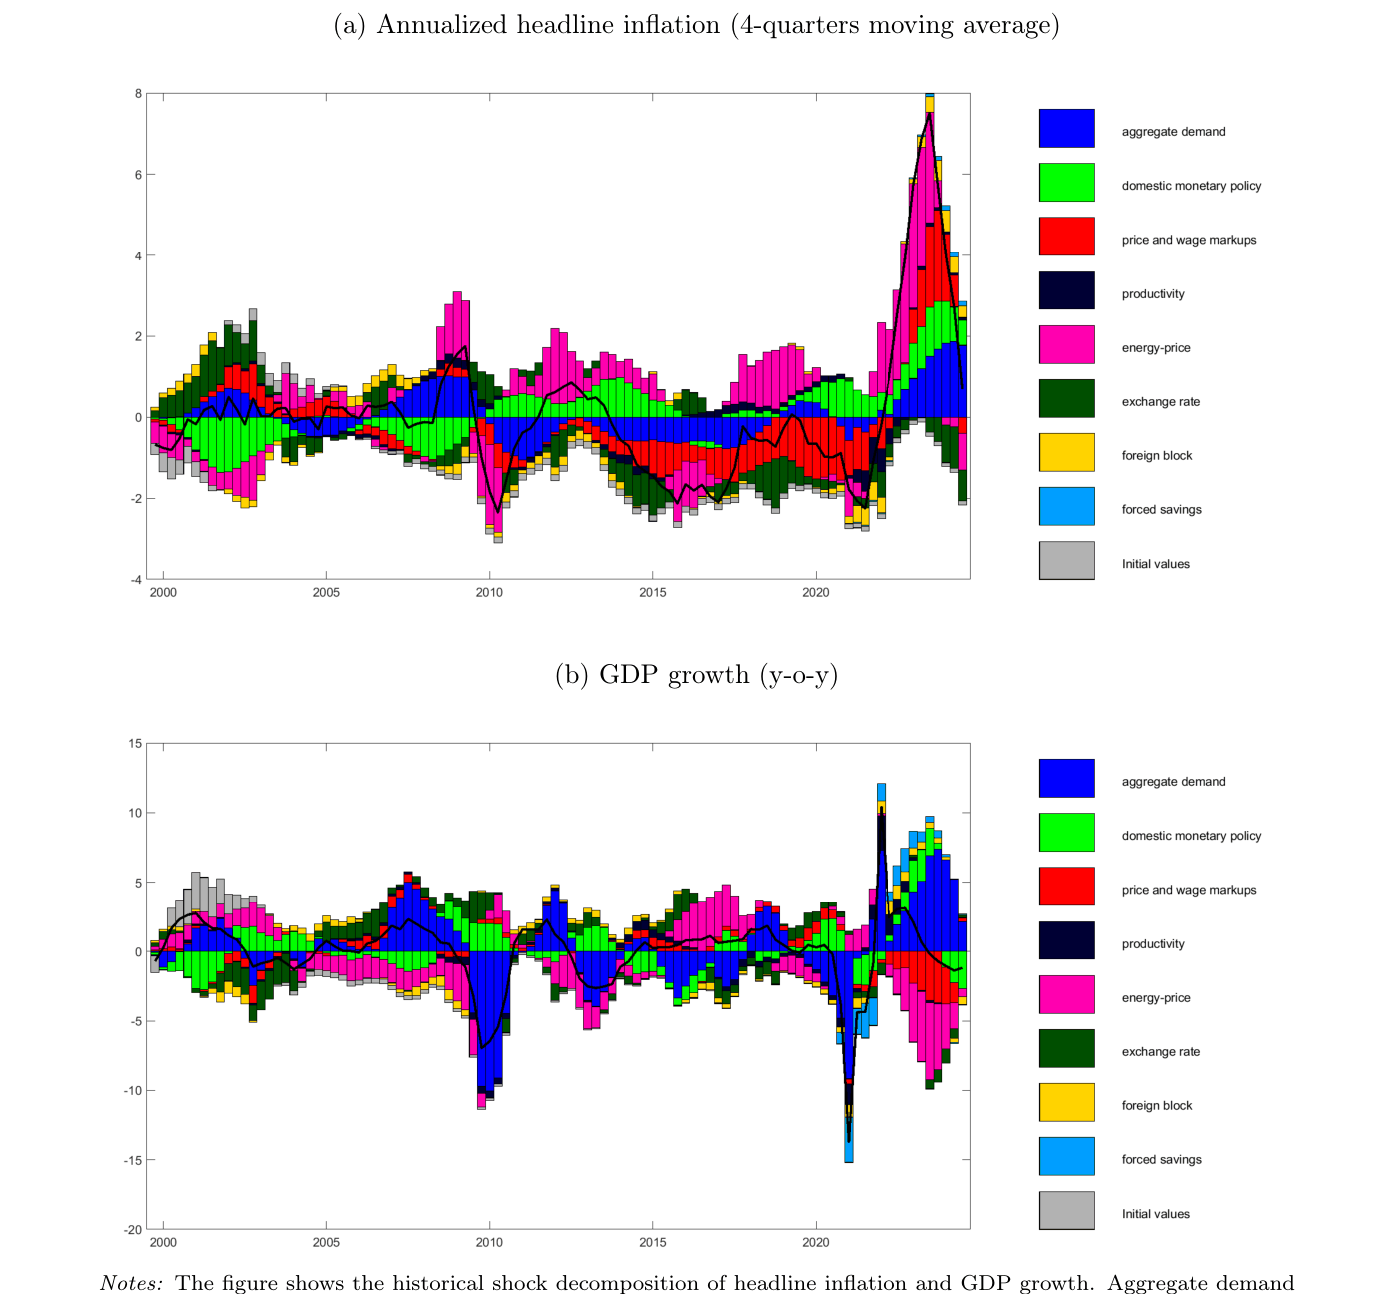
Energy Shocks and Euro Area Monetary Policy

A DSGE model reveals energy and exchange-rate shocks drive euro inflation volatility, and optimal policy can exploit the exchange-rate channel rather than looking through energy shocks.

Fanfare 2Macro-Finance & RatesAlice Albonico et al.PDF

Drivers of headline inflation and GDP growth: a historical decomposition
Figure 2: Drivers of headline inflation and GDP growth: a historical decomposition
24

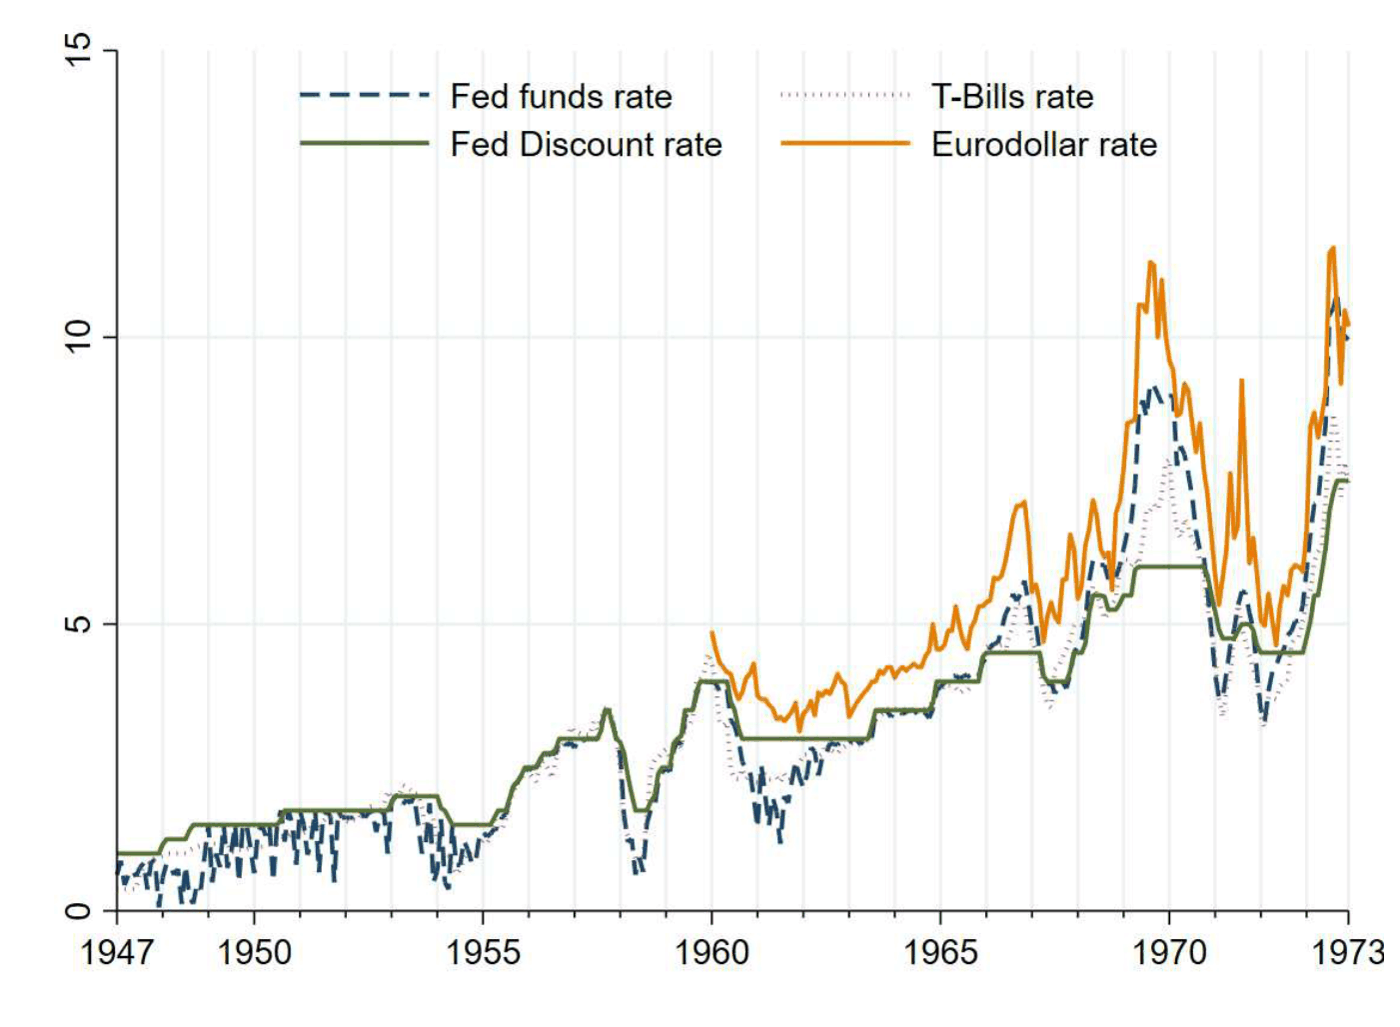
Eurodollars and Bretton Woods Monetary Transmission

US monetary tightening attracted capital through Eurodollar borrowing but did not transmit to foreign output, revealing continued financial segmentation despite offshore growth.

Fanfare 2Macro-Finance & RatesGuillaume Bazot et al.PDF

Fed discount rate, fed funds rate, T-Bills rate, and Eurodollar rate from 1947-1973.
Figure 2: The discount rate of the Federal reserve and the main short-term US interest rates, 1947-1973
27

Dollar Safe Asset Convenience Yields Persist

Dollar safe asset convenience yields remain stable domestically since 2019 but decline globally relative to other currencies, with repo markets leading.

Fanfare 2Macro-Finance & RatesArvind Krishnamurthy and Miguel ChumboPDF

29

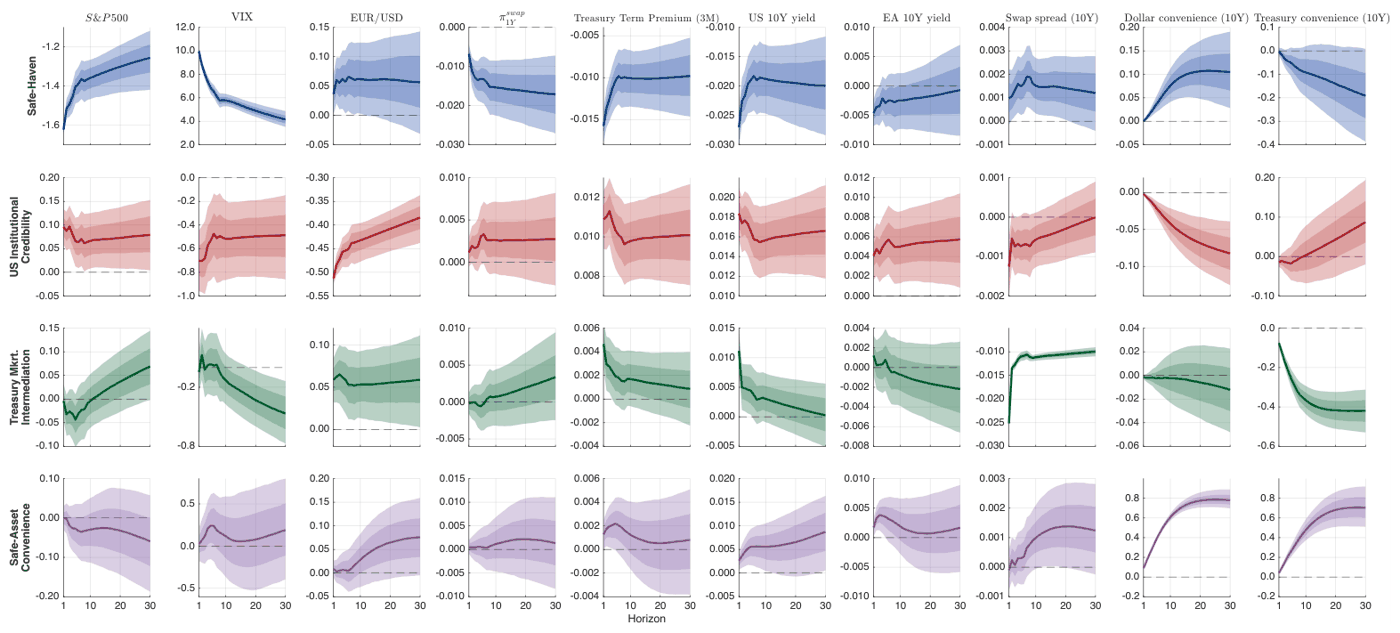
Volatility-Based ID of April 2025 Tariff Shocks

Volatility and kurtosis reveal that dollar depreciation and rising Treasury yields reflect multiple distinct shocks rather than a single tariff announcement shock.

Fanfare 2Macro-Finance & RatesLucas ter Steege and Sofia VelascoPDF

Impulse response functions
Figure 3: Impulse response functions

Risk, Credit & Banking4

05

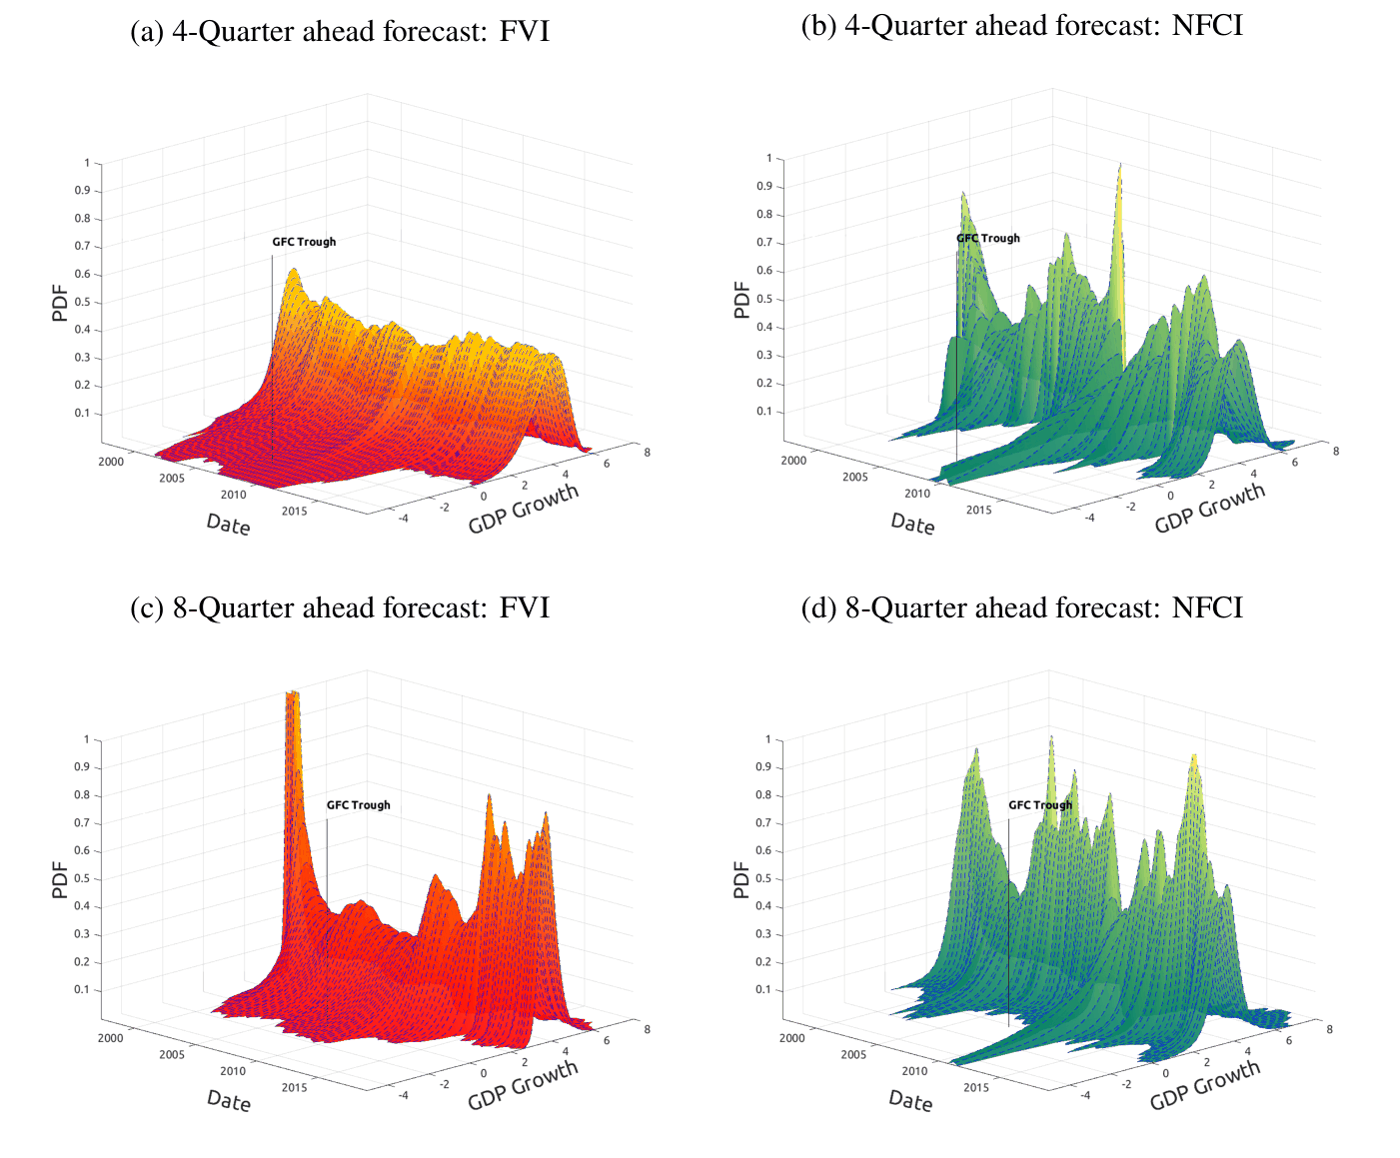
Financial Vulnerability Index for U.S. System

An index capturing structural financial weaknesses displays gradual buildup before crises, predicts shock amplification, and reveals delayed monetary policy transmission effects.

Fanfare 3Risk, Credit & BankingMichele Modugno et al.PDF

Fitted skewed-t distributional forecasts of GDP growth conditional on lagged GDP growth and FVI or NFCI. The fitted
Figure 4: Fitted skewed-t distributional forecasts of GDP growth conditional on lagged GDP growth and FVI or NFCI. The fitted fitted skewed-t distribution is estimated t…
06

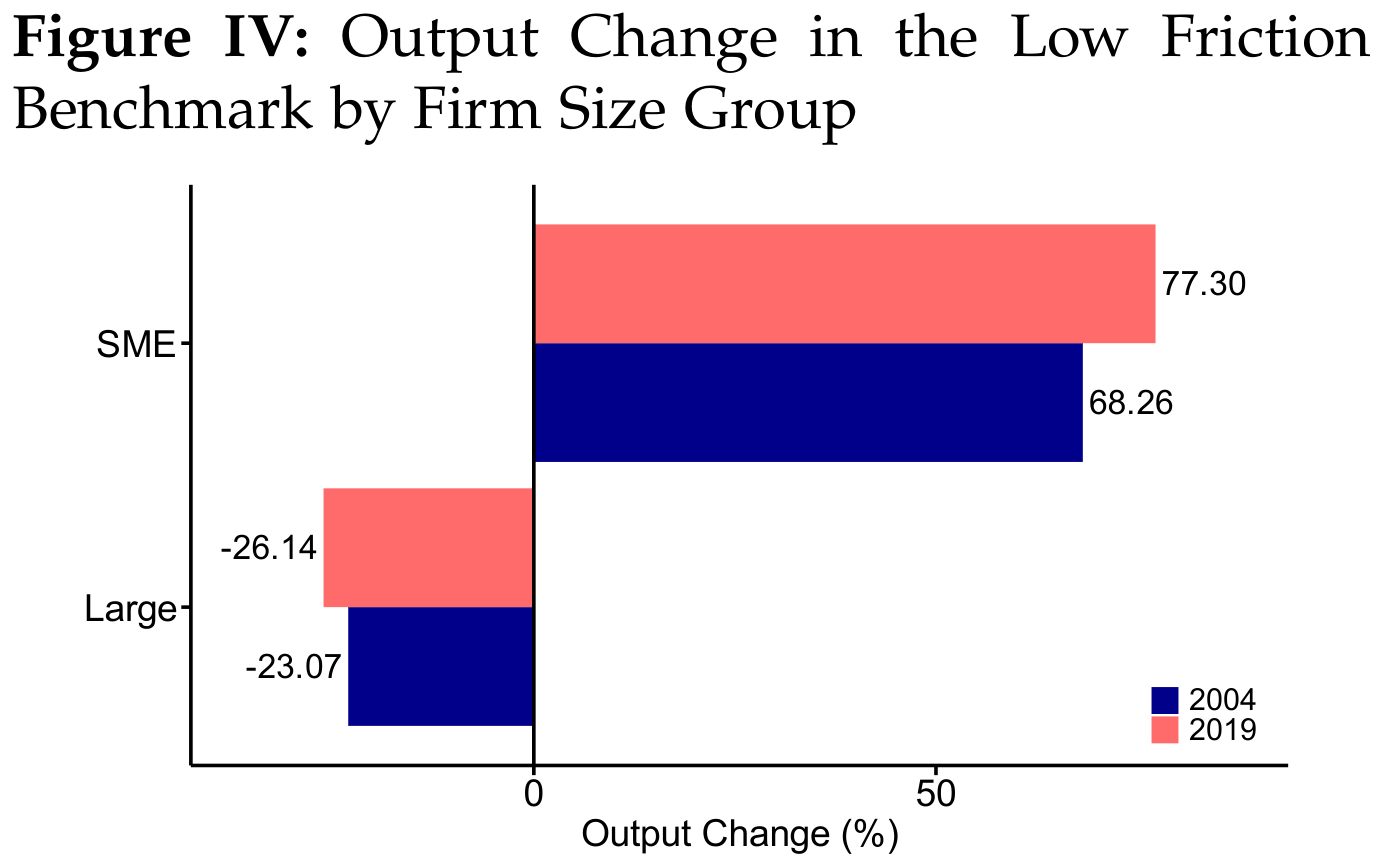
Credit Frictions and Aggregate Economic Output

UK firm-level data shows relaxing credit frictions raises output by 25% and wages by 23%, with most gains from capital accumulation rather than reallocation.

Fanfare 3Risk, Credit & BankingTimothy J. Besley et al.PDF

Output change comparing SME and large firms under low friction scenario, 2004 vs 2019.
11

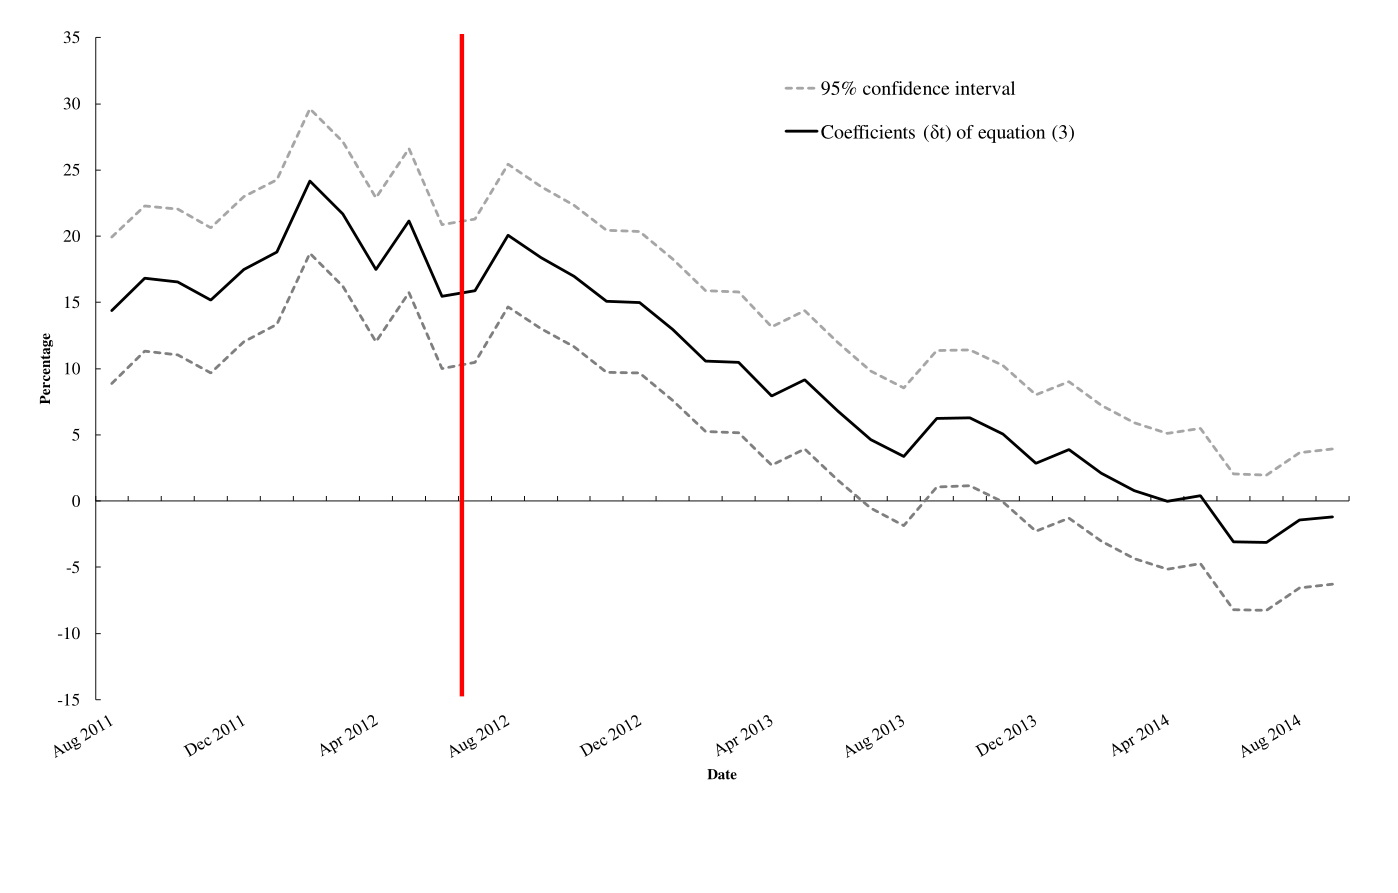
ECB's Whatever It Takes and Bank Risk-Taking

The ECB's "whatever it takes" announcement reversed euro area banks' risk appetite, reducing loan growth and credit risk, showing capitalization can curb lending during crises.

Fanfare 3Risk, Credit & BankingCarlo Alcaraz et al.PDF

Coefficient trend showing reversal in euro bank risk-taking post-announcement
FIGURE 6. Trend reversal. Note: This figure plots the coefficients (δt) of the Equation 3, in %. δt represent the interactions between the treated group (i.e. euro banks…
13

Banker Outside Options and Credit Risk

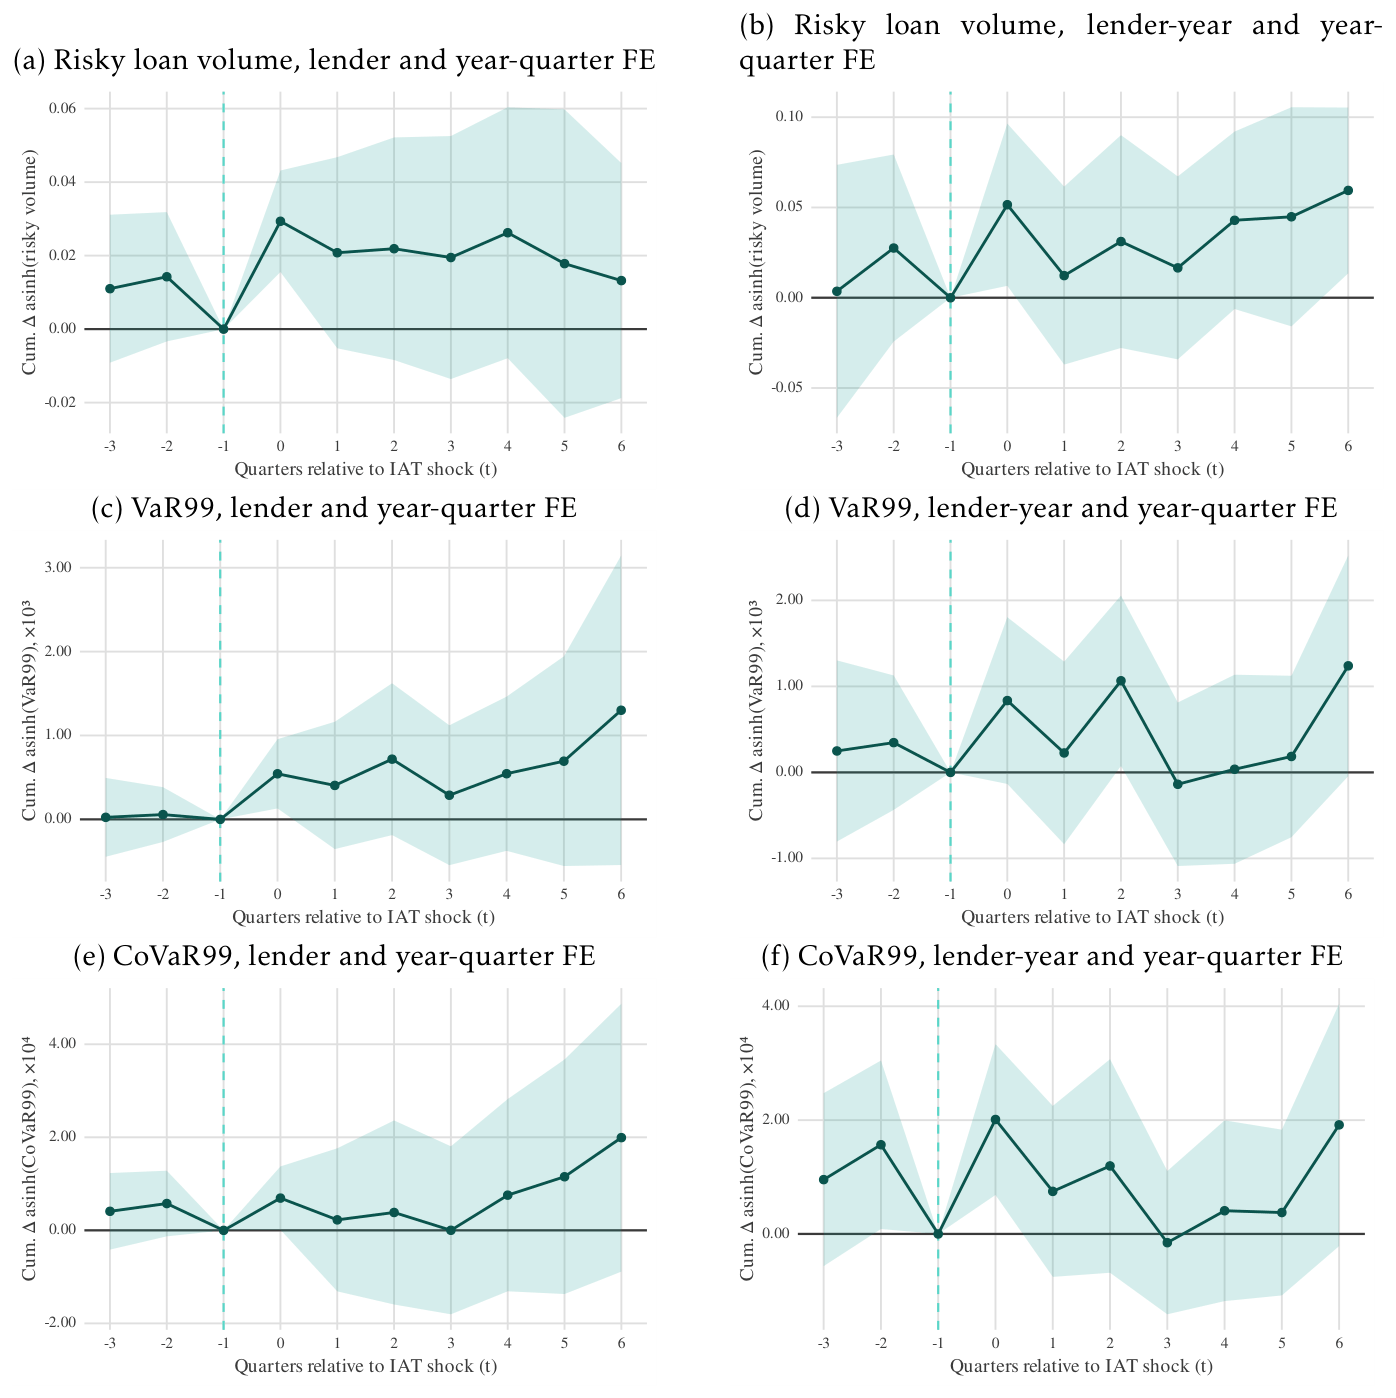
Improved job opportunities for bankers increase non-investment-grade lending and borrower risk without compensating spreads, raising systemic risk through weakened workplace discipline.

Fanfare 3Risk, Credit & BankingValentin Kecht and Georg SchneiderPDF

Dynamic effects of risky loan volume growth and financial risk with confidence bands
Figure 4: Dynamic Effects of Risky Loan Volume Growth and Financial Risk

Portfolio & Allocation2

14

Policy Beliefs Drive Returns in Chinese Funds

The study shows that mutual fund managers' policy beliefs predict market returns and explain positive alphas, while sentiment beliefs attract flows but lack predictive power.

Fanfare 3Portfolio & AllocationZhenyu Gao et al.PDF

26

Optimal Currency Strategies Under CIP Violations

Extending Campbell et al., the analysis shows empirically measured deviations from interest parity reverse optimal currency demands for emerging-market investors.

Fanfare 2Portfolio & AllocationLuis M. Viceira and Sally ShenPDF

Econometrics & Forecasting8

15

Distinguishing FX Shocks from Fundamentals in EMDEs

A framework using deviations from interest-rate parity identifies when exchange-rate movements stem from financial shocks rather than fundamentals, aiding intervention decisions.

Fanfare 3Econometrics & ForecastingEce Ozge Emeksiz et al.PDF

18

Continuous Time Models Beat HAR for Volatility

Fractional processes outperform discrete models like HAR for forecasting realized volatility at longer horizons by better balancing recent levels against long-run persistence.

Fanfare 2Econometrics & ForecastingShuping Shi et al.PDF

21

Classifying Macro News from Asset Co-movements

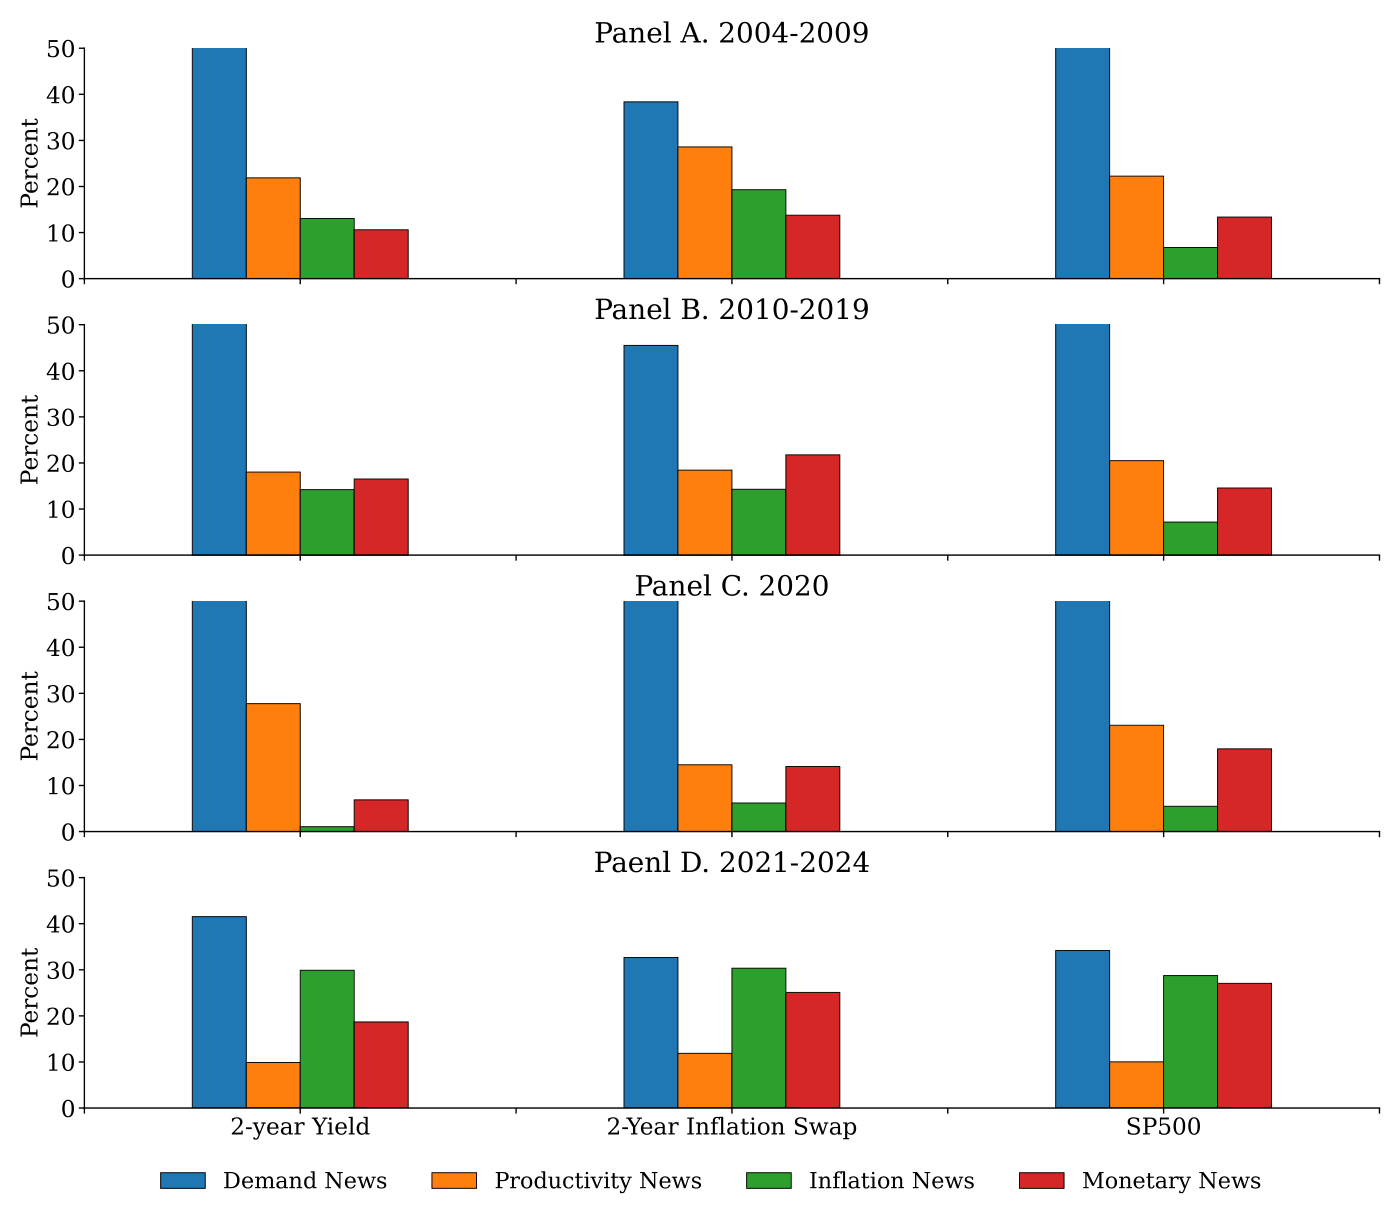
CLONE decomposes daily price moves into demand, productivity, inflation, and policy news using stocks, bonds, and inflation swaps; aggregate demand dominated until 2021.

Fanfare 2Econometrics & ForecastingBruno Feunou et al.PDF

Variance Ratios The figure shows the variance ratios from equation 5 for the S&P 500 Index, 2-year U.S. Treasury yield,
Figure 6. Variance Ratios The figure shows the variance ratios from equation 5 for the S&P 500 Index, 2-year U.S. Treasury yield, and 2-year inflation swap rate, decompo…
22

Term Spread Volatility Predicts Economic Activity

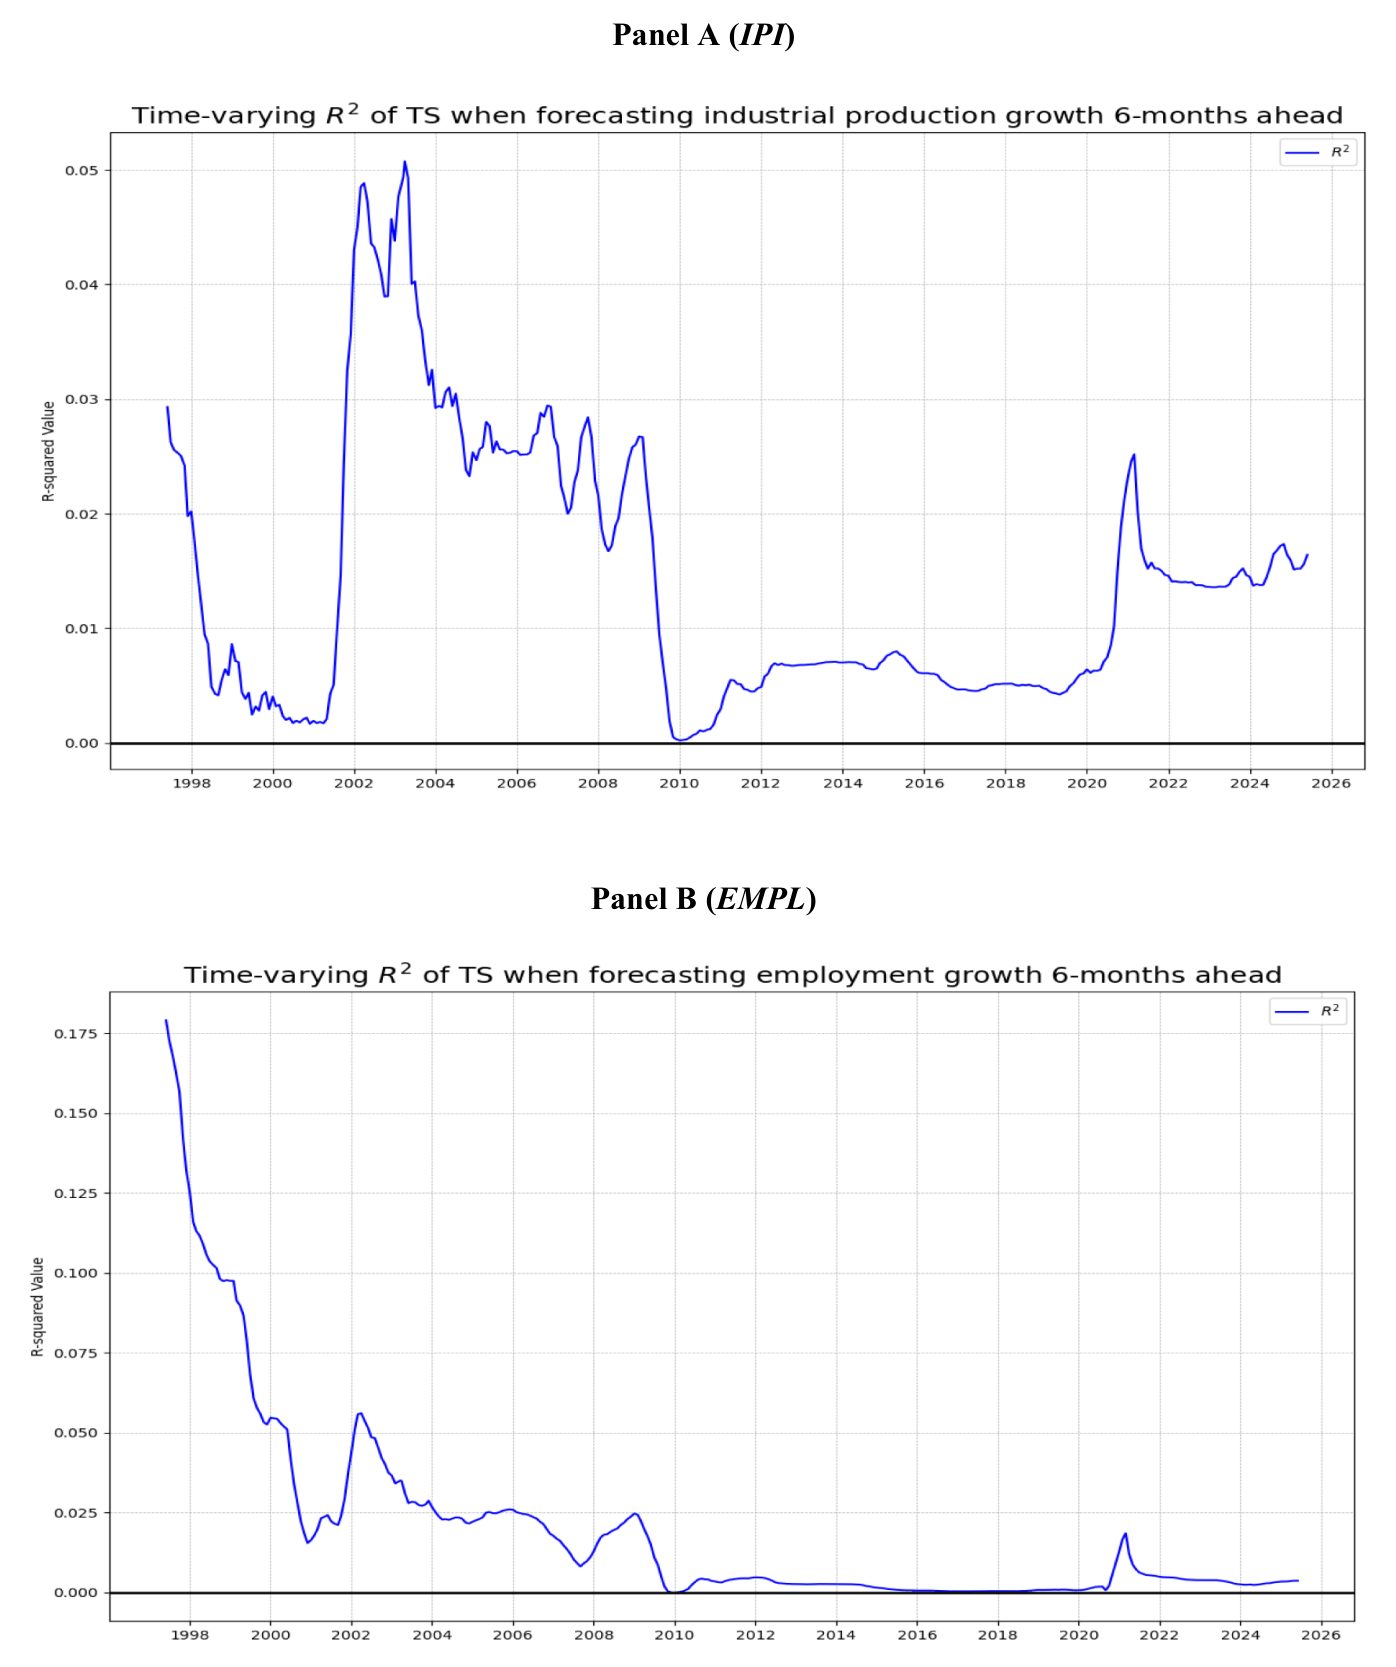
Treasury yield curve slope volatility forecasts industrial production and employment growth at medium and long horizons, outperforming term spread alone after the 2008 crisis.

Fanfare 2Econometrics & ForecastingAnastasios Megaritis et al.PDF

Estimated R2 when forecasting economic activity 6 months ahead using TS
FIGURE 4 | Estimated R2 when forecasting economic activity 6 months ahead using TS.
23

Bayesian Shrinkage in High-Dimensional Panel VARs

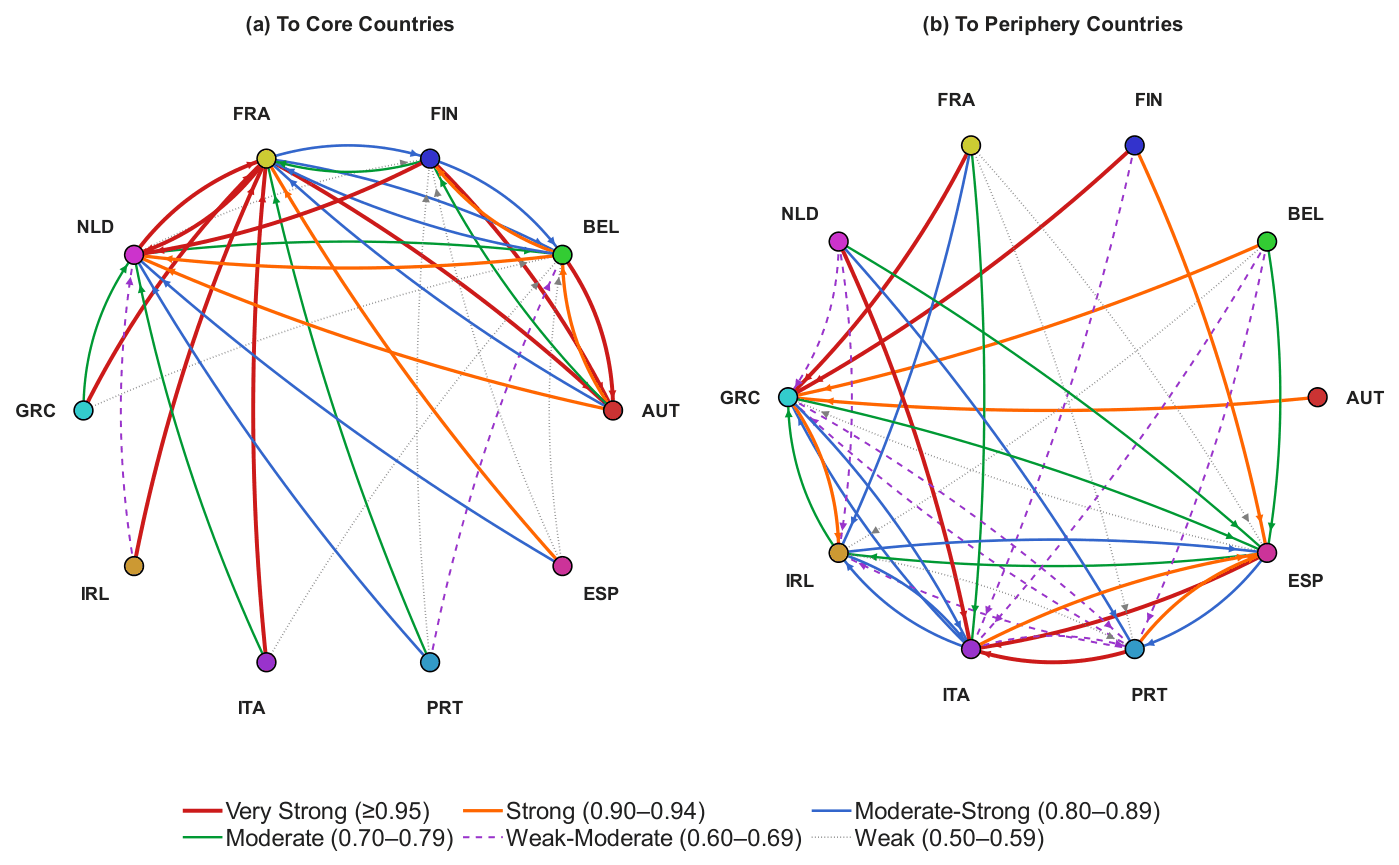
A Bayesian spike-and-slab method improves high-dimensional panel VAR forecasting and reveals heterogeneous spillover structures in sovereign bonds and macro data.

Fanfare 2Econometrics & ForecastingZhiruo Zhang et al.PDF

Posterior Dynamic Interdependencies Across the Euro Area
Figure 5: Posterior Dynamic Interdependencies Across the Euro Area
28

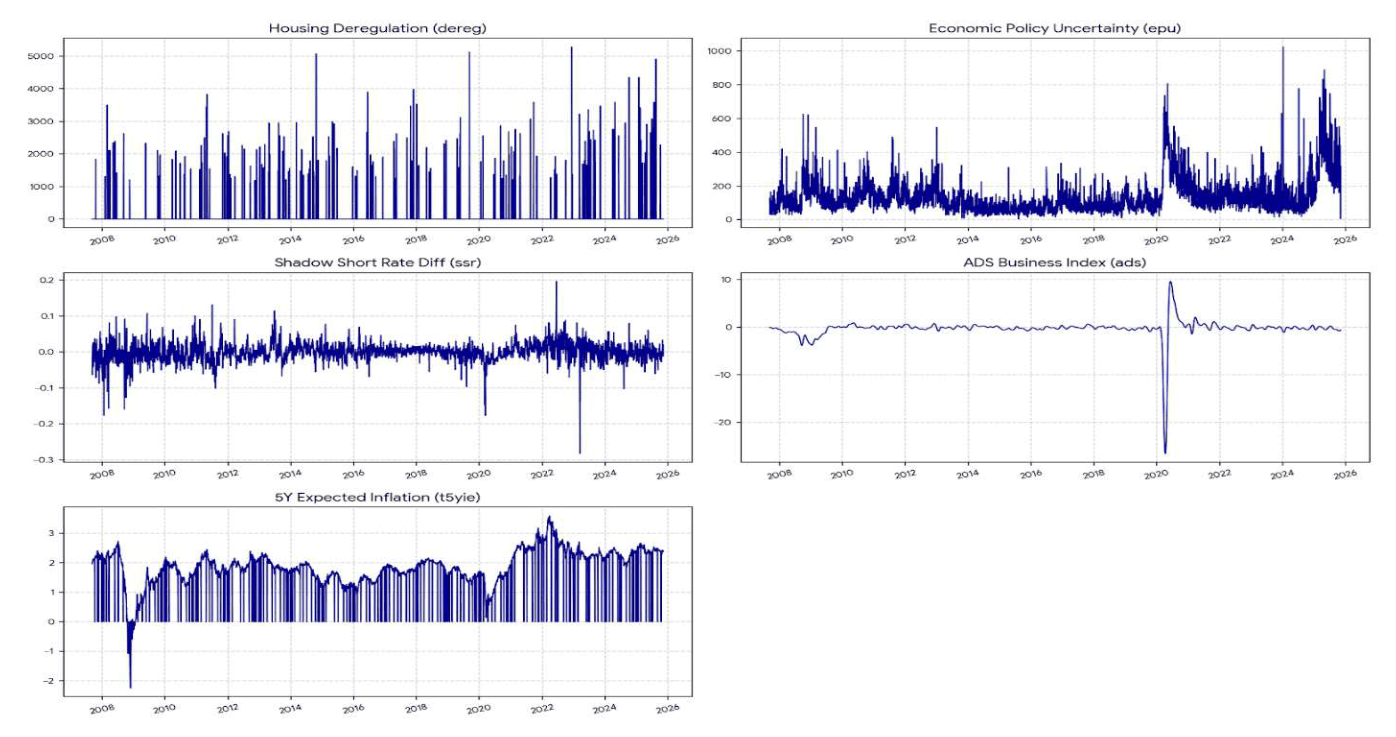
Housing Volatility Spillovers and Policy Networks

A time-varying VAR network reveals supply-inelastic coastal markets absorb largest regulatory shocks and spillovers persist to monetary conditions and inflation expectations.

Fanfare 2Econometrics & ForecastingOnur Polat et al.PDF

Macroeconomic Policy and Financial Indicators
Figure 2. Macroeconomic Policy and Financial Indicators
30

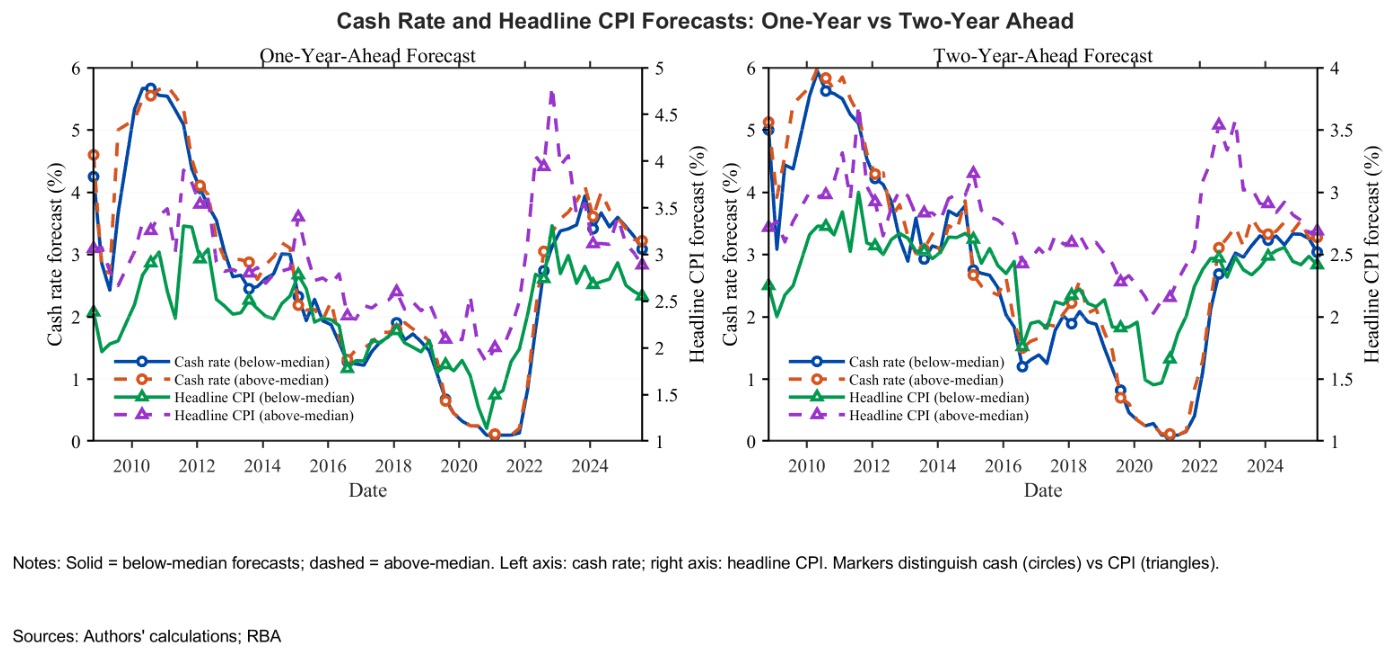
Professional Forecasters' Perceived Policy Rules

Time-varying beliefs about the central bank's reaction function collapsed at the zero bound and rose only after observed tightening, not from guidance alone.

Fanfare 2Econometrics & ForecastingJonathan Hambur and Qazi HaquePDF

Cash rate and headline CPI forecasts
Figure 8: Cash rate and headline CPI forecasts.

Crypto & DeFi2

17

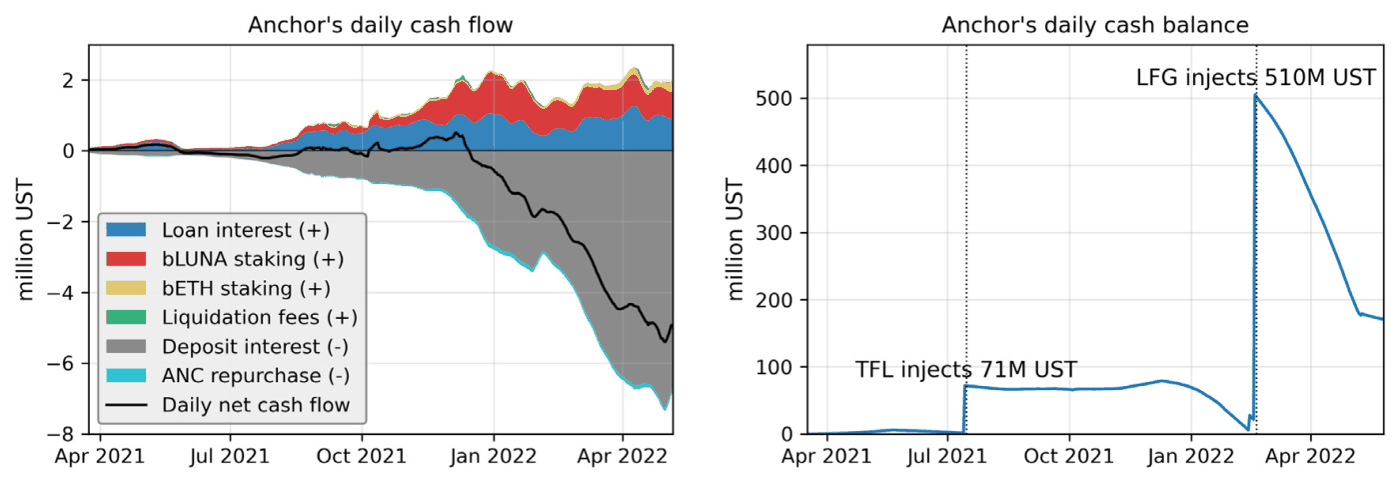
The Terra Luna Blockchain Run Dynamics

Granular blockchain data reveals the Terra crash resulted from subsidized money creation, real-time transaction visibility, and investor concentration amplifying financial fragility.

Fanfare 3Crypto & DeFiJiageng Liu et al.PDF

Anchor's daily cash flow decomposition and balance decline through Terra collapse
Fig. 3. Cash flow decomposition on Anchor. The left panel shows the daily inflows (positive) and outflows (negative) on Anchor in million UST broken out by their sources…
25

Interest Rate Pass-Through in DeFi

The study finds that US risk-free rates predict stablecoin lending rates in decentralized finance, though transmission operates mainly through crypto-native factors like utilization.

Fanfare 2Crypto & DeFiGrigoriy KorolevPDF

Also notable2

07

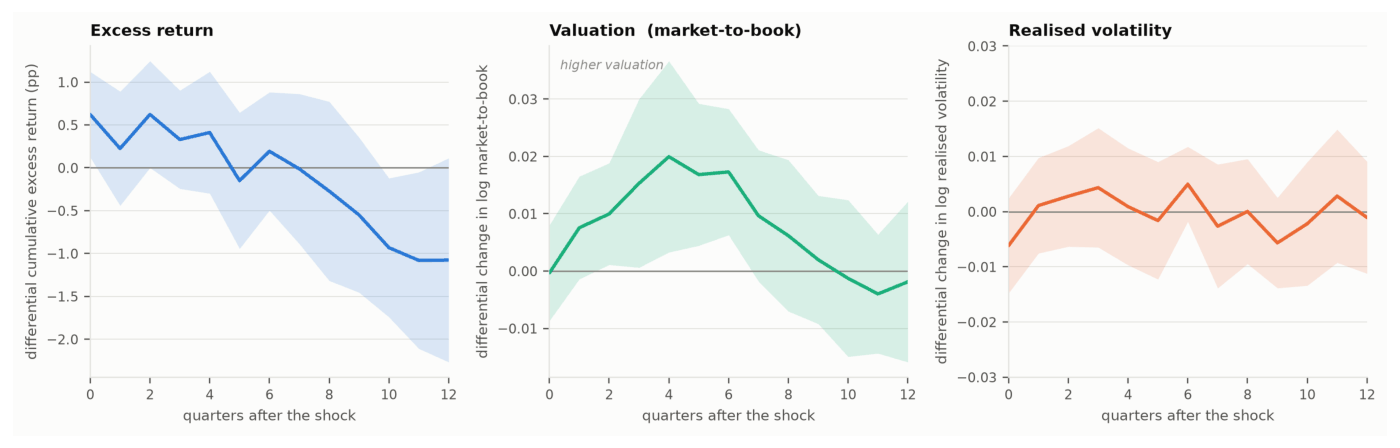
AI Intensity and Economic Shock Responses

Industries with higher AI intensity show significantly higher returns and valuations when hit by supply and technology shocks but not demand shocks.

Fanfare 3ML & AI MethodsChristina Anderl and Guglielmo Maria CaporalePDF

Returns, valuations and volatility following a technology shock, excluding 2020
Figure 7. Returns, valuations and volatility following a technology shock, excluding 2020. The valuation panel plots log market-to-book, so an upward movement denotes a…
10

Volatility Disagreement in Options Market

Cross-sectional dispersion in volatility forecasts predicts delta-hedged straddle losses of 5.14% per month, consistent with mispricing rather than risk compensation.

Fanfare 3Derivatives & VolatilityTuran G. Bali et al.PDF

High-Minus-Low Decile Portfolios Based on VDIS conditional on Stock and Option Characteristics
Fig. 3. High-Minus-Low Decile Portfolios Based on VDIS conditional on Stock and Option Characteristics

Read the paperOpen full-size image

    Type to search. Try rough volatility, LLM agents or FinGPT.

    ↑↓ move↵ openesc closeFull search page