Risk Appetite and Monetary Transmission
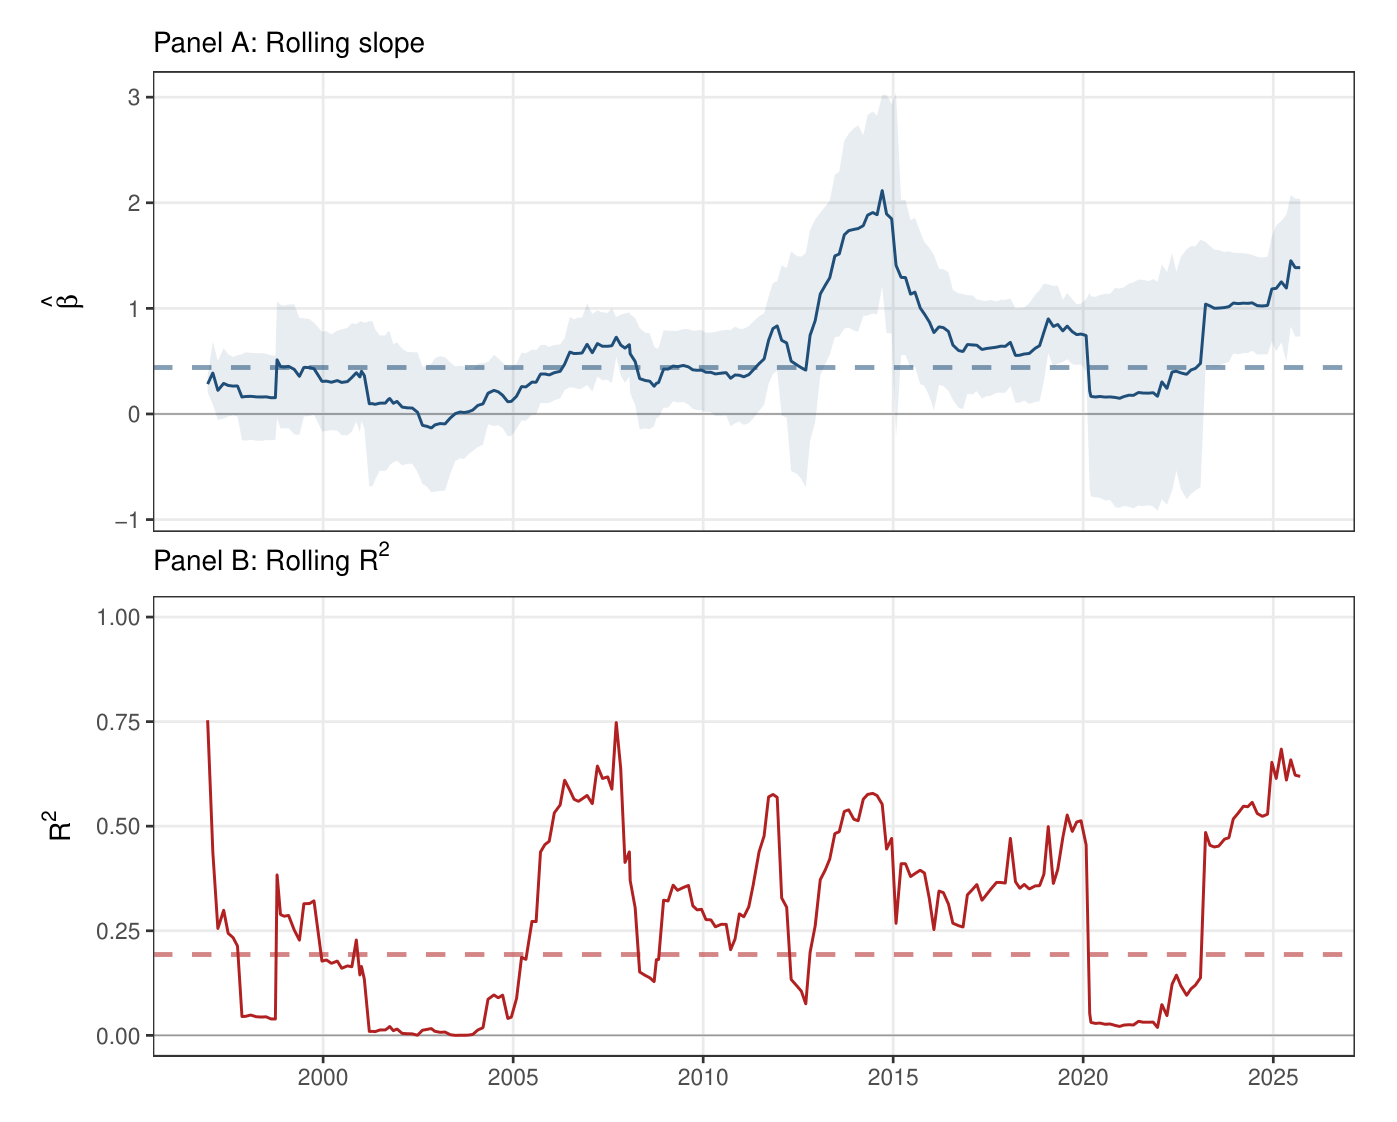
The research shows Fed policy affects risk asset prices primarily through risk appetite shifts, not interest rates; transmission via risk appetite dwarfs rate-channel effects.
Featured in No. 134 on 9 Oct 2026 · 4 days after release
- Released
- 5 Oct 2026
- First featured
- No. 134 · 9 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 4 of 5
- Identifier
- RePEc:fip:fedfwp:103796
- Authors
- Michael D. Bauer et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).