Testing Whether Volatility Model Gains Persist: A Prespecified Holdout in Tail Risk Forecasting
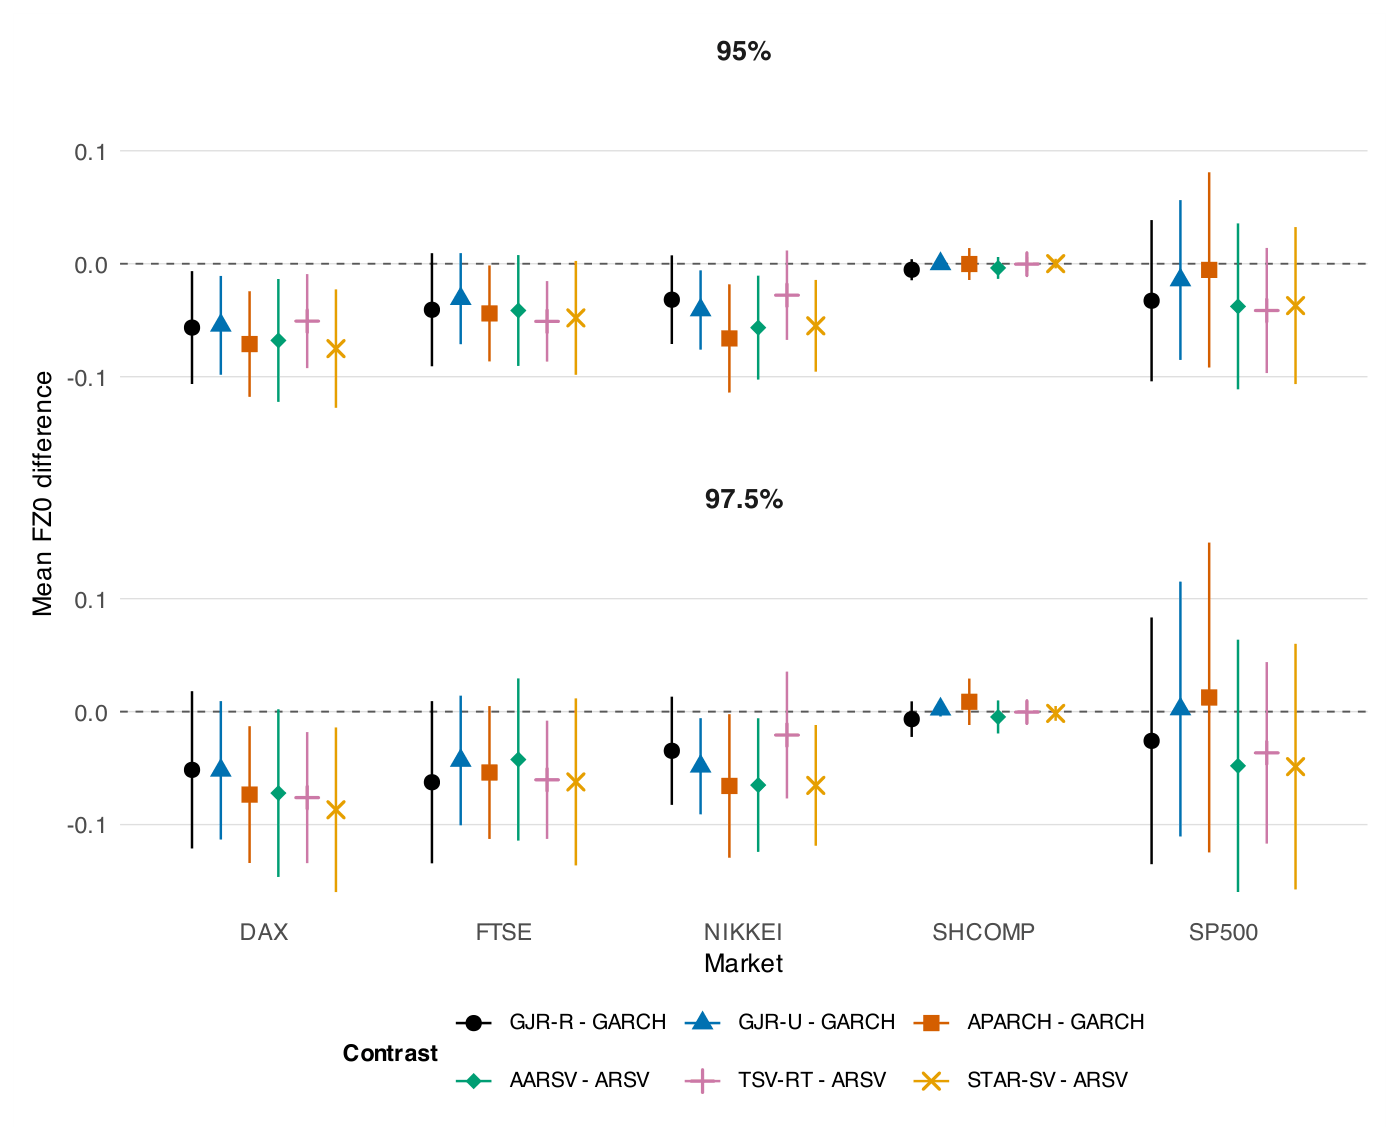
Testing eight volatility models on equity indices with prespecified holdout periods, the research finds that gains from more complex models often do not persist across markets or time.
Featured in No. 133 on 2 Oct 2026 · 2 days after release
- Released
- 30 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:cte:wsrepe:50798
- Authors
- Honfei Guo et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).