Diagnosing and Stabilizing Dynamic Correlations in Multivariate Stochastic Volatility Models
Decomposing forecasting losses into correlation versus scale components, the paper shows how to diagnose and stabilize dynamic-correlation volatility models using realized-volatility inputs.
Featured in No. 133 on 2 Oct 2026 · 9 days after release
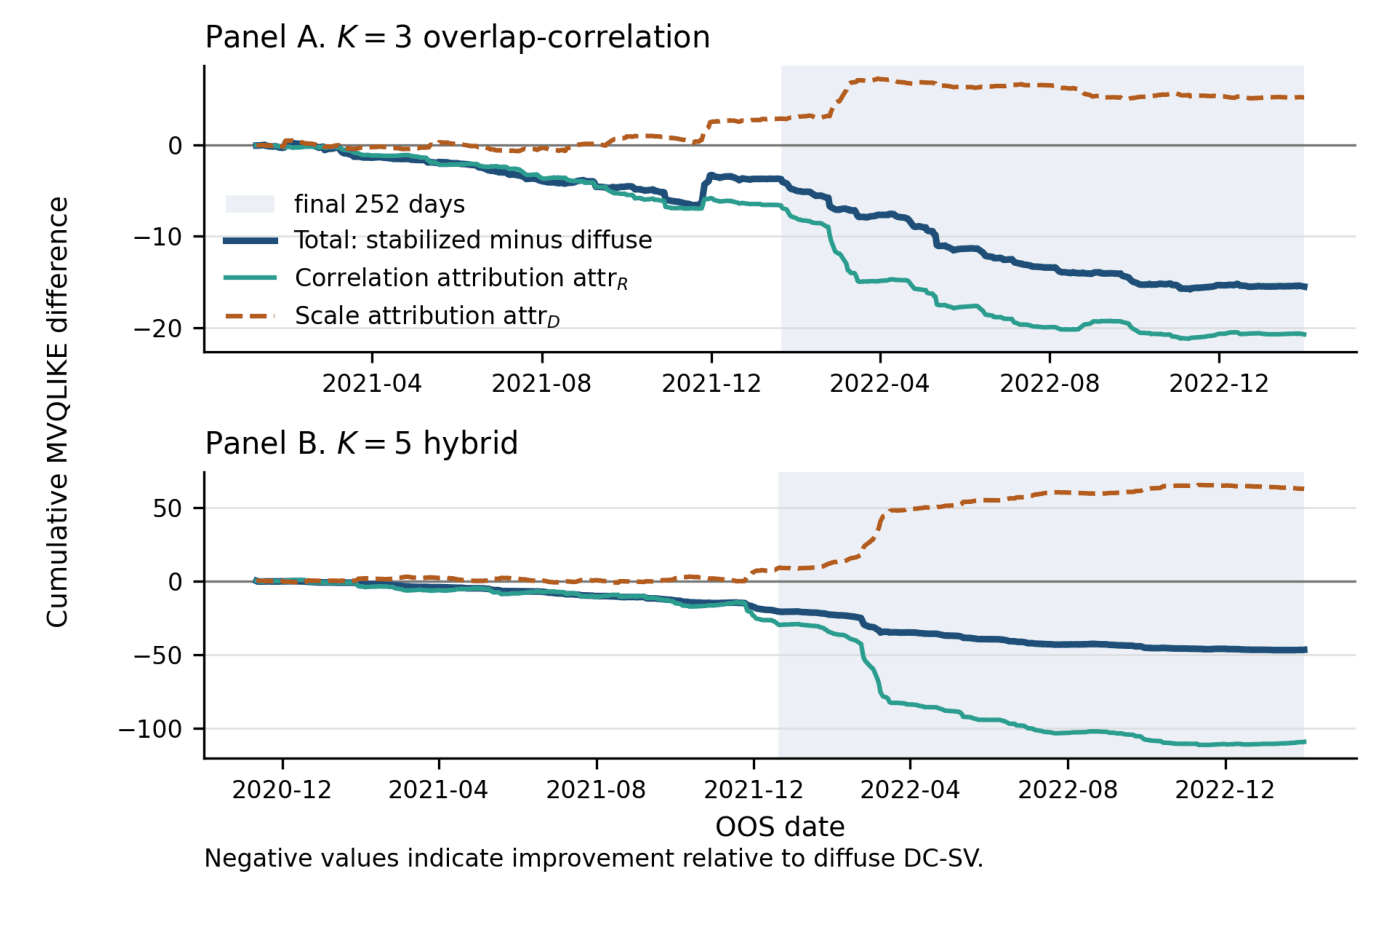
- Released
- 23 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:cte:wsrepe:50561
- Authors
- Hongfei Guo et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).