When Diversification Fades: a Firm Level Perspective of Stock and Corporate Bond Correlations
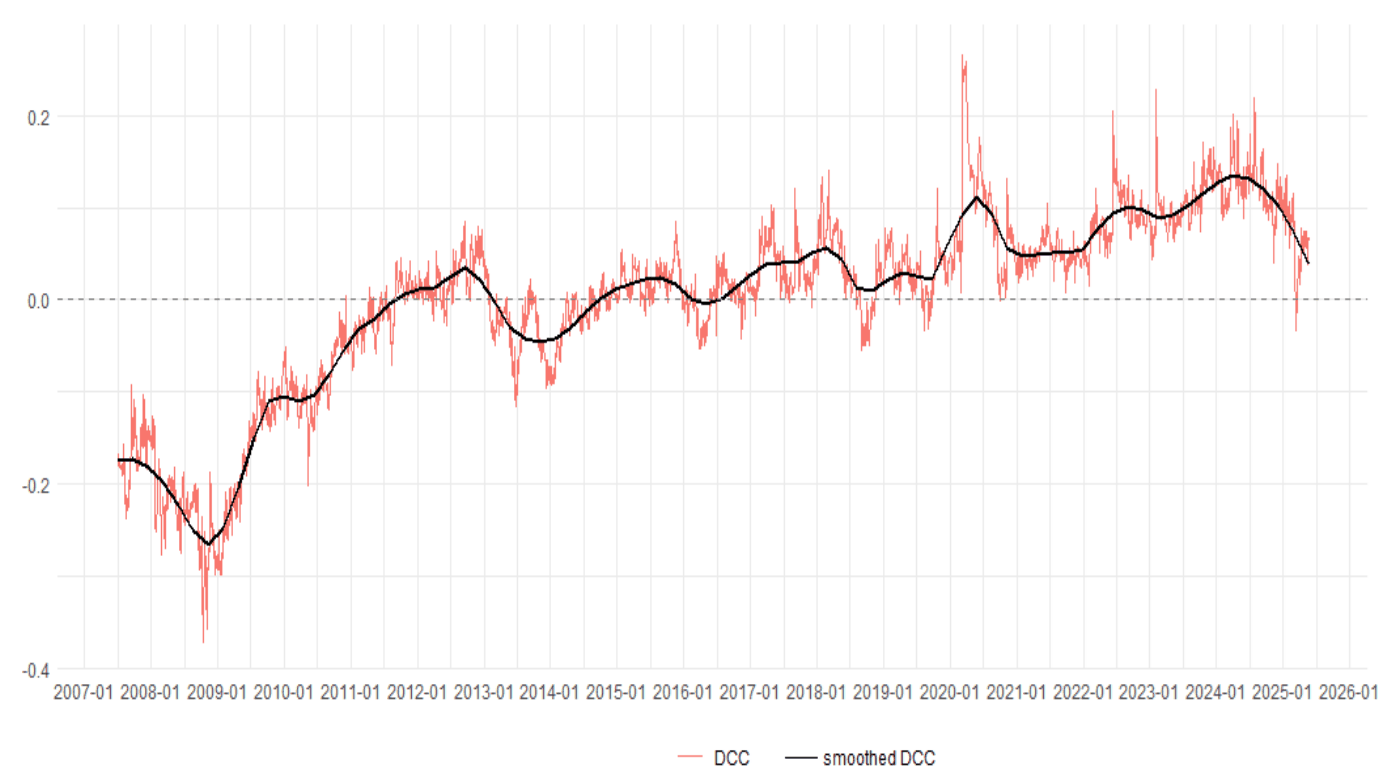
A matched-issuer study finds euro-area stock-bond correlations have trended toward zero since 2009, with discount rates driving co-movement but financial stress effects weakening in high-inflation periods.
Featured in No. 136 on 23 Oct 2026 · 2 days after release
- Released
- 21 Oct 2026
- First featured
- No. 136 · 23 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:bfr:banfra:1065
- Authors
- Linas Jurkšas and Julien Idier
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).