A New Keynesian Model of the Term Structures of Equity and Bond Returns
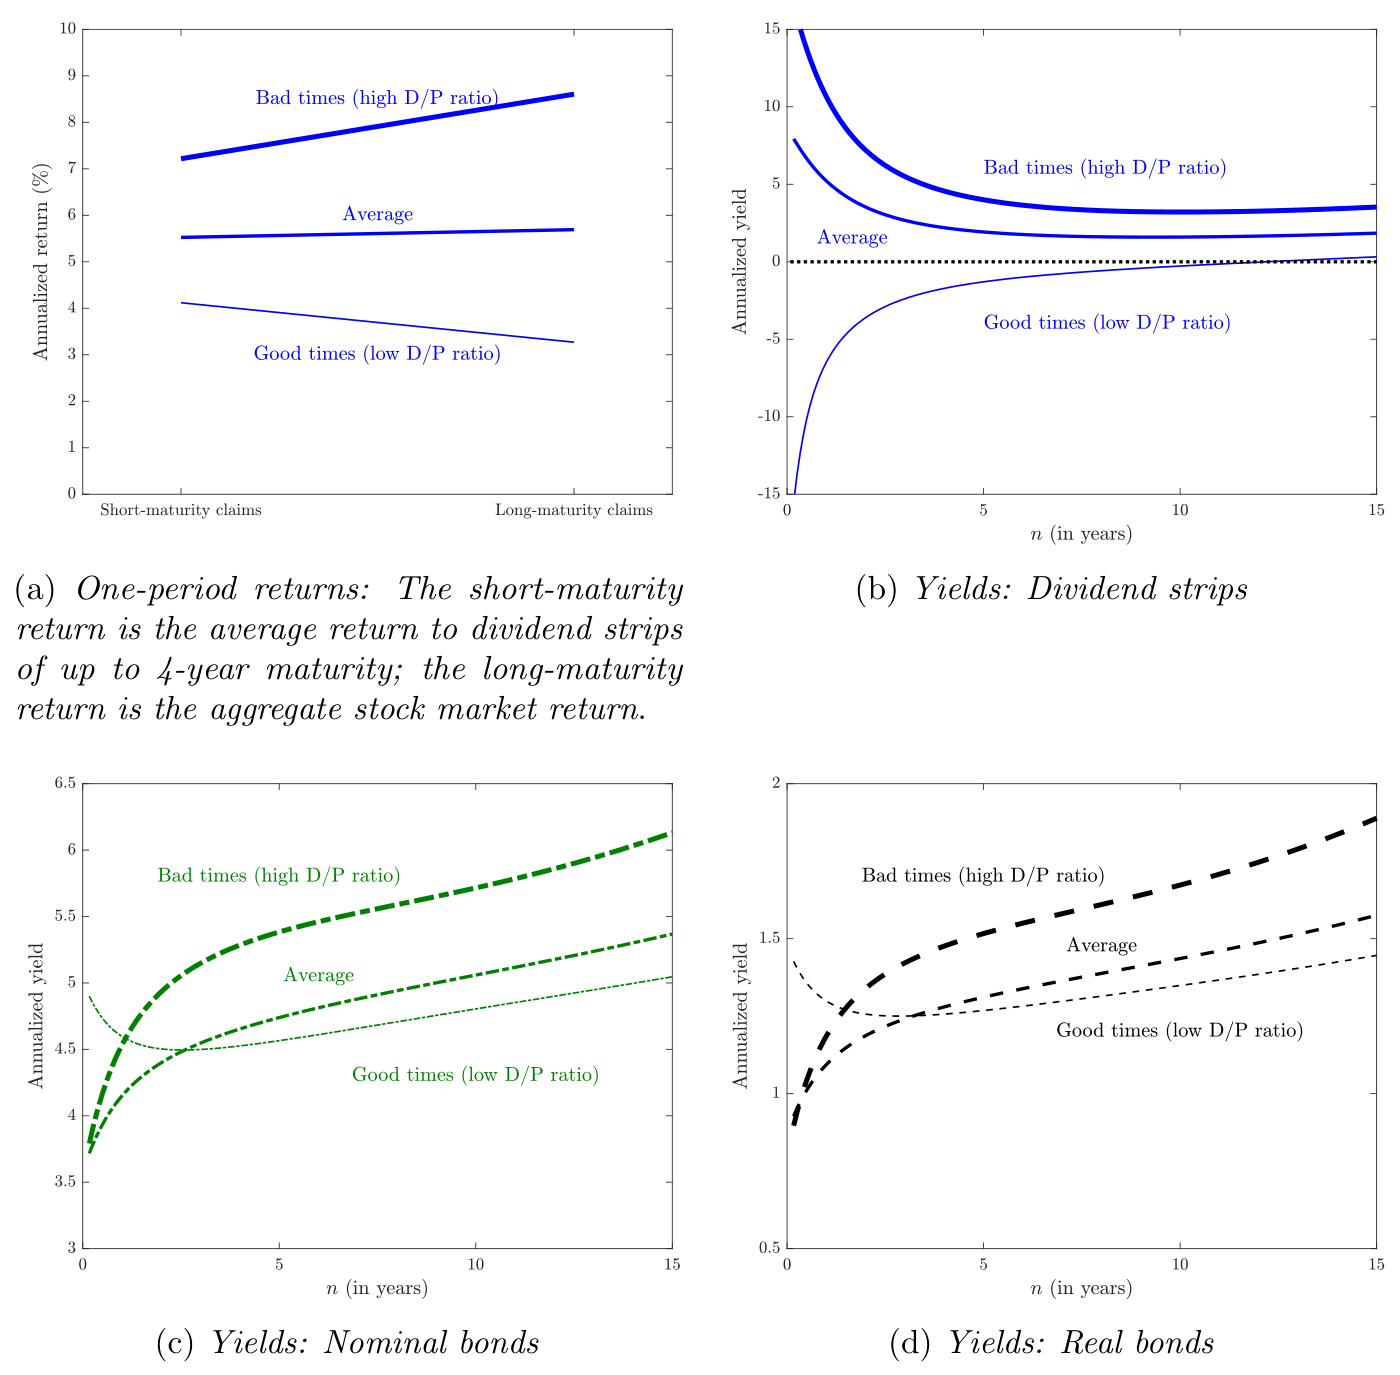
A production economy with sticky prices explains equity and bond term structure slopes and cyclicality through countercyclical inflation and habit-driven risk premiums.
Featured in No. 136 on 23 Oct 2026 · 4 days after release
- Released
- 19 Oct 2026
- First featured
- No. 136 · 23 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:bde:wpaper:2635e
- Authors
- Pierlauro Lopez et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).