arXivEconometrics & Forecasting
Identification through Heteroskedasticity in One Lemma: Partial Identification, an Eigenvalue Construction, and a Caution on Rank Tests
The study unifies identification results for structural shocks when variance paths differ, solving a generalized eigenvalue problem that nests prior work and clarifies what rank tests on second moments actually identify.
Featured in No. 138 on 6 Nov 2026 · 4 days after release
- Released
- 2 Nov 2026
- First featured
- No. 138 · 6 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2610.41361
- Authors
- George Milunovich
Abstract
From arXiv (CC0).
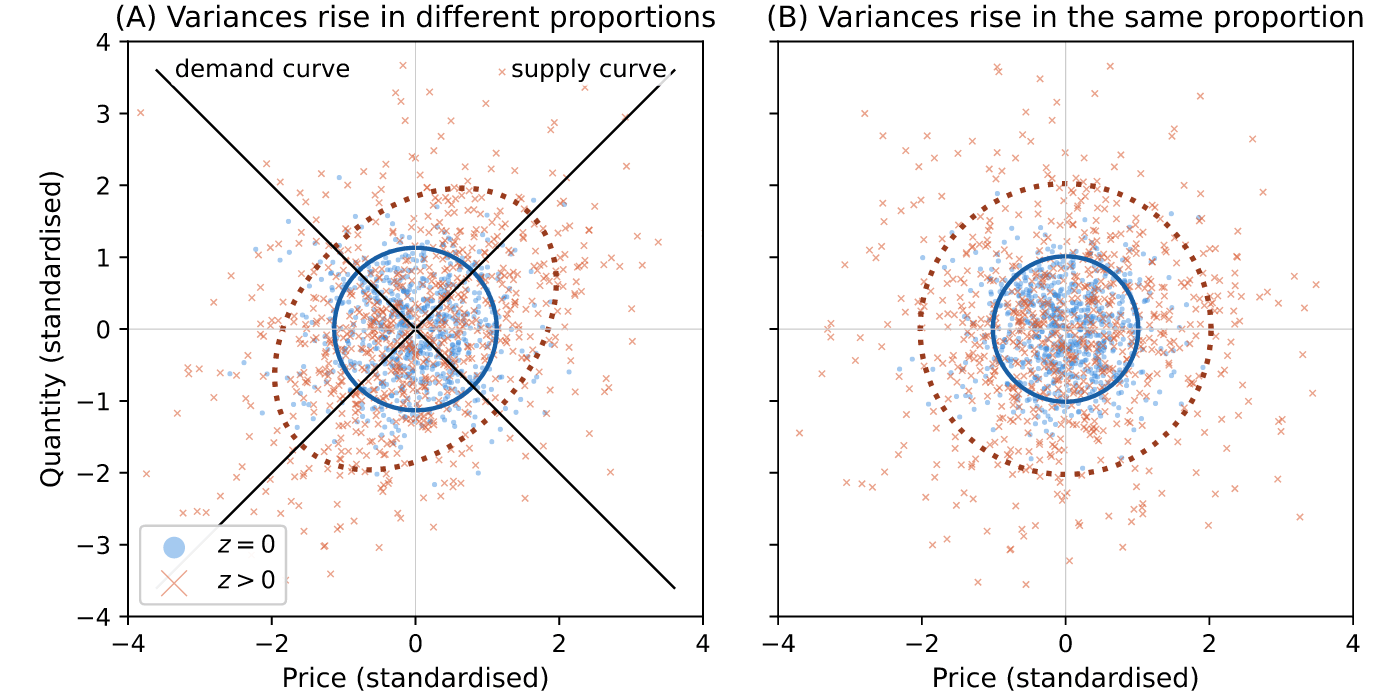
This teaching note unifies known results on identification through heteroskedasticity, under volatility regimes, GARCH, stochastic volatility and covariate-driven variances, in one lemma with a short linear-algebra proof. A shock is identified up to sign and labelling if and only if no other shock shares its variance path, and shocks that share a path are identified up to a rotation. The rows of the structural coefficient matrix solve one generalised eigenvalue problem that nests Rigobon's (2003) two-regime solution. Rank tests on second moments of the errors count at most linearly independent centred variance paths, not identified shocks. A simulation illustrates each point.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).