Dynamic Programming for Value-at-Risk Markov Decision Processes in Continuous Spaces
The paper establishes validity of dynamic programming equations for Value-at-Risk objectives in continuous state and action spaces, enabling optimal execution problems with VaR goals.
Featured in No. 136 on 23 Oct 2026 · 3 days after release
- Released
- 20 Oct 2026
- First featured
- No. 136 · 23 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- arXiv:2610.24439
- Authors
- Xian Chen et al.
Abstract
From arXiv (CC0).
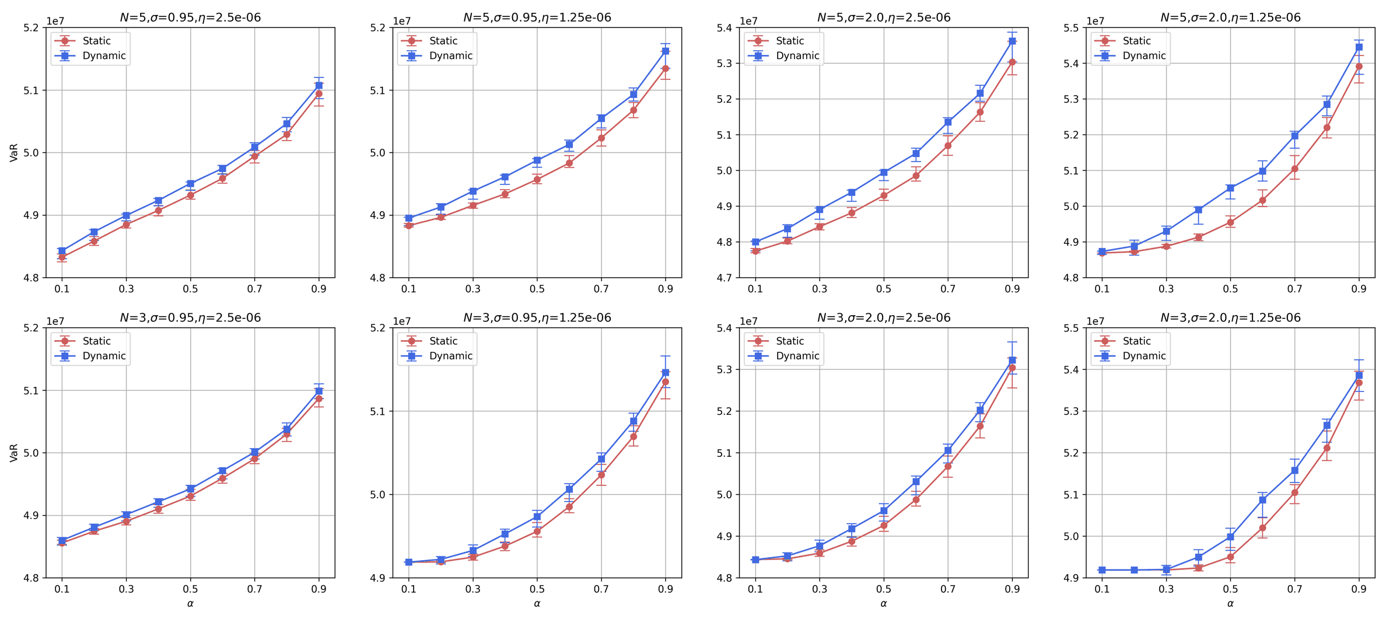
Value-at-Risk (VaR) is a widely adopted quantile-based risk measure in practice, yet incorporating VaR objectives into Markov decision processes (VaR MDPs) remains a longstanding challenge. Recent work has derived dynamic programming equations for VaR MDPs in finite state and action spaces but left the case of more general spaces unresolved. This paper establishes, for the first time, the validity of these equations in continuous spaces, for both finite- and infinite-horizon settings. Such cases naturally arise in many real-world dynamic decision-making problems. As an application, we study an optimal execution problem with a VaR objective and demonstrate that our framework enables the characterization of optimal dynamic strategies, resolving an open question in the field.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).