RePEcTrading, Microstructure & Execution
Elastic in cash, inelastic in repo: Hedge funds in the treasury and repo markets
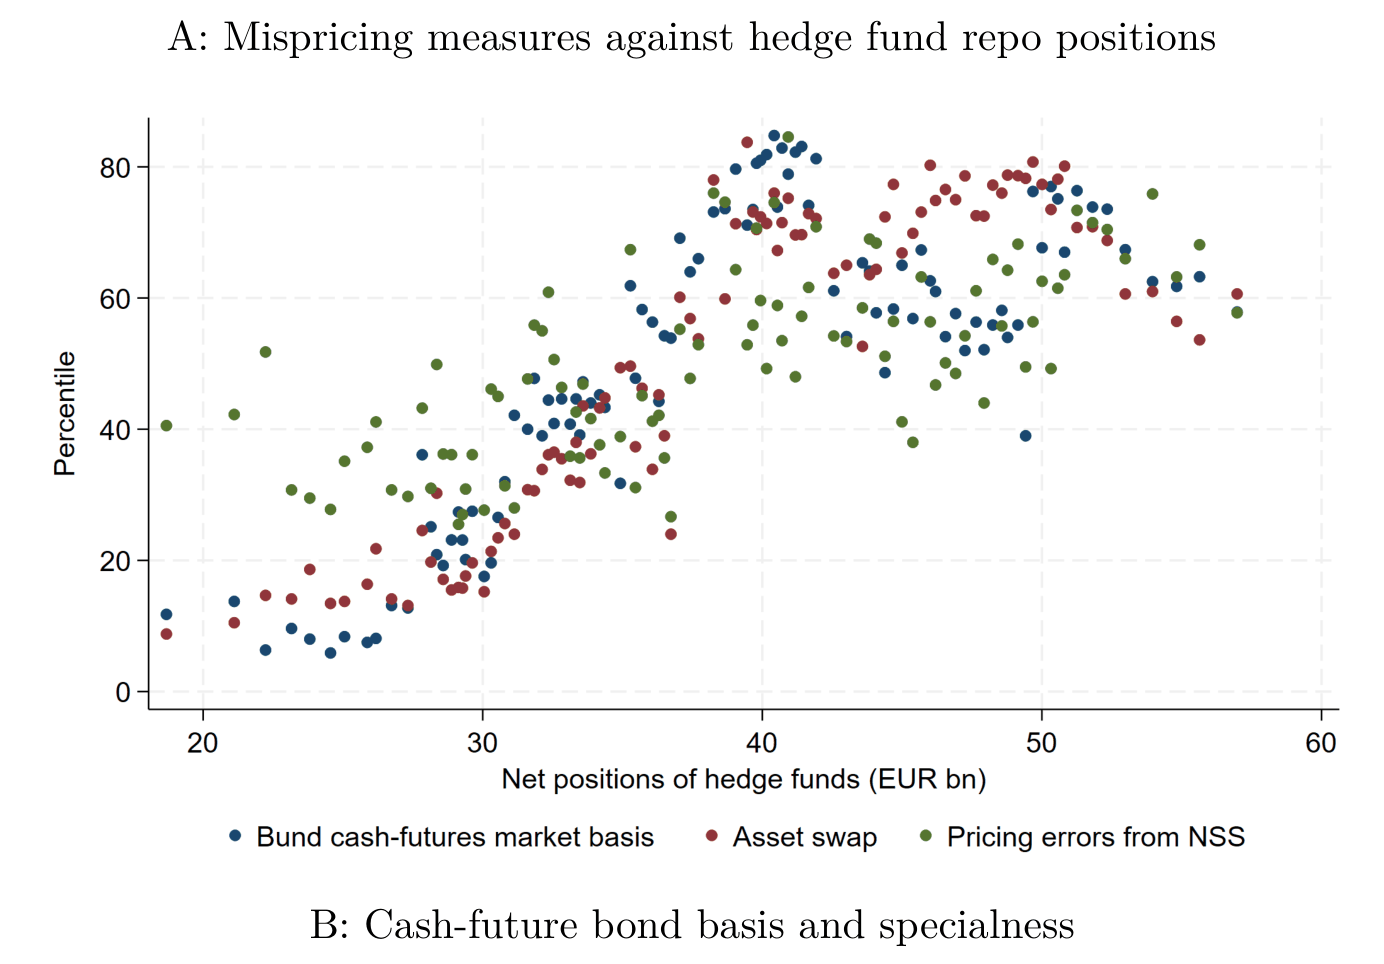
Using German sovereign bond repo data, the research shows hedge funds are price-elastic in cash markets but highly inelastic in repo, inheriting elasticity from their cash-market counterparties.
Featured in No. 132 on 25 Sep 2026 · 8 days after release
- Released
- 17 Sep 2026
- First featured
- No. 132 · 25 Sep 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:zbw:safewp:343098
- Authors
- Andrea Poinelli et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).