RePEcEconometrics & Forecasting
Time-varying Nature of Foreign Portfolio Flows: Evidence from Turkiye
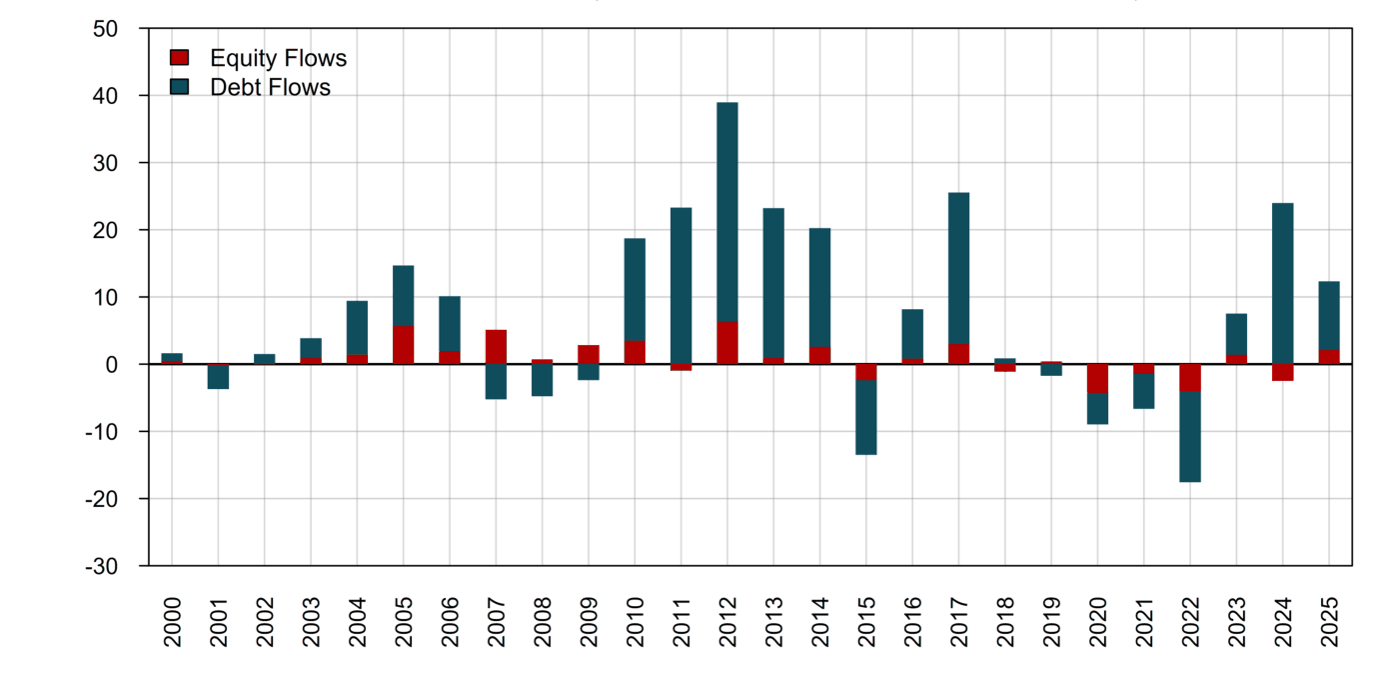
A time-varying VAR model shows that the responsiveness of equity and debt flows to global and domestic shocks has shifted substantially, especially during crises and after 2013.
Featured in No. 140 on 20 Nov 2026 · 4 days after release
- Released
- 16 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:tcb:wpaper:2620
- Authors
- Irfan Cercil et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).