RePEcML & AI Methods
Multilingual Textual Signals and Realized Volatility Forecasting: A Hybrid Transformer-HAR-X Approach Applied to the S&P 500 and the MASI
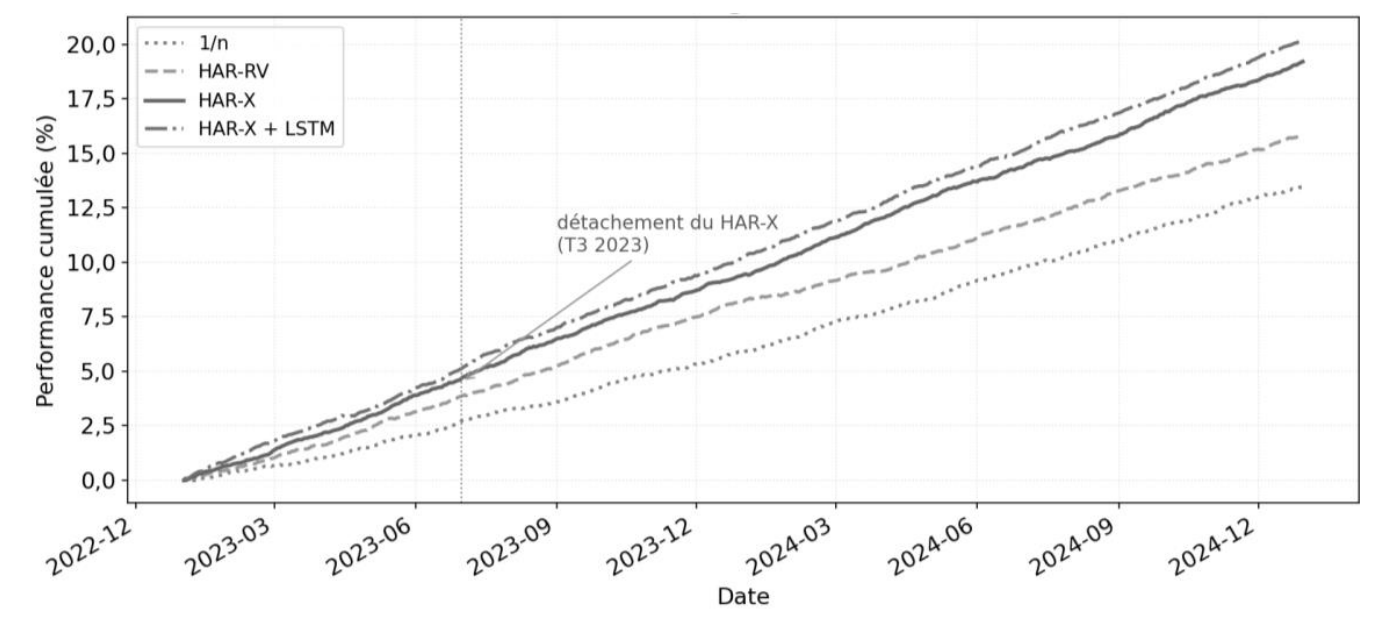
A hybrid FinBERT-HAR-X framework using multilingual news reduces S&P 500 volatility forecast error by 21% and improves realized Sharpe ratios out of sample.
Featured in No. 138 on 6 Nov 2026 · 4 days after release
- Released
- 2 Nov 2026
- First featured
- No. 138 · 6 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:hal:journl:hal-05723648
- Authors
- Sara Boughanou and Adil El Marhoum
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).