RePEcML & AI Methods
Enhancing a Multi-Factor Equity Strategy via Artificial Intelligence and Technical Indicators
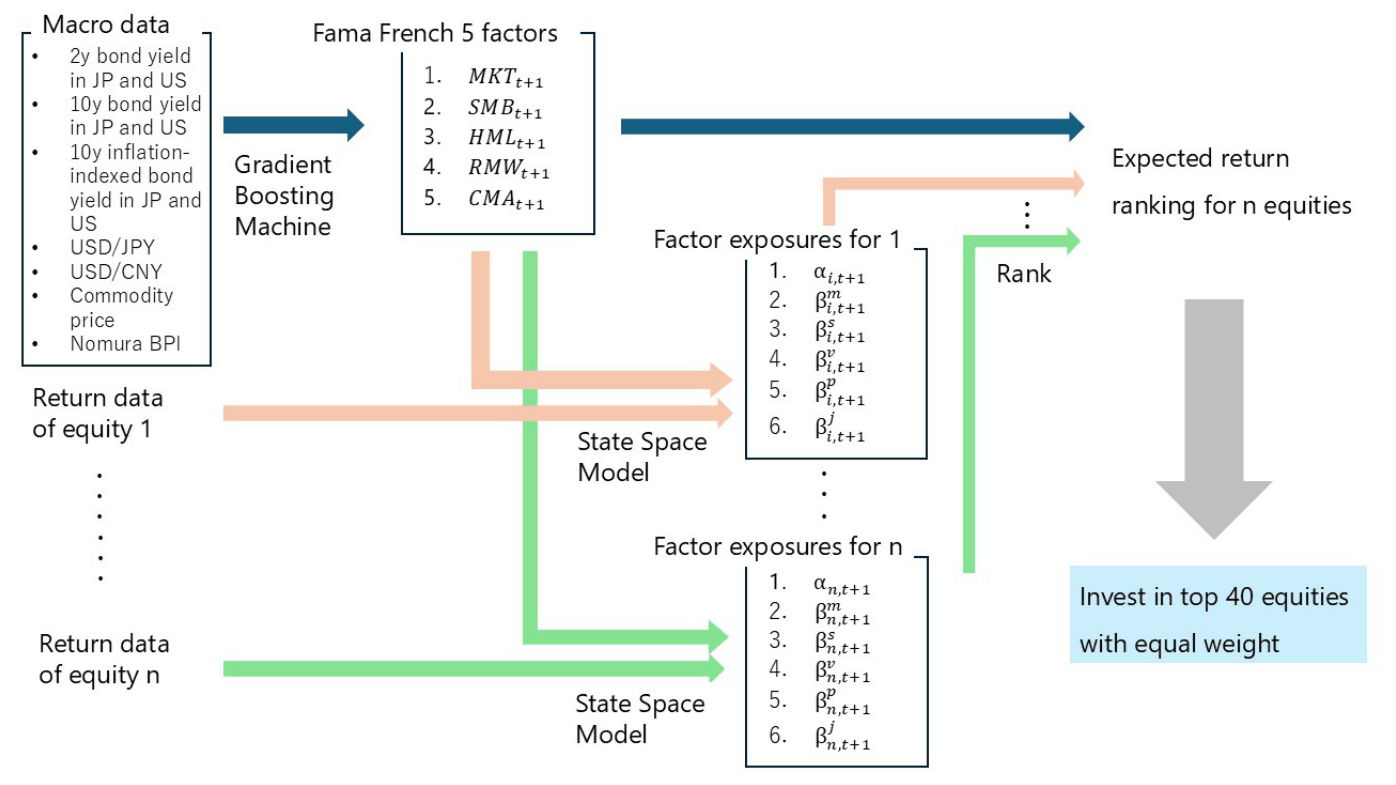
Combining a five-factor model with gradient boosting and technical indicators for hedging, the strategy outperforms index buy-and-hold on Japanese stocks while maintaining interpretability.
Featured in No. 139 on 13 Nov 2026 · 4 days after release
- Released
- 9 Nov 2026
- First featured
- No. 139 · 13 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:cfi:fseres:cf632
- Authors
- Daiya Mita and Akihiko Takahashi
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).