Collateral Advantage: Exchange Rates, Capital Flows, and Global Cycles
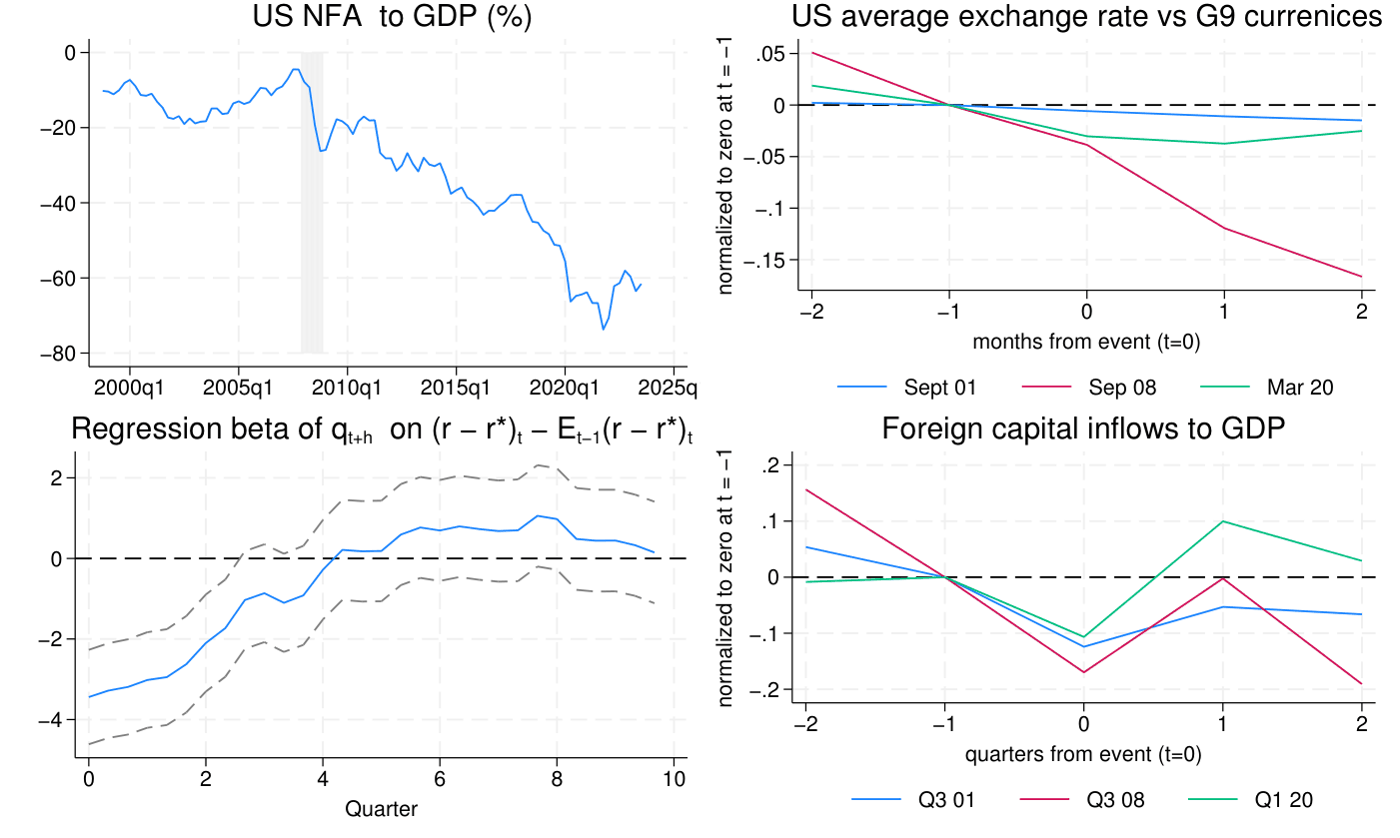
A model shows U.S. Treasury collateral advantage drives dollar appreciation during stress and reconciles exorbitant privilege, financial intermediation, and convenience yield perspectives.
Featured in No. 134 on 9 Oct 2026 · 4 days after release
- Released
- 5 Oct 2026
- First featured
- No. 134 · 9 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:ces:ceswps:_13008
- Authors
- Michael B. Devereux et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).