RePEcML & AI Methods
AI Intensity and Financial Market Responses to Economic Shocks: Evidence from US Industries
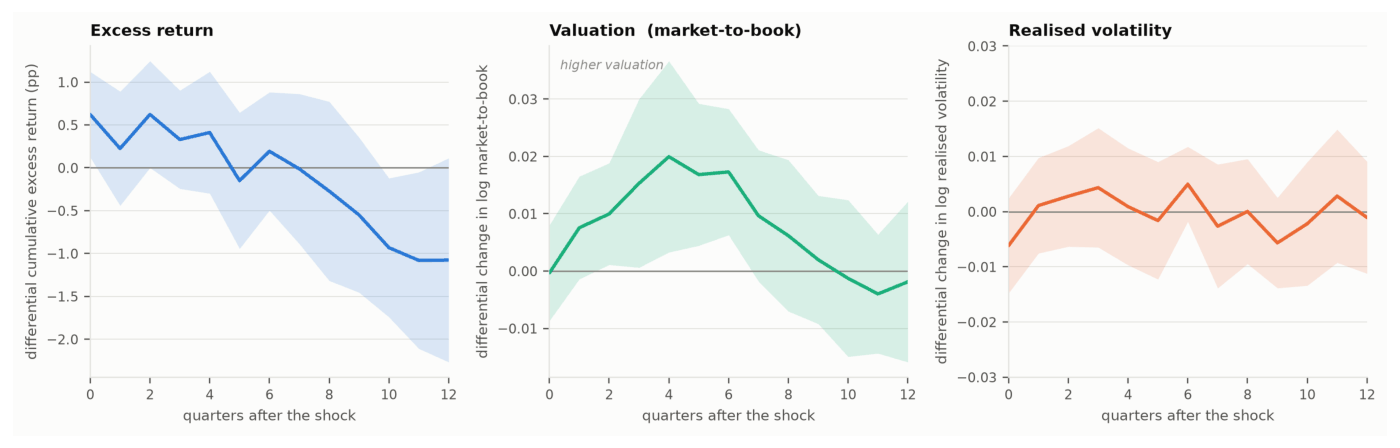
Industries with higher AI intensity show significantly higher returns and valuations when hit by supply and technology shocks but not demand shocks.
Featured in No. 134 on 9 Oct 2026 · 1 day after release
- Released
- 8 Oct 2026
- First featured
- No. 134 · 9 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:ces:ceswps:_13000
- Authors
- Christina Anderl and Guglielmo Maria Caporale
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).