The Fed Put and Bank Risk-Taking: Evidence from the Loan Book
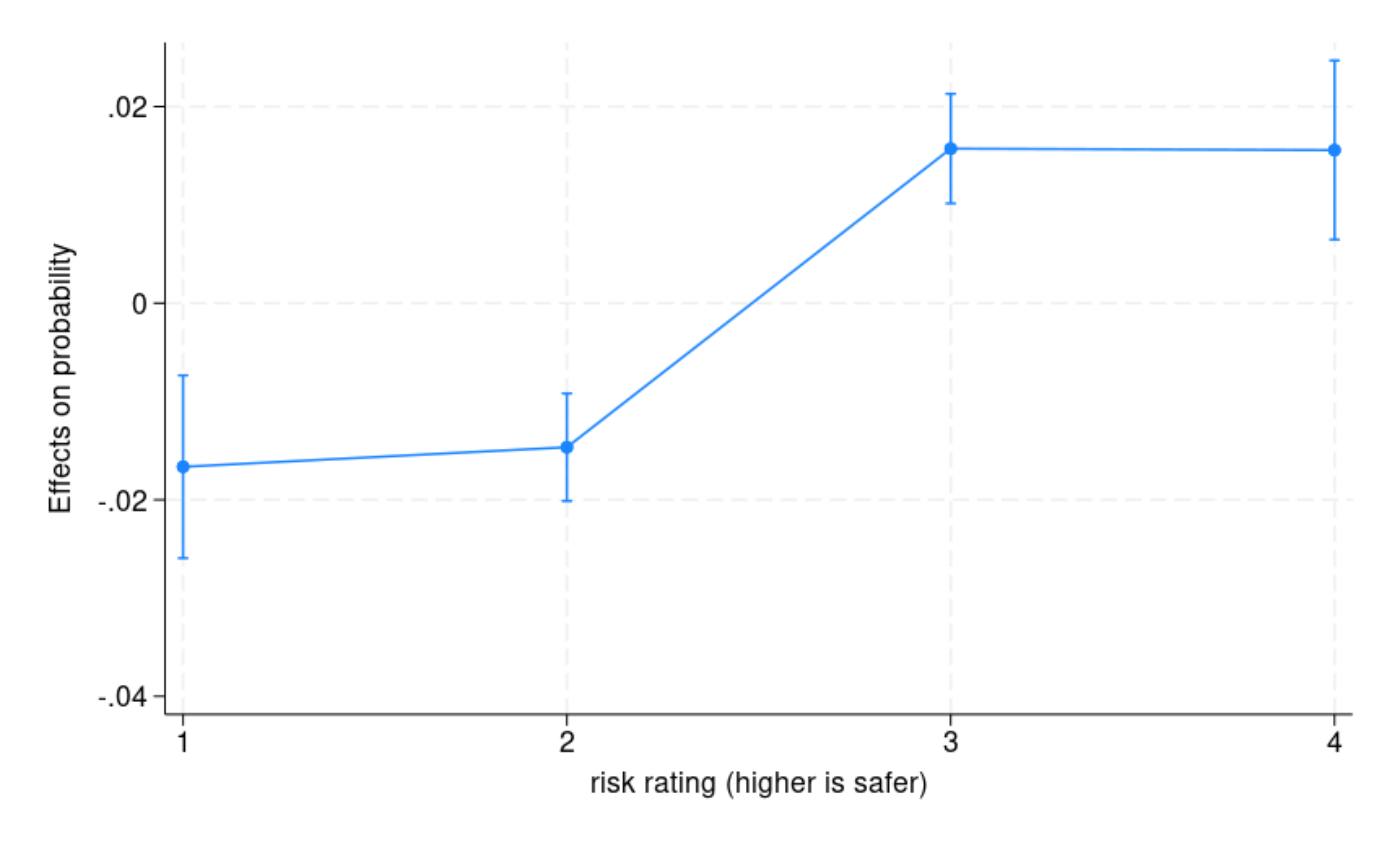
The paper shows that monetary policy reduces perceived tail risk for bank equity, encouraging banks to originate riskier loans to commercial and industrial borrowers.
Featured in No. 133 on 2 Oct 2026 · 4 days after release
- Released
- 28 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- RePEc:ces:ceswps:_12980
- Authors
- Xudong An et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).