RePEcTrading, Microstructure & Execution
One dollar, many prices: dealer-specific pricing of synthetic dollar funding
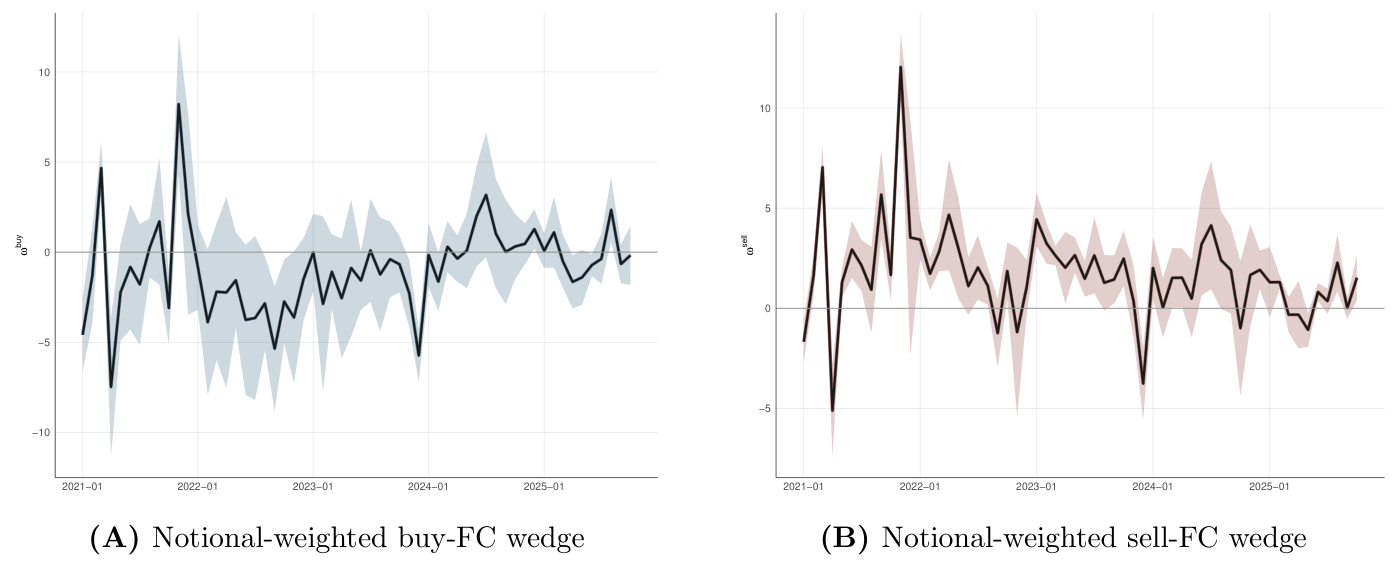
Comparing FX forwards in identical currency pairs and maturities, the study finds large pricing variation across dealers reflecting clientele and pricing power rather than funding costs.
Featured in No. 133 on 2 Oct 2026 · 4 days after release
- Released
- 28 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:boe:boeewp:023631
- Authors
- Marco Grotteria and Alex Kontoghiorghes
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).