US monetary policy, macroeconomic news and the global secular decline of interest rates
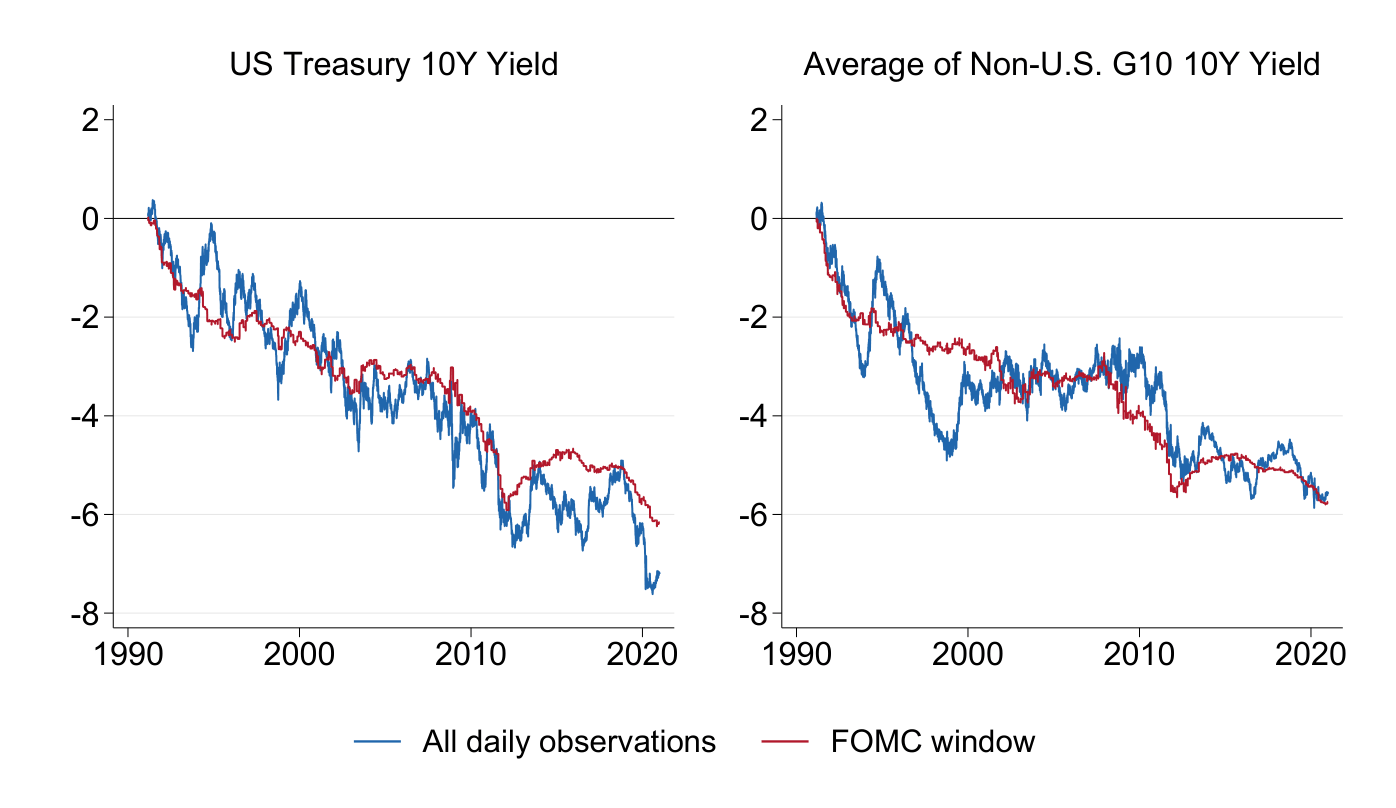
The global fall in long-term rates since the 1990s was driven largely by yield changes during Fed announcement windows, operating through expected short-rate paths rather than term premia.
Featured in No. 140 on 20 Nov 2026 · 4 days after release
- Released
- 16 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 4 of 5
- Identifier
- RePEc:bis:biswps:1393
- Authors
- Boris Hofmann et al.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).