Geopolitical risk and emerging market sovereign risk premia
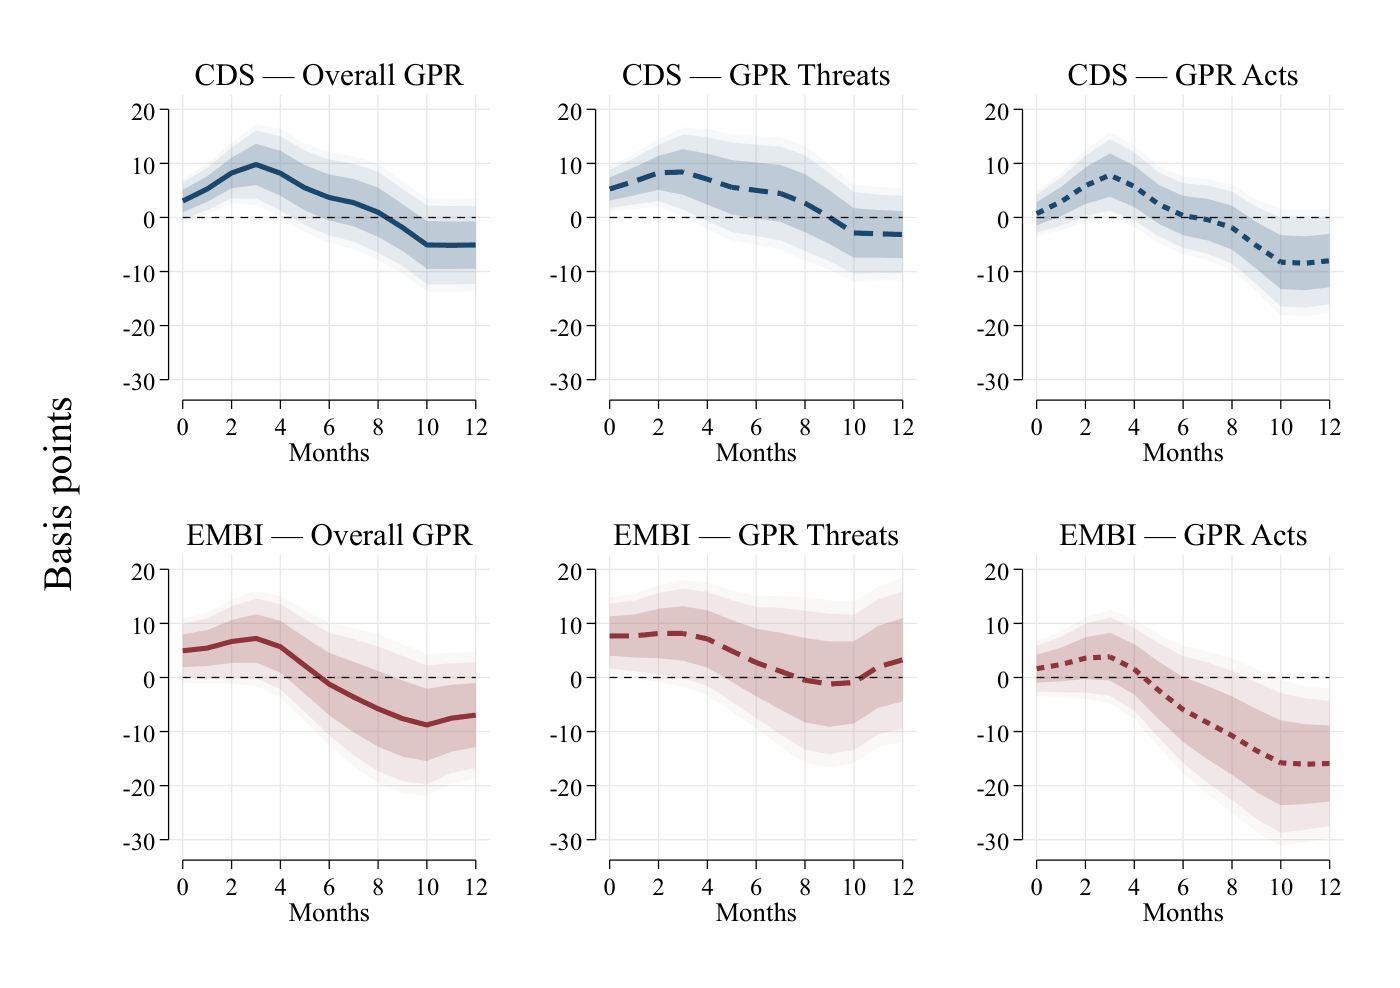
The study finds that geopolitical risk raises sovereign credit spreads in emerging markets, with threats having larger effects than acts, and responses shifting substantially after the Ukraine invasion.
Featured in No. 133 on 2 Oct 2026 · 9 days after release
- Released
- 23 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:bis:biswps:1368
- Authors
- Fredy Gamboa and Jose Vicente Romero
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).