What Volatility Reveals: Agnostic Identification of Exchange Rate and Treasury-Market Dynamics in Inconvenient Times
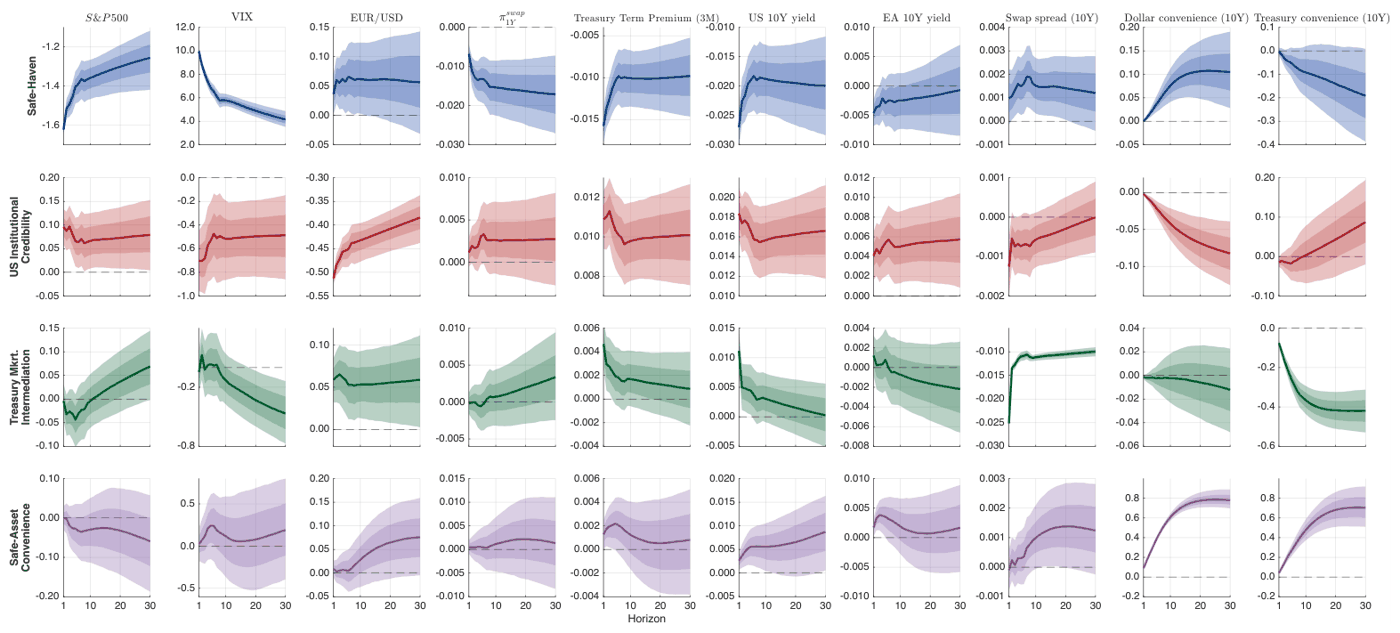
Volatility and kurtosis reveal that dollar depreciation and rising Treasury yields reflect multiple distinct shocks rather than a single tariff announcement shock.
Featured in No. 134 on 9 Oct 2026 · 4 days after release
- Released
- 5 Oct 2026
- First featured
- No. 134 · 9 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- RePEc:bde:wpaper:2629e
- Authors
- Lucas ter Steege and Sofia Velasco
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).