A joint framework for SPX, VIX and VXX
A unified model specifies VIX dynamics and recovers SPX variance from the requirement that its expected thirty-day average equals squared VIX, enabling joint calibration across equity and volatility markets.
Featured in No. 140 on 20 Nov 2026 · on release day
- Released
- 20 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2611.25047
- Authors
- Martino Grasselli et al.
Abstract
From arXiv (CC0).
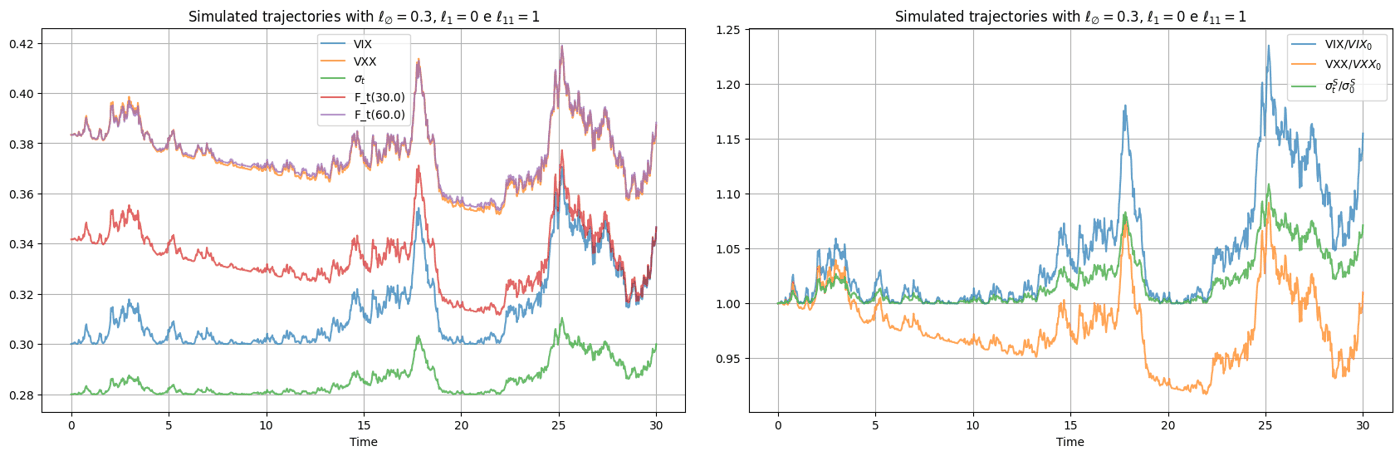
Options on VXX bring the dynamics of the VIX futures curve into the joint SPX-VIX calibration problem. We construct a common model by specifying the VIX and then recovering instantaneous SPX variance from the requirement that its risk-neutral conditional expected average over the next thirty days equals the squared VIX. With truncated signatures of time-extended polynomial diffusions, this recovery reduces to finite-dimensional linear algebra and gives explicit access to the futures underlying VXX. The same specification therefore governs equity variance and rolling volatility exposure. To accommodate flexible specifications while respecting variance nonnegativity, we develop a regularized model and quantify the pricing errors of its tractable VIX and VXX proxies. Applications to short-dated option smiles illustrate joint calibration across the three markets, with Monte Carlo estimates of the proxy error bounds well below quoted bid-ask spreads.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).