Beyond Strike Remapping: Conditional-Gamma Pricing of Leveraged ETF Options under Local Volatility
The conditional-Gamma method prices leveraged ETF options by conditioning on terminal returns, achieving a 158- to 236-fold speed-up over a benchmark PDE.
Featured in No. 140 on 20 Nov 2026 · 2 days after release
- Released
- 18 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2611.22604
- Authors
- Guolin Chen et al.
Abstract
From arXiv (CC0).
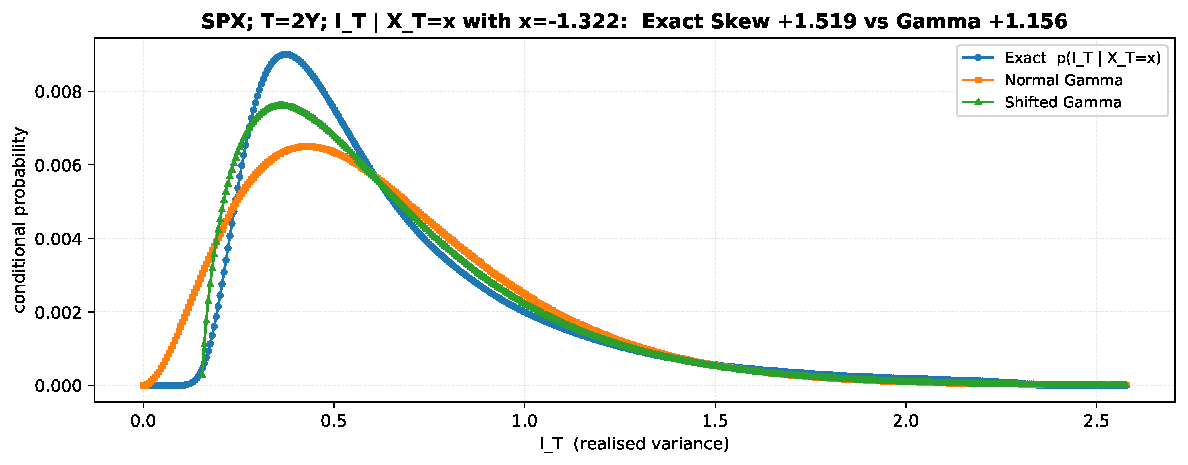
Options on leveraged ETFs (LETFs) are priced and hedged off the LETF volatility surface, but path-dependent variance drag makes that surface difficult to build consistently with the underlying index smile. We study three methods for constructing it: a closed-form first-order strike remapping, a new conditional-Gamma method, and a two-dimensional joint-law PDE that makes no distributional assumption and serves as the benchmark. The conditional-Gamma method is our main contribution. It conditions on the terminal underlying return, which preserves the state dependence of variance drag that a single remapped strike discards. Three one-dimensional forward PDEs under a calibrated local-volatility model give the conditional mean and variance of integrated variance, and a Gamma law matched to these moments keeps realised variance non-negative and prices the option in closed form. A shifted-Gamma variant that also matches the conditional third moment gives its clearest gains for inverse products at longer maturities, and a Gamma-mixture extension covers the full range of conditional skewness compatible with non-negative realised variance. On S&P 500 and Nikkei 225 surfaces the conditional-Gamma smile tracks the benchmark closely at every leverage tested, including the wings where the strike remapping drifts. A full LETF smile takes 0.85-1.42 seconds against 197-224 seconds for the benchmark, a 158- to 236-fold speed-up. Against listed TQQQ quotes the conditional-Gamma smile lies inside the market bid-ask at most strikes.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).