Directionally Correct Views in Portfolio Optimization
The research shows that even small amounts of directionally correct expert information materially improve portfolio allocations in both classical and machine-learning frameworks.
Featured in No. 136 on 23 Oct 2026 · on release day
- Released
- 23 Oct 2026
- First featured
- No. 136 · 23 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2610.31074
- Authors
- Ojas Kumar et al.
Abstract
From arXiv (CC0).
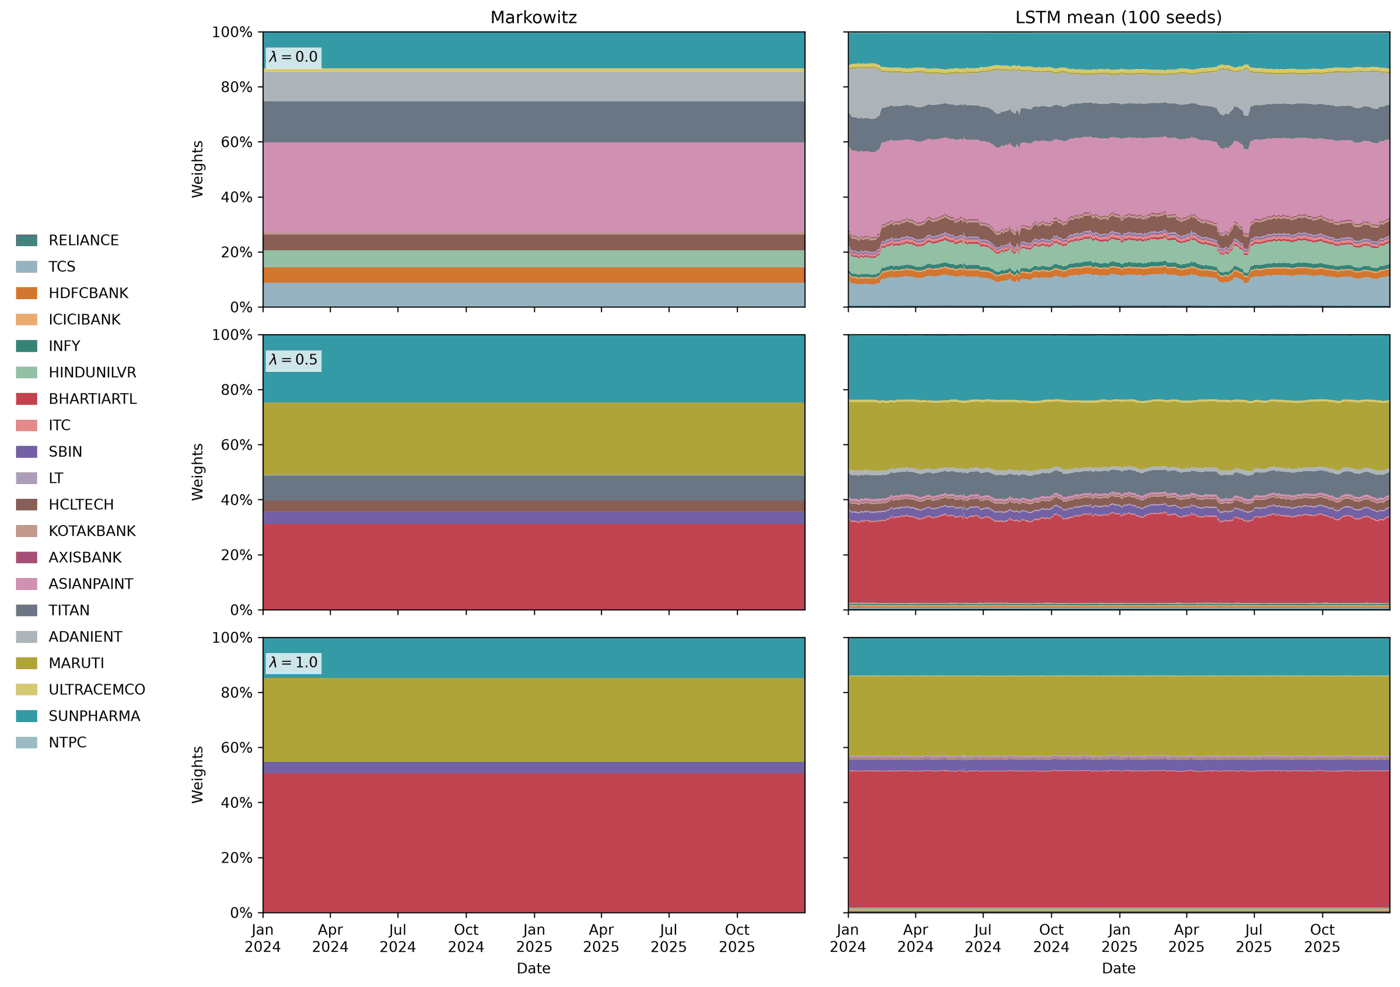
Portfolio optimization techniques often use historical data to estimate parameters for Markowitz-type or ML models. Effective allocation requires a way to align the available data with conditions expected over the investment horizon. Inspired by the Black-Litterman framework, we ask whether incorporating expert views leads to better portfolio allocations. In a simple Markowitz setting, we show that even a small amount of directionally correct information can materially improve investment decisions. We also discuss how expert views can be incorporated in end-to-end portfolio models using entropy-based ideas. Somewhat surprisingly, our empirical results indicate that simpler Markowitz-type model perform as well as an end-to-end model, once directionally correct experts are incorporated.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).