A Three-Factor Hull-White Scenario Generator for Macro-Financial Stress Forecasting
The study builds a three-factor Hull-White model that maps yield-curve paths into forecasts of equity returns, inflation and other macro variables, showing strong out-of-sample performance from 2017 to 2024.
Featured in No. 140 on 20 Nov 2026 · on release day
- Released
- 20 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2611.26200
- Authors
- Ahmad Qadi et al.
Abstract
From arXiv (CC0).
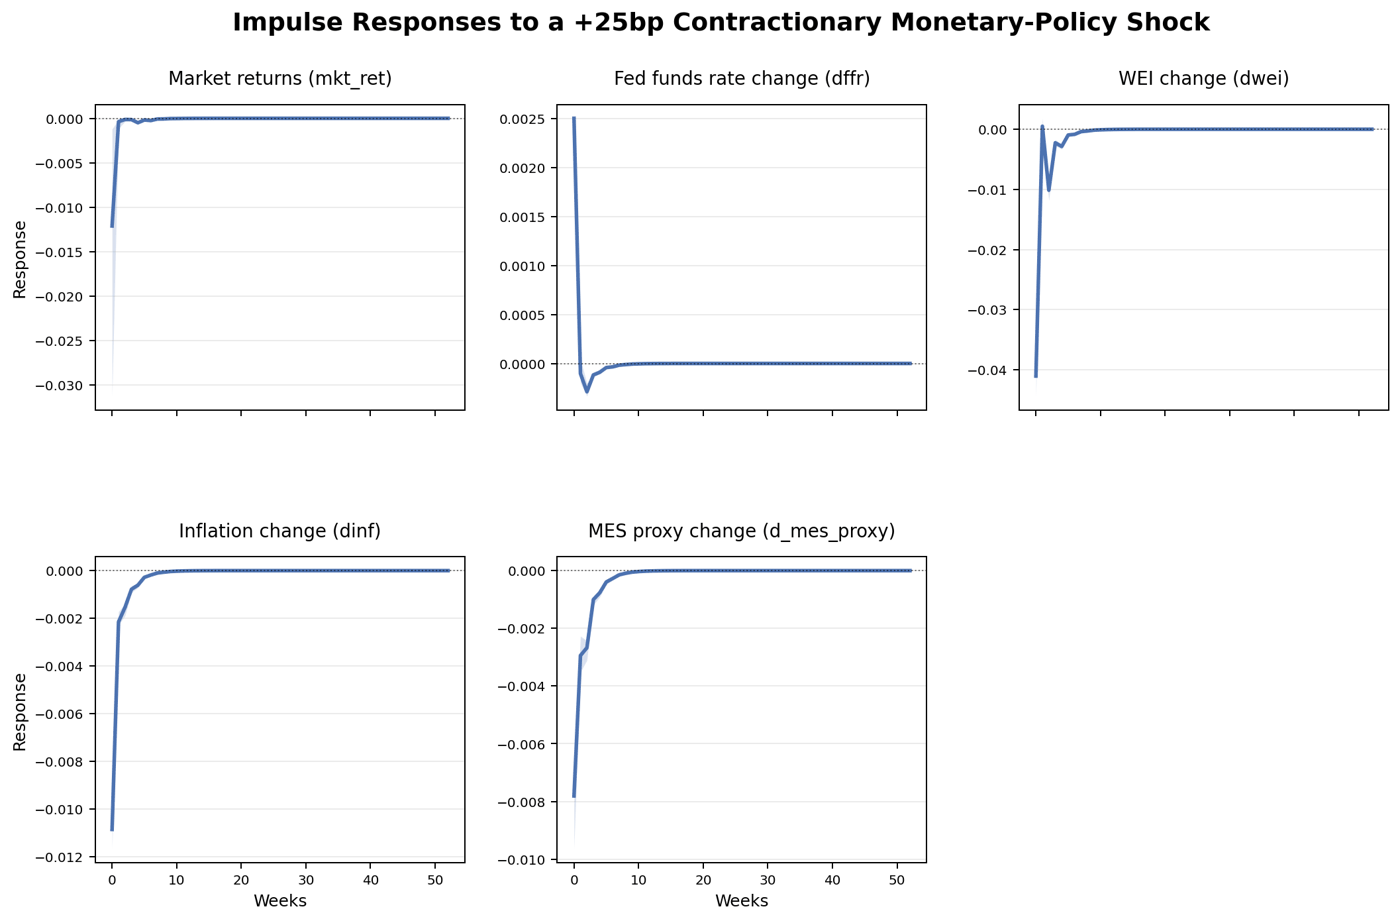
This paper builds a scenario engine that maps a yield-curve path into a distribution of macro-financial outcomes. A three-factor Hull-White model generates arbitrage-free curves whose factors are simulated under the physical measure, with an estimated and reported market price of risk. A Minnesota-prior VARX maps the simulated curves into weekly equity returns, the federal funds rate, the Weekly Economic Index, inflation and a bank Marginal Expected Shortfall proxy, with a sign-restricted policy shock adapted to weekly data. Evaluated out of sample from 2017 to 2024, the term-structure block has the lowest forecast error in 13 of 20 maturity and horizon cells, and the density forecasts are well calibrated for the continuously moving variables. At weekly frequency the curve carries no incremental information about these variables once their own lags are controlled for, so the engine's value lies in conditioning on a specified curve path, which no benchmark can do.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).