Statistical moments, risk weighting and percentiles of a loss distribution of a finite homogeneous credit portfolio; extending the Vasicek distribution
The study extends the Vasicek distribution to finite portfolios using moments and the Cornish-Fisher expansion, enabling adjusted risk-weighted asset calculations for small portfolios under 100 obligors.
Featured in No. 140 on 20 Nov 2026 · on release day
- Released
- 20 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2611.25881
- Authors
- Marco van der Burgt
Abstract
From arXiv (CC0).
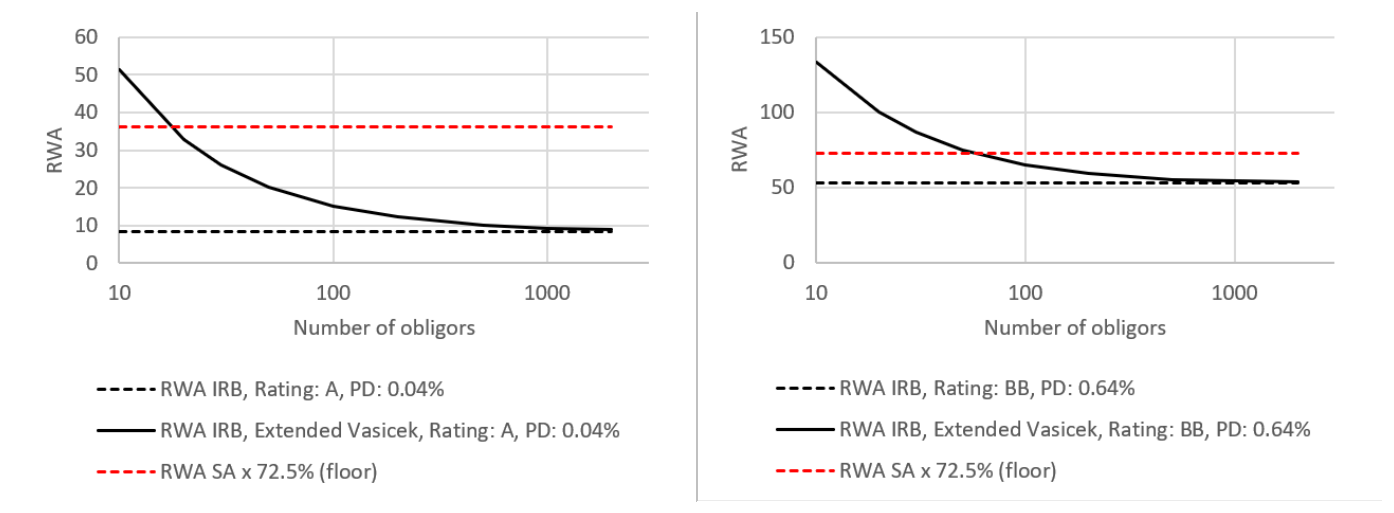
The Vasicek distribution assumes an infinite portfolio of identical obligors and forms the basis of the Basel III/IV Risk Weighted Assets (RWA) calculation. We derive the central moments of the loss distribution for a finite number (n) of obligors. We use these moments to calculate percentiles of the fraction (x) of defaulted obligors, via the Cornish-Fisher expansion and via a weighting method. Both methods are based on scaling the standard deviation in x by a capital multiple. The weighting method assumes that the capital multiple is linear in the central moments and leads to an Extended Vasicek distribution. We apply this distribution in calculating an adjusted RWA for small portfolios. Simulations show that this adjustment is only relevant for small portfolios of less than 100 obligors and that the Extended Vasicek distribution allows analytical risk capital calculations for portfolios with different rating grades, even when the number of obligors per rating grade is small.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).