Adaptive Tests of Pricing Restrictions with Observed and Latent Factors
Develops high-dimensional tests for asset pricing models with observed and latent factors, detecting when pricing errors can be explained by estimated latent-factor loadings.
Featured in No. 140 on 20 Nov 2026 · on release day
- Released
- 20 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2611.25549
- Authors
- Anlin Liu et al.
Abstract
From arXiv (CC0).
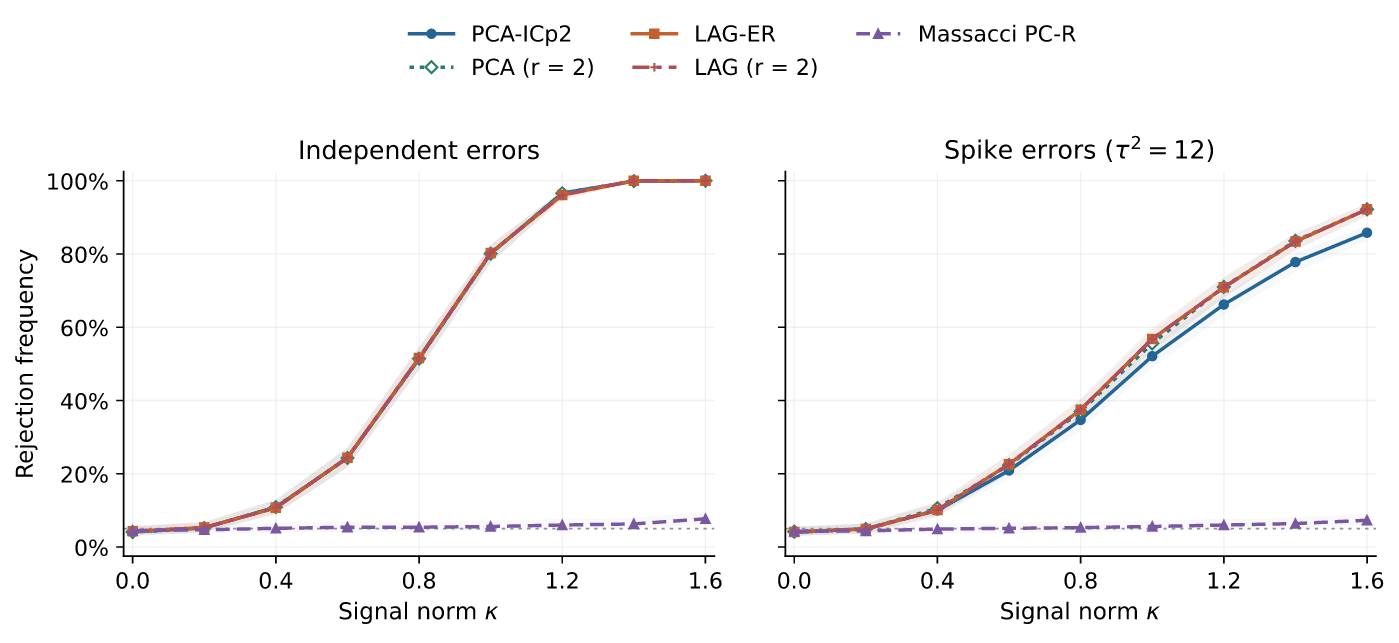
This paper develops a high-dimensional test for asset pricing models with observed and latent factors. The null hypothesis allows the intercepts from an observed-factor regression to be nonzero, provided that they lie in the latent factor loading space. We estimate the pricing errors in three steps: regress returns on the observed factors, extract latent factors from the lagged covariance structure of the regression residuals, and regress returns on both observed and estimated latent factors. The intercept from the final regression serves as the estimated pricing error. We construct Sum and Max tests based on the estimated pricing errors to detect diffuse and concentrated alternatives, respectively, and combine them using a Cauchy procedure. Under suitable regularity conditions, we establish the joint null distribution of the component statistics, their asymptotic independence, and their power against alternative hypotheses. We also propose a residual bootstrap and establish its first-order validity. Simulation studies examine the finite-sample performance of the tests under different pricing-error patterns and factor-number choices. An application to S\&P 500 stocks illustrates the use of the proposed framework in evaluating an observed-factor pricing model after latent-factor adjustment.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).