arXivLLMs & Text
Explaining Realized Returns: Roll's $R^2$ 40 Years Later
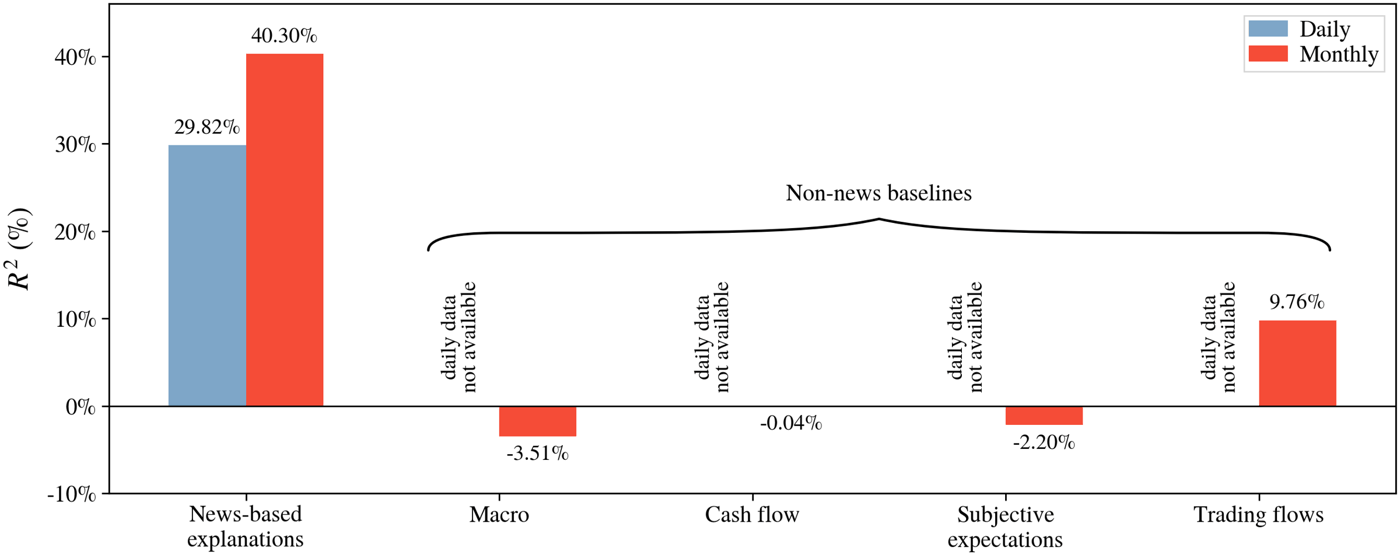
Using AI to extract reasons from market news summaries, the research shows that narrative explanations capture 30-40% of daily and monthly equity return variation, far exceeding conventional variables.
Featured in No. 140 on 20 Nov 2026 · 2 days after release
- Released
- 18 Nov 2026
- First featured
- No. 140 · 20 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 4 of 5
- Identifier
- arXiv:2611.22277
- Authors
- Bryan Kelly et al.
Abstract
From arXiv (CC0).
Can we explain asset price movements even with hindsight? Reinterpreting Roll's (1988) AFA Presidential Address, "$R^2$," as a modern empirical exercise, we show that conventional macroeconomic, cash-flow, expectations, and flow variables explain less than 10% (often with negative $R^2$) of monthly U.S. equity return variation out of sample and lack daily observations. We use generative AI to extract reasons stated in Wall Street Journal market summaries while filtering out price-related language. These reasons explain around 30-40% of daily and monthly return variation out of sample. Their content spans interpretable themes, including corporate news, macroeconomic conditions, monetary policy, sentiment, and geopolitics.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).