Specification LASSO and a Flexible Characteristics-Based Asset Pricing Model
A two-step LASSO-based method selects variables and model specification jointly in high dimensions, with oracle properties; applied to characteristics-based pricing, it reveals linear and nonlinear effects and interactions with firm size.
Featured in No. 138 on 6 Nov 2026 · 3 days after release
- Released
- 3 Nov 2026
- First featured
- No. 138 · 6 Nov 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2611.03391
- Authors
- Chaohua Dong et al.
Abstract
From arXiv (CC0).
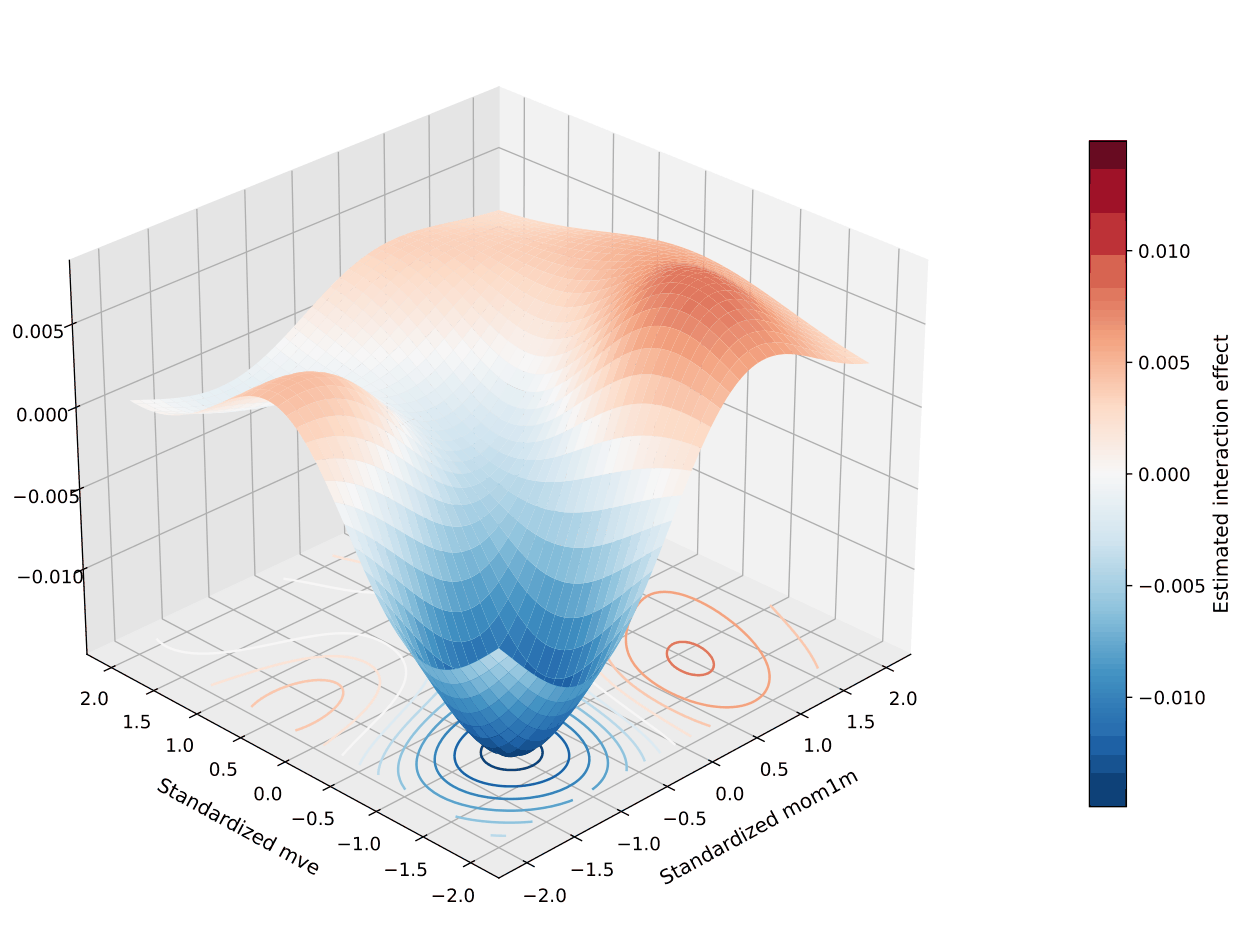
This paper studies a partially linear semiparametric additive model that allows for interactions among variables in high-dimensional settings. We propose the Specification LASSO (S-LASSO), a two-step method that integrates LASSO and Adaptive Group LASSO to simultaneously perform variable selection and model specification. Theoretically, we establish that S-LASSO possesses oracle properties in terms of selection consistency and asymptotic normality. Monte Carlo simulations confirm that S-LASSO outperforms existing alternatives across a variety of scenarios. Empirically, we apply S-LASSO to a characteristics-based asset pricing model, exploring the linear and nonlinear effects of asset-specific characteristics on cross-sectional returns, as well as their interactions with firm size.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).