arXivTrading, Microstructure & Execution
Event History Over Scale: Compact Transformers for Low-Latency Limit Order Book Forecasting
MBOFormer and MBOFusion, two causal transformers with under 70 kilobyte serialized state, predict limit order book price trends with sub-millisecond latency across three markets and four prediction horizons.
Featured in No. 134 on 9 Oct 2026 · 4 days after release
- Released
- 5 Oct 2026
- First featured
- No. 134 · 9 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- arXiv:2610.02917
- Authors
- David Schaurecker et al.
Abstract
From arXiv (CC0).
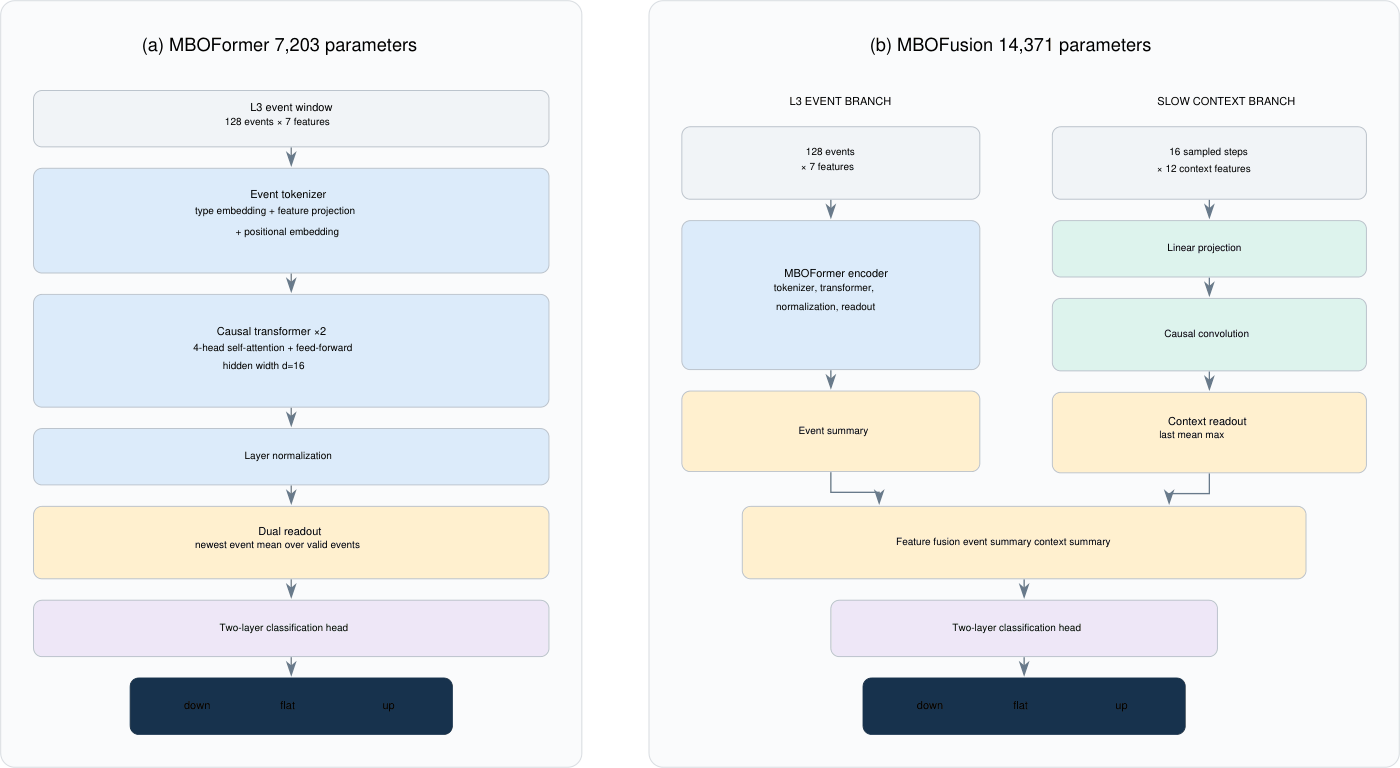
Short-horizon price-trend prediction from limit order books in equity and intraday electricity markets requires models that combine predictive quality with low single-sample latency and a small serialized model size to keep pace with rapid and continuous market updates. We introduce MBOFormer, a 7,203-parameter causal transformer, and MBOFusion, a 14,371-parameter extension with a slow temporal-context branch. Both models process market-by-order (level-3) histories of individual order submissions, cancellations, and executions. We compare them with level-2-based baselines that process sampled order-book snapshots and simple statistics instead of their underlying messages. Across three markets and four prediction horizons, our models achieve the highest mean macro-F1 in eleven of the twelve settings in a comparison against other benchmark models of varying sizes. Both our models achieve sub-millisecond median inference on a single Apple M2 CPU thread and have serialized state dictionaries below 70 kB. MBOFormer is 5.1x-8.1x faster than the million-parameter baselines at comparable predictive quality. Our results show that fine-grained market event history can reduce the need for model size under tight deployment constraints for short-term equity and electricity price forecasting tasks.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).