arXivEconometrics & Forecasting
DualCast: A Dual-Path Language Model for Bimodal Financial Time-Series Forecasting
Dual-path language model extended with financial tokens and news-conditioned revision achieves lowest error in 8 of 12 equity and energy forecasting settings across multiple horizons.
Featured in No. 133 on 2 Oct 2026 · 1 day after release
- Released
- 1 Oct 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2609.38197
- Authors
- Wentao Zhao et al.
Abstract
From arXiv (CC0).
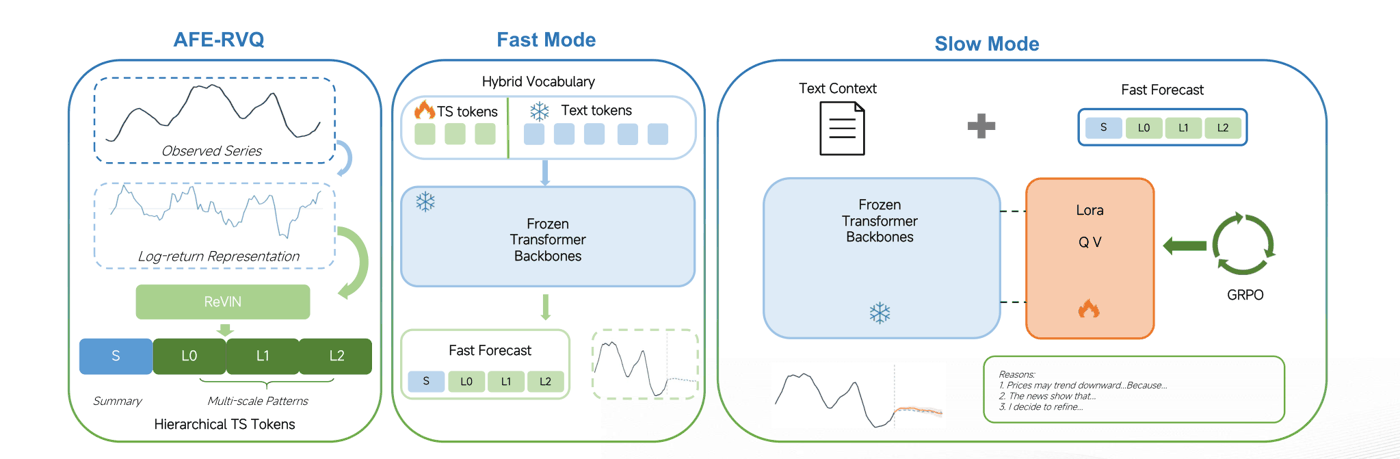
Financial time-series forecasting must capture price dynamics across heterogeneous assets while incorporating news available at prediction time. We introduce DualCast, a dual-path framework that extends a frozen language model with a discrete financial vocabulary. Each log-return patch is represented by a learned summary token and three residual shape tokens, preserving local drift and volatility while allowing shape patterns to be shared across assets. To improve codebook utilization, we develop adaptive frequency-equalizing residual vector quantization, which rebalances overloaded codewords without compromising reconstruction accuracy. The fast path trains only the new financial-token embeddings and output heads on a frozen Qwen3-8B backbone. A toggleable LoRA adapter enables a slow path that conditions on the fast forecast and news available at the forecast origin to produce a revised prediction. The reviser is initialized by supervised fine-tuning and further optimized with a return-space group relative policy optimization objective that rewards improvements over the fast forecast. In zero-shot evaluations covering equities and energy prices at five-minute, daily, and weekly resolutions, the slow path achieves the lowest mean absolute percentage error among the compared methods in 8 of 12 dataset-horizon settings, including every longest-horizon setting. News ablations indicate additional gains in most tested settings, although their magnitude varies across markets. DualCast thus combines a fast numerical forecaster with an optional text-conditioned revision mechanism.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).