arXivML & AI Methods
KiT: A Foundation Model for Financial Time-Series Forecasting using DiffusionTransformers
Diffusion transformer foundation model reformulates candlestick prediction as conditional trajectory generation, achieving 0.057 mean return RankIC across markets and timescales.
Featured in No. 133 on 2 Oct 2026 · 3 days after release
- Released
- 29 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- arXiv:2609.34507
- Authors
- Boyu Zhang and Haorui Li
Abstract
From arXiv (CC0).
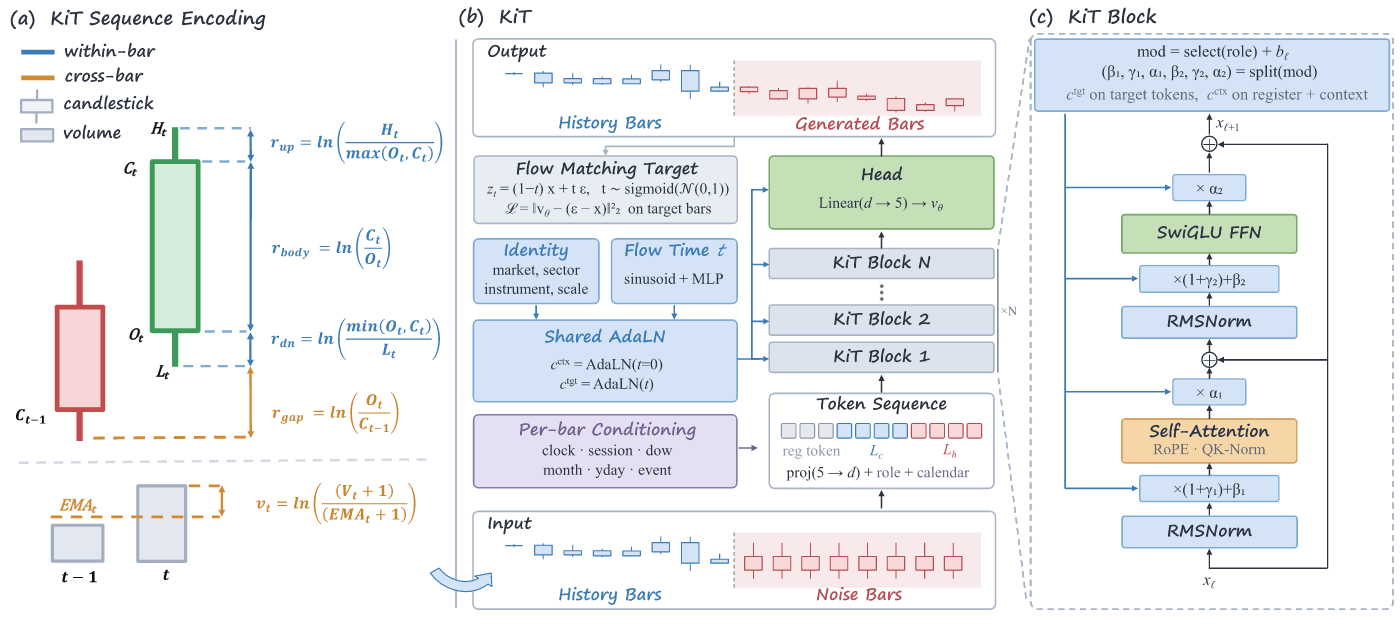
Financial candlestick forecasting is fundamental to quantitative investment, yet it remains exceptionally challenging due to extremely low signal-to-noise ratios and vast heterogeneity across markets and instruments. Existing approaches have largely attempted to introduce deep learning to capture hidden temporal features, but most adopt an auto-regressive formulation, which leads to error accumulation during inference. Meanwhile, general-purpose time-series foundation models are not tailored to the unique structure of k-line data and yield unsatisfactory performance on downstream candlestick forecasting tasks. To tackle these problems, we introduce KiT, a K-line Diffusion Transformer foundation model, and reformulate future prediction as conditional path generation via flow matching: given a historical context window, the model generates an ensemble of plausible future OHLCV trajectories. We pre-train KiT at multiple parameter scales on billions of candlestick bars spanning multiple markets and timescales. Across three markets and seven resolutions, KiT attains a mean return RankIC of 0.057 and a mean volatility RankIC of 0.66, leading at every timescale and outperforming both task-specific financial forecasters and general time-series foundation models. Code will be available at: https://github.com/Luciferbobo/KiT.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).