Taming the Greeks: Option Portfolios with Inductive Biases
A deep learning framework for options trading enforces portfolio-level delta neutrality and other risk constraints during training, improving risk-adjusted returns with lower directional exposure.
Featured in No. 133 on 2 Oct 2026 · 3 days after release
- Released
- 29 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 2 of 5
- Identifier
- arXiv:2609.33767
- Authors
- Wee Ling Tan et al.
Abstract
From arXiv (CC0).
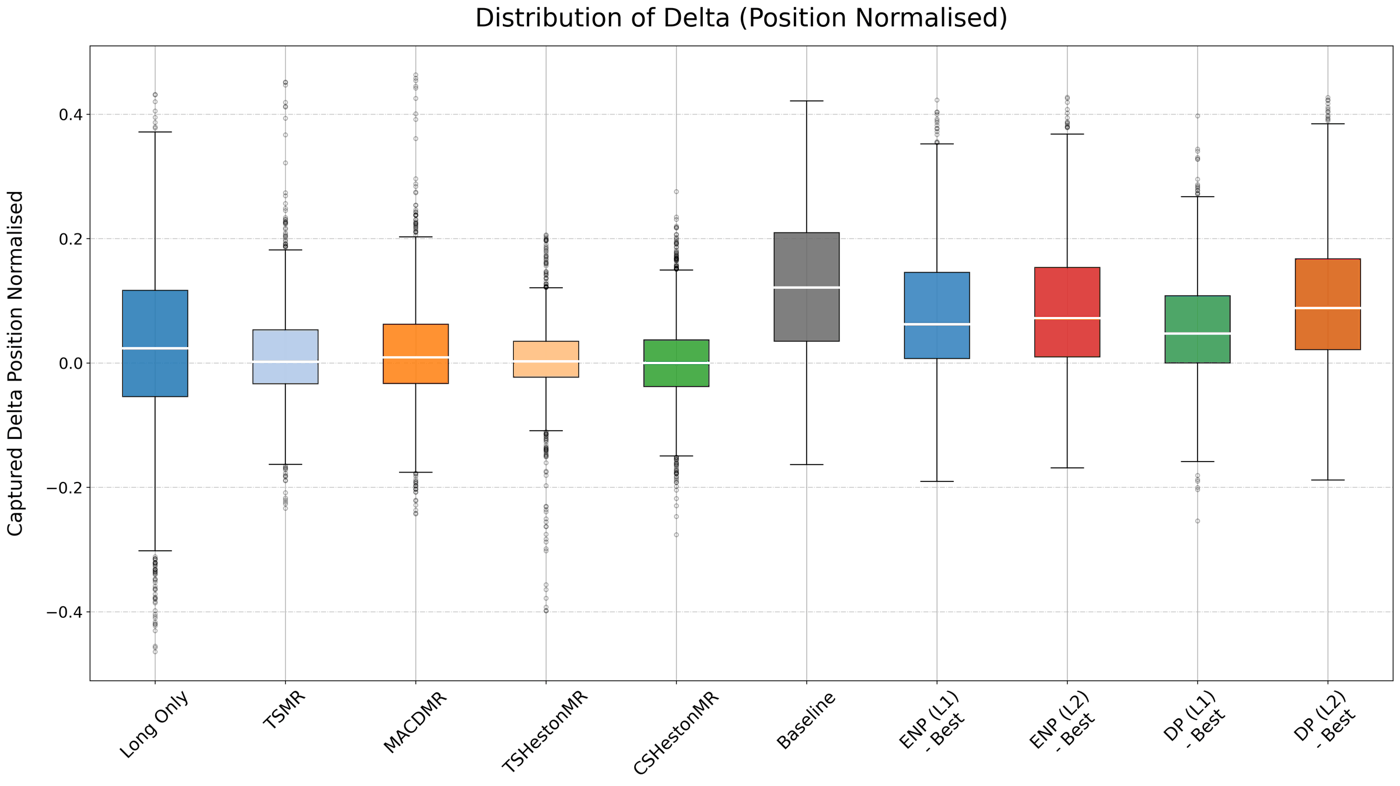
We present an end-to-end deep learning framework for systematic options trading that directly embeds hedging behavior through explicit control of portfolio-level risk exposures. While neural networks trained to optimize risk-adjusted performance have been shown to outperform traditional rules-based strategies, such approaches remain agnostic to the sensitivities of the resulting portfolios with respect to specific underlying risk factors. We propose a general training objective that combines a performance-driven loss with a differentiable risk-sensitivity penalty, enforcing neutrality to selected risk dimensions. Unlike reinforcement learning methods that approximate optimal hedging policies via simulated market dynamics, our framework operates entirely on historical data and jointly optimizes risk-adjusted returns and targeted risk constraints in a single learning problem. We instantiate the framework on static delta-neutral straddle portfolios with the penalty directed at first-order directional exposure, and evaluate two penalty variants -- an exposure-normalized penalty and a Greek-ratio drift penalty. Empirical results on Nasdaq 100 equity options demonstrate that appropriately calibrated regularization simultaneously improves out-of-sample risk-adjusted performance relative to an unregularized baseline while reducing realized directional exposure.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).