arXivTrading, Microstructure & Execution
UQ-LOB: Uncertainty-Aware Limit Order Book Mid-Price Forecasting
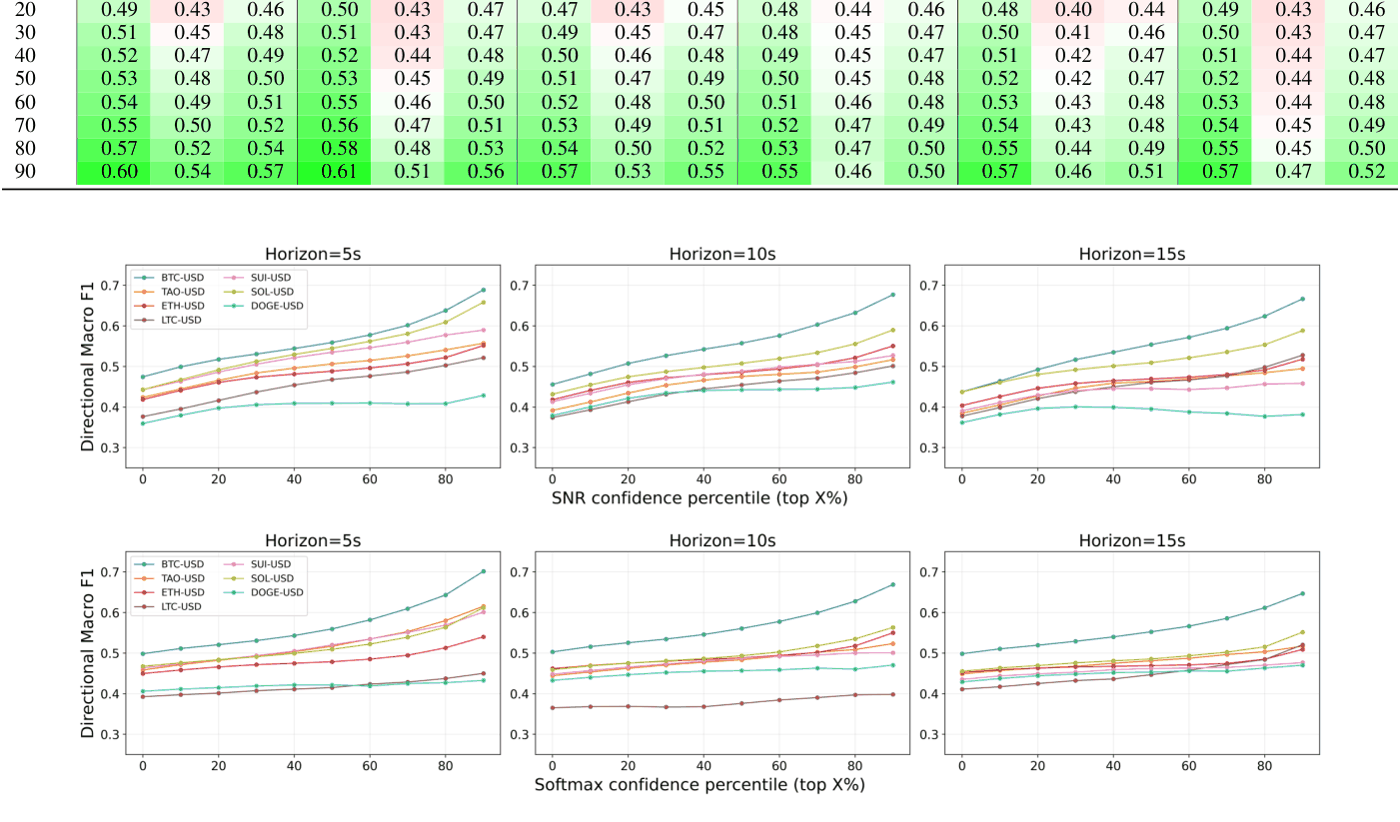
A lightweight module adds confidence estimates to limit-order-book forecasters, raising directional F1 by 0.11-0.15 when predicting the most confident 10% of trades.
Featured in No. 133 on 2 Oct 2026 · 4 days after release
- Released
- 28 Sep 2026
- First featured
- No. 133 · 2 Oct 2026
- Published in
- Not yet, as far as Semantic Scholar knows
- Fanfare
- 3 of 5
- Identifier
- arXiv:2609.31491
- Authors
- Derrick Gilchrist Edward Manoharan et al.
Abstract
From arXiv (CC0).
Forecasting short-horizon mid-price movements from limit order book (LOB) data is central to algorithmic trading, yet most deep LOB forecasters are point predictors: they output a direction or a displacement, but never indicate which of their forecasts can be trusted. We introduce UQ-LOB, a lightweight, encoder-agnostic uncertainty quantification module that attaches to any pretrained LOB encoder and, in the spirit of attentive neural processes, conditions each forecast on a context set of recently completed windows whose outcomes are already realised. The UQ-regression variant outputs a calibrated Gaussian over the future tick displacement, while the UQ-classification variant outputs a categorical distribution over down/up/stationary. Both expose a scalar confidence (predicted signal-to-noise ratio or class probability) that supports selective prediction. On 5.2 billion LOB events across seven cryptocurrency assets and horizons of 5, 10 and 15 seconds, UQ-regression attains near-nominal 68% interval coverage, and restricting to the most confident 10% of predictions raises directional macro F1 by 0.11-0.15 for UQ-regression and 0.05-0.11 for UQ-classification, at every horizon. On large, economically meaningful moves, the tightest confidence tier reaches a directional F1 of 0.88 (down) and 0.83 (up) at the 5-second horizon.
Citations and venue from Semantic Scholar (ODC-BY), refreshed weekly. Summary: Quant Letter (CC BY 4.0).